Yet Another Value BlogDoubao · 实盘不做把握 4/10不做原因:无增量信息
北京时间·🕒 发布 10-09 21:37:42·⟳ 抓取 07:59:59 +1d10h·⚡ 决策 10-11 08:02:14 +2m15s·16.4 天前
价值博客评论文章称消费级AI代理将颠覆OTA与零售,但无新增硬事实、不构成可交易事件
这是一篇Substack个人观点博客,不是公司公告、业绩、订单、监管或可核验的新增事实;其做空OTA论点基于长期DCF主观判断,引用的Amazon封禁(9月21日)和Expedia集成均为数周前旧闻,且市场闭市、无近期触发点,不具备事件驱动的交易edge。
📄 原文Yet Another Value Blog↗ 原文
Consumer agents: an ethics race, a prisoner’s dilemma, and the obvious OTA short
I’ve written [extensively about Muse and consumer agents over the past few weeks](https://www.yetanothervalueblog.com/p…
不做 Expedia Group(EXPE.US)
个人博客长期看空观点,无新增硬催化与量化冲击,且EXPE已与Muse集成、近期股价跑赢,不满足做空红线(强催化+置信≥4),周末亦无法成交
不做 Booking Holdings(BKNG.US)
AI代理颠覆OTA为多年慢变量,本文无新事实、无短期触发器,观点性评论不足以构成事件驱动做空edge
展开详情(成交明细 / 研究档案 / 原文全文 / 决策记录链)
研究档案
结论摘要
文章属于行业评论/投资观点,提出AI代理长期颠覆OTA与零售的慢变量论点,但无新增硬事实、无量化冲击、无近期催化,做空EXPE/BKNG不满足强催化红线,故不做。
关键理由
- 看空OTA依赖的是多年期现金流被侵蚀的主观推演,而非可在1-10个交易日定价的新增信息
- 作者自承论点'明显'且市场'打哈欠',恰说明缺乏预期差与短期触发器
主要风险
- 若后续出现OTA预订量被代理分流的硬数据或大型平台官方代理合作/封杀升级,该慢变量可能转为可交易事件,需重新评估
- 单一作者博客可能存在持仓利益冲突(Substack付费订阅、fiscal.ai推广链接),文中论点未提供独立数据支撑
反向证据
- 做空前查反向 · 来源 web · 影响 weakens
文中自己列出最强多头反证:EXPE/BKNG拥有海量专有旅行数据、欧洲长尾酒店关系、消费者习惯粘性,且EXPE已与Muse合作并近期跑赢;多空均为叙事,缺乏证伪或证实的硬数据
检索:Expedia Booking AI agent travel booking benefit data moat 2026 原文 ↗
先例如何影响了这次决策
对本次决策的影响:缺少事件型先例与短期触发器,支持AVOID而非凭主题观点开空
方向:无对齐先例:本条不是有明确时间锚点的公司事件,而是长期主题评论,无法用事件研究衡量
涨幅量级:不足:缺乏可锚定的首发催化与1/3/5日反应窗口,不宜据此设定做空幅度
形态:不适用
工具执行结果 · 成功 1 · 降级 0 · 失败 0 · 取消 0
- search_processed_events 成功 stock_tools HTTP · 9 ms
{"result": "search_processed_events:agent query=`amazon blocks meta muse ai agent retail site | consumer agents ethics guardrails prisoner dilemma retailers otas | consumer ai agents muse ota disruption expedia booking short thes`;结构化索引覆盖完整 72 小时;旧记录兼容扫描近 0.0/72 小时、0 条本臂决策(完整),返回 0 条候选。未命中只表示这些 agen
原文全文
展开原文 · 12,062 字
I’ve written [extensively about Muse and consumer agents over the past few weeks](https://www.yetanothervalueblog.com/p/if-muse-is-buying-your-running-shoes) ([including a plea for people to actually try them](https://www.yetanothervalueblog.com/p/before-you-fade-muse-use-it-for-72)!). I continue to experiment and play a lot with them; I will admit that my thoughts on them do wax and wane by the day from “damn, these are going to change everything” to “these are really cool, but it’s just going to make our lives a little easier, not reshape the consumer economy as we know it.”
As I’ve continued to play with them and think about how they’ll impact both the investing landscape and our lives, there are three somewhat interconnected thoughts that have just been popping into my head over and over. And, because they keep popping in my head, I figured I’d put some (figurative) ink down on paper on them. Those three thoughts are:
-
Incentives for lack of ethics / guardrails in consumer agents
-
Short term gain, long term pain: the prisoner’s dilemma for retailers versus agents
-
OTAs and the “obvious” disruptive shorts
Let’s dive in:
-
**Incentives for lack of ethics / guardrails in consumer agents**
The two agents I use the most are Muse and Claude Cowork. I mainly use Muse for personal stuff and I use Claude Cowork for business / investing stuff. I do dabble a little bit with ChatGPT and I have downloaded Grokbot, but for my purposes those are the two main ones.
One of the main differences I’ve noticed between Muse and Claude is that Claude is very strict on ethics. For example, if a website asks you to confirm you’re a human, Claude simply won’t do that for you. In contrast, Muse will either try to do it for you automatically or ask you if it should try to fool the website.
That’s a small example, but it applies to other things. For example, I once asked Claude to search a Substack (that I paid for!) for past references to a particular stock and then create a timeline with a summary of what was said on that stock and a link to the article. Claude told me it wouldn’t do that, saying it was worried about violating copyright law. I got into an argument with Claude (“I’m paying for this Substack; I’m just asking you to summarize and link to the mentions, and this is just for my internal notes and research and reference! How can this be copyright violation in any way?”) and it eventually did it for me, but it was a pain and put up a ton of barriers. In contrast, when I asked Muse to do it, it just went off and did the task no questions asked. That’s a little bit of a niche example, but it applies across the board / all the time; there are things that Claude simply won’t do or resists doing that Muse is happy to do.
Yet Another Value Blog is a reader-supported publication. To receive new posts and support my work, consider becoming a free or paid subscriber.
**
For most of the last few years, the AI race has been driven by being at the frontier. And maybe that is the path to riches; perhaps whoever can build a recursive self improvement AI first pulls away from everyone else and wins the AI race for all time. But Muse is winning a lot of market share not because it’s the best model but because it’s really easy to use **and **because it will basically just try to do everything you ask it to without question.
All of the AI players are competing for enormous prizes that are existential (both in a business sense and possibly for all of humanity). If one way to gain an edge in winning the “AI race” prize is to lower standards / just do stuff, eventually every lab is going to be forced to do that. It’s a very prisoner’s dilemma type thing; the moment one lab does it, all labs have to do it or they get left behind.
As a consumer, in the short run that’s pretty cool. How awesome would it be if an AI could click all those “are you a human” boxes for you across twenty different websites and automatically build a dashboard that let you manage your finances or your social life or something really easily?
But, in the long run, you could see a lot of reasons to be worried if each lab is incentivized to lower standards like that.
Speaking of prisoner’s dilemma….
-
**Short term gain, long term pain: the prisoner’s dilemma for retailers versus agents**
This may be anecdata, but I feel like I’ve seen an increase in the times Muse tells me “I can’t interact directly with that site…. want me to take control of your browser and pretend to be you and try anyway?” (yes, another example of the ethics / guardrail issue mentioned above). That issue started with[ Amazon, which banned Muse almost the moment it rolled out](https://www.bloomberg.com/news/articles/2026-09-21/amazon-blocks-meta-s-muse-ai-agent-from-its-retail-site), but I think it’s getting wider.
That ban creates an interesting prisoner’s dilemma for a host of businesses: consumer agents might destroy your business in the long run, but in the short run if every competitor in an industry bans agents then any one competitor could get a leg up by catering to agents.
A simple example will illustrate this: imagine that Expedia and Booking both think Muse is an existential risk to their business and refuse to work with it. They may very well be right…. but if a ton of consumers are using Muse, either Expedia or Booking could capture a lot of business in the short term by lifting the ban and being the de facto agent of choice for Muse. Yes, they’re risking their existential future, but in the short run the returns would be glorious…. and, indeed, [Expedia has done an integration with Muse already](https://www.expedia.com/newsroom/find-your-next-stay-with-the-help-of-your-personal-ai-agent-muse/)! And it is perhaps worth noting that EXPE’s stock has well outperformed BKNG’s stock over the past month as consumer agents have taken off; obviously one stock does not make a trend, but that’s exactly the type of outperformance you’d expect to see from a company that “took the deal” and stabbed everyone in the back in a prisoner’s dilemma!
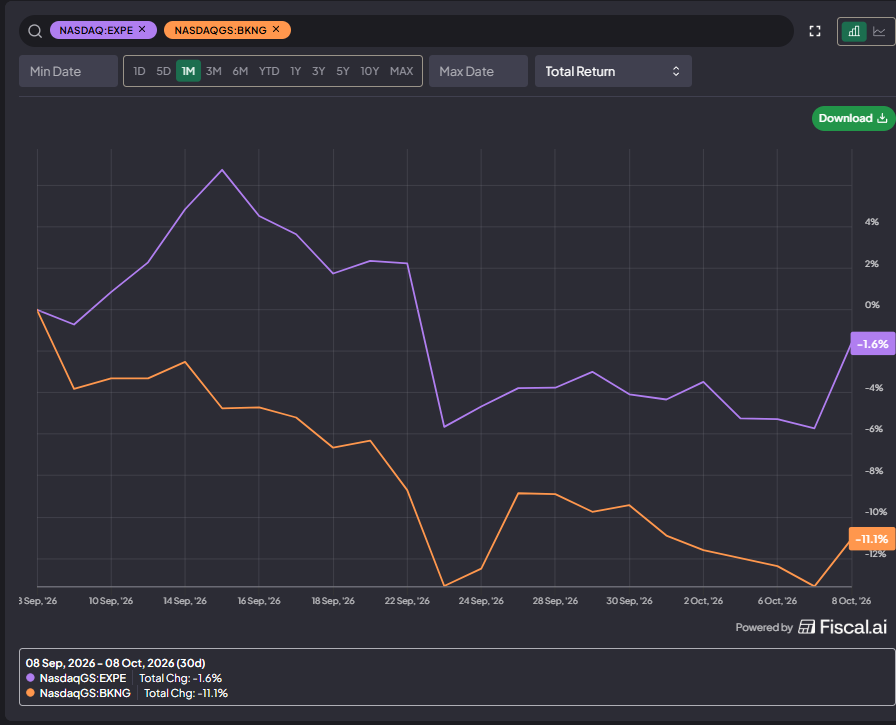
_Source: [fiscal.ai. You can get a 15% discount on fiscal.ai membership by signing up here](http://fiscal.ai/yav)_
You can imagine that issue across a host of businesses. One I like to think about is department stores / retailers. Obviously, broadline department stores are struggling; you don’t need me to pull up a chart of JCPenney or Sears to prove that to you (in fact, I can’t because they’re bankrupt / nonexistent anymore). But, for the remaining department stores, agents are clearly a disaster for their already under siege business. If you need undershirts or a pair of workout shorts, why go to macys.com and buy them when you could just ask your agent to search the internet for you and buy them from whoever is cheapest? So, if you’re Macy’s, you can’t work with an agent because it will kill you…. but if none of your competitors will work with them, maybe you can get one last windfall by stabbing them in the back and being the only one to work with agents?
In the short run, I think a lot of businesses are going to be blocking / banning consumer agents. But, in the long run, they’re going to have to work with them. Either the consumer agents will figure out ways to find end arounds to the blocks, or a competitor will realize they’re in a prisoner’s dilemma and stab everyone in the back to capture the profits[1](#footnote-1).
Which brings me to my last point….
-
**OTAs and the “obvious” disruptive shorts**
I have listened to a lot of podcasts from people who are building consumer agents (mainly the Muse and Instinct teams). Invariably, when asked about how to use consumer agents, the first use case mentioned will be using agents to save money on subscriptions or to easily plan and book travel.
I’ve talked to longs on EXPE / BKNG. When I do, they’ll mention a lot of things: there’s a long tail of European hotels that the OTAs have spent years cultivating that consumer agents won’t be able to reach / displace OTAs from easily, consumer habits are really sticky, the OTAs are taking a small fraction of the value and convenience they provide, in the short run agents will work with the OTAs and might even benefit them, etc.
I totally get all of those arguments[2](#footnote-2)… but, if I just eyeball Expedia and Booking, they’re trading for like 15x P/E. That valuation requires the business’s cash flows to have a very long life; for a business trading at a 15x P/E and growing in the mid to high single digits in the short term, ~80% of a business’s value comes from cash flows after year five in a DCF[3](#footnote-3).
Consumer agents are exploding in popularity, the companies behind them are investing billions of dollars into the product, and the first use case the people who are making them blurt out is “Use them as a super OTA!” I’m not sure how any investor looks at that fact pattern and thinks “yeah, I can generate alpha by buying an OTA and betting these cash flows are not just going to have a long life, but going to have a long life well above what the market is forecasting.”
Now, markets are competitive, and consumer agents have been with us for ~a month; that’s more than enough time for markets to digest a threat this obvious.... yet neither BKNG’s nor EXPE’s stock is showing any type of existential worries; again, both trade at ~15x and EXPE’s stock is basically flat on the year!
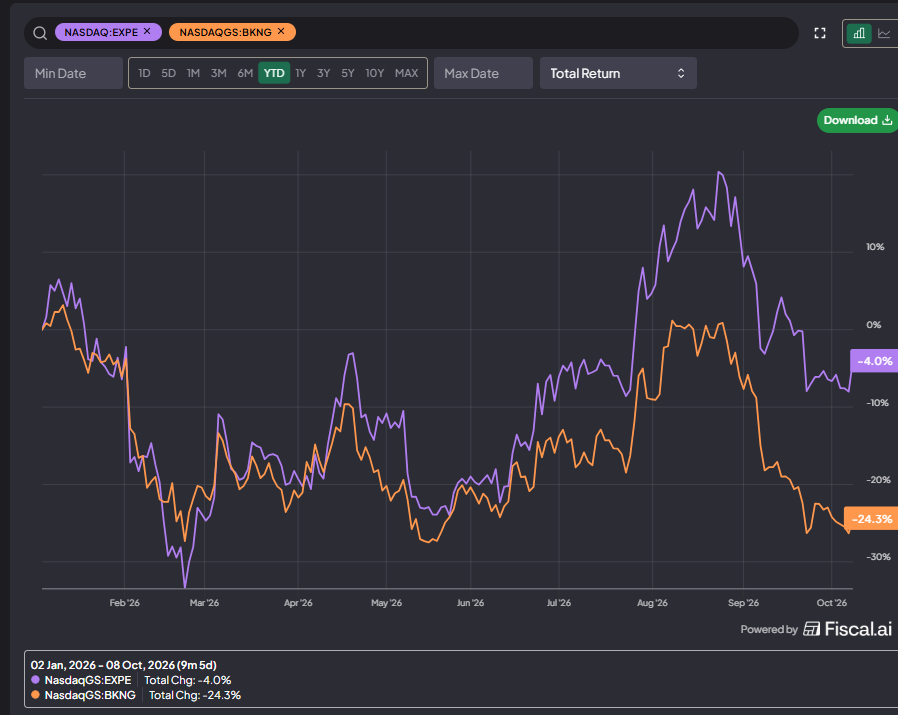
_Source: [fiscal.ai. You can get a 15% discount on fiscal.ai membership by signing up here](http://fiscal.ai/yav)_
It’s just hard for me to square “every consumer agent is targeting travel as a vector and raising billions” with “OTAs are trading like the future is rosy.” I realize that Google Flights and a host of other competitors never took off, and that the consumer agents might take a little more time / handholding to book a simple trip than an OTA right now…. but travel is clearly a killer use case for agents, and it just seems wild to me that the market is yawning here.
[1](#footnote-anchor-1)
This is a tangent that I’ve offhandedly mentioned before, and I could and should probably build a post around this point…. but, if you play the “everyone needs to work with agents” point out to its conclusion, consumer agents are just wildly, wildly deflationary as they will eat into basically every business’s margins through price comparing and constantly negotiating. In fact, I can’t think of a single consumer facing business that consumer agents are broadly bullish or margin supportive for!
[2](#footnote-anchor-2)
Actually, I intentionally didn’t use the best bull argument for the OTAs: EXPE and BKNG have billions of proprietary data points from historical consumer interactions, so AI creates existential risk but could also create a permanent moat if that data turns into a travel flywheel in some form. That could be true, but I’d suggest at 15x P/E the downside risks far, far outweigh the upside ones. I also would come back to basics: right now, EXPE and BKNG “control” the consumer and the distribution process; in the future world I’m talking about, the AI agent (like Muse) owns the consumer. I can’t think of a single product that has lost control of the consumer and then been worth more on the backend. Ask STRZ and the rest of the cable bundle how licensing content to Netflix and letting them have control of the consumer worked out!
[3](#footnote-anchor-3)
Lots of different assumptions on growth rates, reinvestment rates, interest rates, etc. could get you to different numbers here. But 80% is in the right ballpark!
As I’ve continued to play with them and think about how they’ll impact both the investing landscape and our lives, there are three somewhat interconnected thoughts that have just been popping into my head over and over. And, because they keep popping in my head, I figured I’d put some (figurative) ink down on paper on them. Those three thoughts are:
-
Incentives for lack of ethics / guardrails in consumer agents
-
Short term gain, long term pain: the prisoner’s dilemma for retailers versus agents
-
OTAs and the “obvious” disruptive shorts
Let’s dive in:
-
**Incentives for lack of ethics / guardrails in consumer agents**
The two agents I use the most are Muse and Claude Cowork. I mainly use Muse for personal stuff and I use Claude Cowork for business / investing stuff. I do dabble a little bit with ChatGPT and I have downloaded Grokbot, but for my purposes those are the two main ones.
One of the main differences I’ve noticed between Muse and Claude is that Claude is very strict on ethics. For example, if a website asks you to confirm you’re a human, Claude simply won’t do that for you. In contrast, Muse will either try to do it for you automatically or ask you if it should try to fool the website.
That’s a small example, but it applies to other things. For example, I once asked Claude to search a Substack (that I paid for!) for past references to a particular stock and then create a timeline with a summary of what was said on that stock and a link to the article. Claude told me it wouldn’t do that, saying it was worried about violating copyright law. I got into an argument with Claude (“I’m paying for this Substack; I’m just asking you to summarize and link to the mentions, and this is just for my internal notes and research and reference! How can this be copyright violation in any way?”) and it eventually did it for me, but it was a pain and put up a ton of barriers. In contrast, when I asked Muse to do it, it just went off and did the task no questions asked. That’s a little bit of a niche example, but it applies across the board / all the time; there are things that Claude simply won’t do or resists doing that Muse is happy to do.
Yet Another Value Blog is a reader-supported publication. To receive new posts and support my work, consider becoming a free or paid subscriber.
**
For most of the last few years, the AI race has been driven by being at the frontier. And maybe that is the path to riches; perhaps whoever can build a recursive self improvement AI first pulls away from everyone else and wins the AI race for all time. But Muse is winning a lot of market share not because it’s the best model but because it’s really easy to use **and **because it will basically just try to do everything you ask it to without question.
All of the AI players are competing for enormous prizes that are existential (both in a business sense and possibly for all of humanity). If one way to gain an edge in winning the “AI race” prize is to lower standards / just do stuff, eventually every lab is going to be forced to do that. It’s a very prisoner’s dilemma type thing; the moment one lab does it, all labs have to do it or they get left behind.
As a consumer, in the short run that’s pretty cool. How awesome would it be if an AI could click all those “are you a human” boxes for you across twenty different websites and automatically build a dashboard that let you manage your finances or your social life or something really easily?
But, in the long run, you could see a lot of reasons to be worried if each lab is incentivized to lower standards like that.
Speaking of prisoner’s dilemma….
-
**Short term gain, long term pain: the prisoner’s dilemma for retailers versus agents**
This may be anecdata, but I feel like I’ve seen an increase in the times Muse tells me “I can’t interact directly with that site…. want me to take control of your browser and pretend to be you and try anyway?” (yes, another example of the ethics / guardrail issue mentioned above). That issue started with[ Amazon, which banned Muse almost the moment it rolled out](https://www.bloomberg.com/news/articles/2026-09-21/amazon-blocks-meta-s-muse-ai-agent-from-its-retail-site), but I think it’s getting wider.
That ban creates an interesting prisoner’s dilemma for a host of businesses: consumer agents might destroy your business in the long run, but in the short run if every competitor in an industry bans agents then any one competitor could get a leg up by catering to agents.
A simple example will illustrate this: imagine that Expedia and Booking both think Muse is an existential risk to their business and refuse to work with it. They may very well be right…. but if a ton of consumers are using Muse, either Expedia or Booking could capture a lot of business in the short term by lifting the ban and being the de facto agent of choice for Muse. Yes, they’re risking their existential future, but in the short run the returns would be glorious…. and, indeed, [Expedia has done an integration with Muse already](https://www.expedia.com/newsroom/find-your-next-stay-with-the-help-of-your-personal-ai-agent-muse/)! And it is perhaps worth noting that EXPE’s stock has well outperformed BKNG’s stock over the past month as consumer agents have taken off; obviously one stock does not make a trend, but that’s exactly the type of outperformance you’d expect to see from a company that “took the deal” and stabbed everyone in the back in a prisoner’s dilemma!

_Source: [fiscal.ai. You can get a 15% discount on fiscal.ai membership by signing up here](http://fiscal.ai/yav)_
You can imagine that issue across a host of businesses. One I like to think about is department stores / retailers. Obviously, broadline department stores are struggling; you don’t need me to pull up a chart of JCPenney or Sears to prove that to you (in fact, I can’t because they’re bankrupt / nonexistent anymore). But, for the remaining department stores, agents are clearly a disaster for their already under siege business. If you need undershirts or a pair of workout shorts, why go to macys.com and buy them when you could just ask your agent to search the internet for you and buy them from whoever is cheapest? So, if you’re Macy’s, you can’t work with an agent because it will kill you…. but if none of your competitors will work with them, maybe you can get one last windfall by stabbing them in the back and being the only one to work with agents?
In the short run, I think a lot of businesses are going to be blocking / banning consumer agents. But, in the long run, they’re going to have to work with them. Either the consumer agents will figure out ways to find end arounds to the blocks, or a competitor will realize they’re in a prisoner’s dilemma and stab everyone in the back to capture the profits[1](#footnote-1).
Which brings me to my last point….
-
**OTAs and the “obvious” disruptive shorts**
I have listened to a lot of podcasts from people who are building consumer agents (mainly the Muse and Instinct teams). Invariably, when asked about how to use consumer agents, the first use case mentioned will be using agents to save money on subscriptions or to easily plan and book travel.
I’ve talked to longs on EXPE / BKNG. When I do, they’ll mention a lot of things: there’s a long tail of European hotels that the OTAs have spent years cultivating that consumer agents won’t be able to reach / displace OTAs from easily, consumer habits are really sticky, the OTAs are taking a small fraction of the value and convenience they provide, in the short run agents will work with the OTAs and might even benefit them, etc.
I totally get all of those arguments[2](#footnote-2)… but, if I just eyeball Expedia and Booking, they’re trading for like 15x P/E. That valuation requires the business’s cash flows to have a very long life; for a business trading at a 15x P/E and growing in the mid to high single digits in the short term, ~80% of a business’s value comes from cash flows after year five in a DCF[3](#footnote-3).
Consumer agents are exploding in popularity, the companies behind them are investing billions of dollars into the product, and the first use case the people who are making them blurt out is “Use them as a super OTA!” I’m not sure how any investor looks at that fact pattern and thinks “yeah, I can generate alpha by buying an OTA and betting these cash flows are not just going to have a long life, but going to have a long life well above what the market is forecasting.”
Now, markets are competitive, and consumer agents have been with us for ~a month; that’s more than enough time for markets to digest a threat this obvious.... yet neither BKNG’s nor EXPE’s stock is showing any type of existential worries; again, both trade at ~15x and EXPE’s stock is basically flat on the year!

_Source: [fiscal.ai. You can get a 15% discount on fiscal.ai membership by signing up here](http://fiscal.ai/yav)_
It’s just hard for me to square “every consumer agent is targeting travel as a vector and raising billions” with “OTAs are trading like the future is rosy.” I realize that Google Flights and a host of other competitors never took off, and that the consumer agents might take a little more time / handholding to book a simple trip than an OTA right now…. but travel is clearly a killer use case for agents, and it just seems wild to me that the market is yawning here.
[1](#footnote-anchor-1)
This is a tangent that I’ve offhandedly mentioned before, and I could and should probably build a post around this point…. but, if you play the “everyone needs to work with agents” point out to its conclusion, consumer agents are just wildly, wildly deflationary as they will eat into basically every business’s margins through price comparing and constantly negotiating. In fact, I can’t think of a single consumer facing business that consumer agents are broadly bullish or margin supportive for!
[2](#footnote-anchor-2)
Actually, I intentionally didn’t use the best bull argument for the OTAs: EXPE and BKNG have billions of proprietary data points from historical consumer interactions, so AI creates existential risk but could also create a permanent moat if that data turns into a travel flywheel in some form. That could be true, but I’d suggest at 15x P/E the downside risks far, far outweigh the upside ones. I also would come back to basics: right now, EXPE and BKNG “control” the consumer and the distribution process; in the future world I’m talking about, the AI agent (like Muse) owns the consumer. I can’t think of a single product that has lost control of the consumer and then been worth more on the backend. Ask STRZ and the rest of the cable bundle how licensing content to Netflix and letting them have control of the consumer worked out!
[3](#footnote-anchor-3)
Lots of different assumptions on growth rates, reinvestment rates, interest rates, etc. could get you to different numbers here. But 80% is in the right ballpark!
决策记录链 · 只追加
每次领取产生一条记录,重新决策追加一条并以 supersedes 指向被替代的记录(ADR 0014)。
6fa749eae9· 2026-10-11 08:02 · doubao / doubao-seed-evolving-latest-version · 策略包2226518bfdee当前