TMT BreakoutCodex · 实盘不做把握 5/10
北京时间·🕒 发布 05:26:48时区推断·⟳ 抓取 05:33:19·⚡ 决策 07-29 05:35:14 +1m55s·90.8 天前
TMT Breakout盘后复盘提到美股科技回调及STX、KLAC、NXPI等财报反应
这篇文章本身是盘后复盘和投资者情绪总结,不是单一低扩散的一手交易催化。
📄 原文TMT Breakout↗ 原文
TMTB EOD Wrap; Seagate (STX) KLAC NXPI First Takes
Good afternoon. **QQQs -1%** as more of the same unwind that we’ve seen the last 3 days continued. NDX and SOX both tes…
不做 Seagate Technology(STX.US)
财报利好明确但属于排期内披露,主流媒体已扩散且盘后已跳涨约7%至9%;在AI存储高预期和近期大波动背景下,次日追开盘缺少可回测的剩余edge。
不做 KLA Corporation(KLAC.US)
结果并非实质利空,只是低于较高买方预期;不满足强做空催化,且未核到可借券条件,不做。
不做 NXP Semiconductors(NXPI.US)
财报和指引小幅超预期但不足以改善叙事,方向偏中性;盘后下跌不能作为反手做空依据,不做。
展开详情(成交明细 / 研究档案 / 原文全文 / 决策记录链)
研究档案
消息传播链
- Seagate此前已公告将在7月28日美股收盘后发布FY2026四季度及全年业绩,事件时点本身可预期。
- WSJ报道STX四季度收入36.3亿美元、调整后EPS 5.71美元,并给出下一季度收入约41亿美元、调整后EPS 7.30美元。市场反应:报道提到盘后上涨,市场已对财报进行即时重定价。
- Barron's称STX盘后涨约8.8%,强劲财报由AI数据存储需求推动。市场反应:STX盘后已大幅跳涨。
- WSJ报道NXPI二季度收入和利润高于预期、三季度指引略高于市场预期,但盘后下跌约5.8%。市场反应:NXPI盘后下跌反映市场认为beat-and-raise不足以改变叙事。
关键理由
- 这篇文章本身是盘后复盘和投资者情绪总结,不是单一低扩散的一手交易催化。
- Seagate(STX.US)财报和指引确有正向 surprise,但属于排期内财报且盘后已跳涨约7%至9%,追开盘的剩余 edge 不清晰。
- KLAC.US、NXPI.US盘后下跌主要是买方预期过高或指引不够超预期,不构成强公司级实质利空做空催化。
主要风险
- STX.US若次日开盘仍能维持强承接,可能继续沿AI存储需求重估上行;本次不做的主要风险是踏空。
- 半导体板块处于连续回撤和FOMC前夕,盘后价格容易放大,次日开盘可能与盘后读数不同。
反向证据
- 做多前查反向 · 来源 web · 日期 2026-07-28 · 影响 weakens
STX财报前已有较高预期,盘后已大幅上涨,且市场担忧中国供给和AI存储需求可持续性。
检索:Seagate earnings July 2026 after hours stock jump high expectations AI storage competition China supply 原文 ↗ - 做空前查反向 · 来源 web · 日期 2026-07-28 · 影响 weakens
KLAC并非业绩暴雷,而是beat-and-raise低于较高买方预期;不满足强做空催化。
检索:KLA fiscal Q4 2026 beat raise buyside expectations after hours down 原文 ↗ - 做空前查反向 · 来源 web · 日期 2026-07-28 · 影响 weakens
NXPI收入和EPS均高于预期且Q3指引略高于Street,盘后下跌更多是预期差不足,不是公司级净损害。
检索:NXP Q2 2026 results Q3 guidance after hours down beat estimates 原文 ↗
原文全文
展开原文 · 9,399 字
Good afternoon. **QQQs -1%** as more of the same unwind that we’ve seen the last 3 days continued. NDX and SOX both testing 100MA for first time in months as the SOX is in a 25% drawdown with QQQs now in a 10% drawdown and only up 10% YTD. Semis still up 55% YTD despite a 30% drawdown which gives some good perspective despite the pain many investors are feeling in July. TMT Mo down another 10%+ today and in a 50% drawdown as semis were a sea of read with memory leading the way lower (**SNDK -14%; MU -9%**) as investors worry about 2nd derivative pricing slowing & Chinese supply. But plenty of other names down high single digits+ as well. Not much new to touch on the AI semis narrative/sentiment front that we didn’t touch on in yesterday’s EOD wrap.
This is all happening with SPX down less than 3% from ATHs and AAPL hitting ATHs. Internet got the big bid today with mid cap names rallying (**DASH +6%, CHWY +5%; CART +3.5%** and even **SPOT/NFLX +3%** catching a bid) while hyperscalers languished again (**META/AMZN flattish** with **GOOGL +2%**). Software continued to be a beneficiary of the unwind & narrative change (open-source/lower model costs debate favors better margins for the SaaS players): **HUBS +7%; WDAY +8%; MNDY +6% NOW +5%** etc. **PLTR -6%** after Clev flagged below street commercial growth in Q2 and **DOCN -6%** getting looped with AI semis the big losers.
A quick snapshot of sentiment among investors right now:
_TMTB Slack_
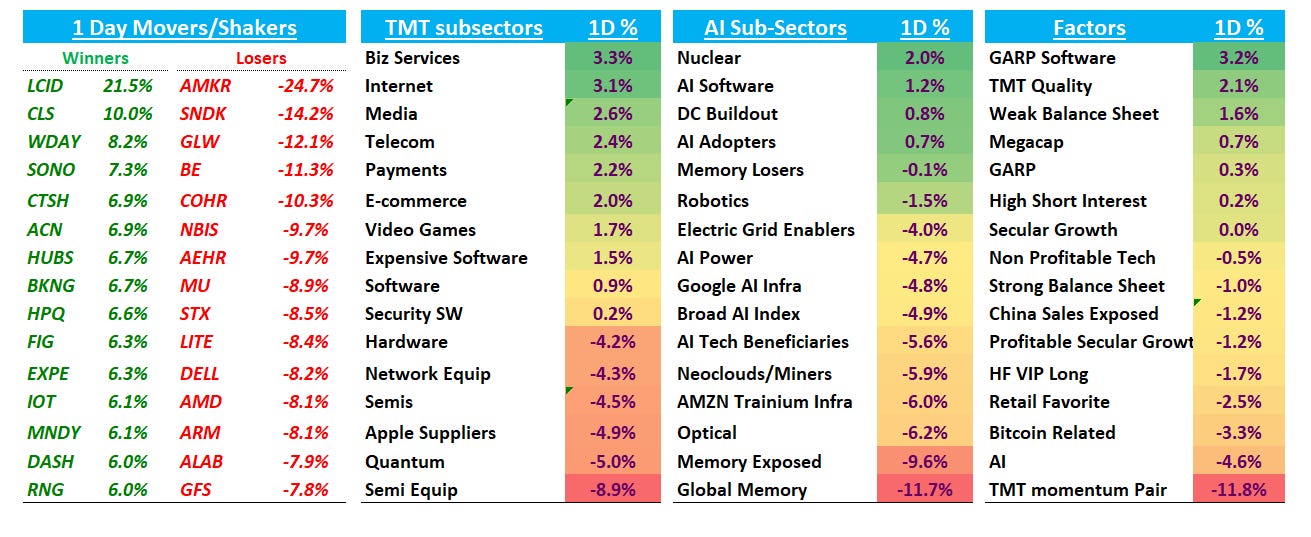
Arun — who is always great at coming up with good mental models to frame outcomes/distributions — [wrote a great post](https://tmtbreakout.slack.com/archives/C0A7X6WKVB2/p1785264727618709) in TMTB Slack that’s worth a full read, which followed up on the thread we called out yesterday regarding what’s plaguing the AI trade. Great discussion in that thread from others as well. Here’s a brief summary of Arun’s points from Claude:

A few positive price action tea leaves on the earnings front amidst the carnage in semis: **CLS +10%** held its gains and more after a strong beat and raise; **CDNS +2%** finished green on a much better print as well; and **GLW -12%** finished higher than where it opened. Just flagging things in terms of change of character, which are a bit different than the massive green to red reversal we saw from INTC on Friday and sell the news reactions we’ve seen from AI semis over the past week. Still things aren’t pretty out there. We’ll see how **STX +5%** holds up tomorrow after putting up a set of good numbers (was +8% at one point).
We laid our thoughts on the trading environment in yesterday’s EOD wrap [here](https://www.tmtbreakout.com/p/tmtb-eod-wrap-236). TLDR: lower gross/sizing, patience, no overreacting either way, shorter duration trades. Key quote: *“It’s as tricky a trading environment as I’ve seen in a while — there are times to bask in the HOT AI SUMMER vibes and press the accelerator down. There are other times like now when it’s time to bask in the good ol’ outdoor summer vibes.” * As always, we keep an open-mind and will adjust when the market tells us to.
Some other interesting thoughts in TMTB Slack today:
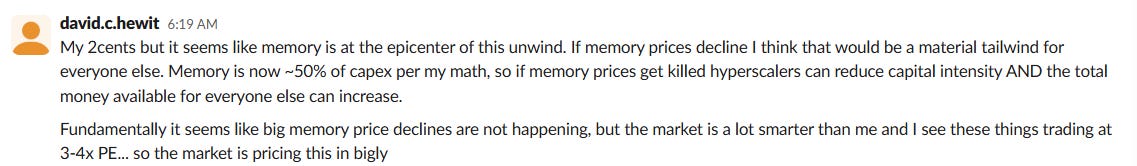
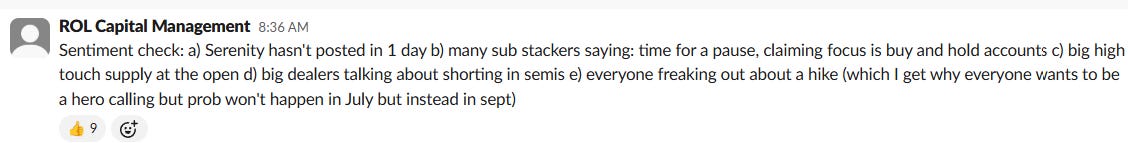
_TMTB Slack_
### **Post-close earnings:**
**STX +7%**: Looks solid with numbers at or above bogeys we heard coming in. Investors were looking for HSD EPS upside for the guide and got mid 20s. Nice GM upside for the Q.
**Q4:** Revenue $3.63B vs. Street $3.49B and bogeys of $3.60B+; GM 52.7% vs. street 50.4% and bogeys of 51.5%; EPS $5.71 vs. $5.08
**Q1 Guide:** Revenue $4.10B vs. Street $3.79B vs bogeys of $3.9B; EPS $7.30 vs. $5.81…I’m getting something close to an implied ~57% GM guide vs bogeys of 53.5%
*“Seagate’s strong fourth quarter exceeded our expectations for revenue and non-GAAP EPS, capping a fiscal 2026 in which we grew annual revenue 34%, delivered record profitability, and generated a record $3.1 billion in free cash flow. Our performance is being driven by robust cloud data center demand and disciplined execution, and we see the momentum continuing in 2027,” “As AI accelerates data generation and its value, we see durable long-term demand for mass capacity storage. Seagate is well positioned to address strengthening exabyte demand through our Mozaic platform and differentiated HAMR technology roadmap, enabling customers to scale efficiently while supporting our ability to drive profitable growth and value creation,”*
**KLAC -8%:** Results were a modest beat-and-raise, but upside fell short of elevated buyside expects with Q4 a touch light. KLAC raised its 2026 WFE outlook to the low-$150B range, though investors were already underwriting similar or higher levels.
**Q4:** Revenue $3.66B vs. Street $3.60B vs buyside expects of $3.7B; GM 62.4% vs. 61.8%; EPS $1.05 vs. $1.00
**Q1 Guide:** Revenue $4.00B vs. Street $3.91B vs buyside $4.05B; GM 62.5% vs. 61.9%; EPS $1.16 vs. $1.1
*
"KLA's June quarter results reinforce that the trends driving our growth are strengthening, and we see momentum across our business accelerating in the second half of calendar 2026 and continuing through 2027," said Rick Wallace, president and CEO of KLA Corporation. "KLA remains uniquely positioned on the critical path of AI infrastructure expansion, where the increasing number and sophistication of leading-edge designs across foundry/logic and the rising complexity and performance specifications in memory are driving greater demand for process control. In addition, the AI infrastructure buildout is also driving new growth opportunities in advanced packaging where KLA's market-leading process control product portfolio is well positioned."*
**NXPI -5%;** Results were mostly in line, with the Q2 beat driven primarily by Industrial rather than Auto. The Q3 revenue guide implies ~7% q/q growth at the midpoint but only ~1% upside to Street, unlikely to drive meaningful estimate revisions or improve sentiment despite NXPI’s valuation discount to analog peers. Sentiment was low here vs. other analogs and positioning skewed short into the print, but on surface doesn’t look good enough to change narrative.
**2Q:** Revenue $3.50B vs. Street $3.47B; GM 58.0% vs. 58.0%; EPS $3.61 vs. $3.52
**3Q Guide:** Revenue $3.75B vs. Street $3.71B; GM 58.5% vs. 58.6%; EPS $4.11 vs. $4.03
*“NXP delivered second-quarter revenue of $3.5 billion, up 19 percent year-on-year and 10 percent sequentially, with growth across all end markets and all regions. This performance reflects the strength of our company-specific growth drivers, particularly in Software-Defined Vehicles and Physical AI, with Data Center emerging as an additional growth engine. Our strong first-half results and third-quarter guidance reinforce our confidence in achieving our financial commitments to drive long-term shareholder value. Underlying these results, AI is moving from the cloud into the physical world — into vehicles, factories, and robots — and it lands directly in the markets where NXP has leadership positions. NXP's portfolio of processing, connectivity, and security solutions, positions us to enable next-generation edge intelligence for our customers,” said Rafael Sotomayor, NXP President and Chief Executive Officer.*
**SWKS -10%:** Results modestly beat, while Q4 guidance was broadly in line. Mobile demand remained healthy, with Broad Markets growing y/y on double-digit gains in automotive and data center, though weak FCF and limited guidance upside has stock down.
**F3Q:** Revenue $935M vs. Street $926M; GM 44.9% vs. 45.0%; EPS $1.08 vs. $1.03
**F4Q Guide:** Revenue $1.01–1.06B vs. Street $1.03B; EPS $1.27 vs. $1.29
**VRNS -8%:** Revenue and earnings beat modestly, while Q3 guidance and the full-year outlook were raised. However, SaaS net-new ARR excluding conversions of $31.5M missed the ~$37M buyside bogey, overshadowing healthy new-logo momentum
**2Q:** Revenue $180M vs. Street $176.8M; SaaS revenue $171.7M vs. $169.5M; SaaS ARR $726M vs. $784.4M
**3Q Guide:** Revenue $185–188M vs. Street $186.1M; EPS $0.02–0.03 vs. $0.02
**FY Guide:** Revenue $735–739M vs. Street $734.4M; EPS $0.14–0.15 vs. $0.12; SaaS ARR $819–850M, raised from $814–845M
Gavin with a good take on hyperscaler credit spreads:

Not a ton to call out on individual stock level today that didn’t seem unwind driven so we’ll skip that see what tomorrow brings with the Fed meeting.
This is all happening with SPX down less than 3% from ATHs and AAPL hitting ATHs. Internet got the big bid today with mid cap names rallying (**DASH +6%, CHWY +5%; CART +3.5%** and even **SPOT/NFLX +3%** catching a bid) while hyperscalers languished again (**META/AMZN flattish** with **GOOGL +2%**). Software continued to be a beneficiary of the unwind & narrative change (open-source/lower model costs debate favors better margins for the SaaS players): **HUBS +7%; WDAY +8%; MNDY +6% NOW +5%** etc. **PLTR -6%** after Clev flagged below street commercial growth in Q2 and **DOCN -6%** getting looped with AI semis the big losers.
A quick snapshot of sentiment among investors right now:

_TMTB Slack_

Arun — who is always great at coming up with good mental models to frame outcomes/distributions — [wrote a great post](https://tmtbreakout.slack.com/archives/C0A7X6WKVB2/p1785264727618709) in TMTB Slack that’s worth a full read, which followed up on the thread we called out yesterday regarding what’s plaguing the AI trade. Great discussion in that thread from others as well. Here’s a brief summary of Arun’s points from Claude:

A few positive price action tea leaves on the earnings front amidst the carnage in semis: **CLS +10%** held its gains and more after a strong beat and raise; **CDNS +2%** finished green on a much better print as well; and **GLW -12%** finished higher than where it opened. Just flagging things in terms of change of character, which are a bit different than the massive green to red reversal we saw from INTC on Friday and sell the news reactions we’ve seen from AI semis over the past week. Still things aren’t pretty out there. We’ll see how **STX +5%** holds up tomorrow after putting up a set of good numbers (was +8% at one point).
We laid our thoughts on the trading environment in yesterday’s EOD wrap [here](https://www.tmtbreakout.com/p/tmtb-eod-wrap-236). TLDR: lower gross/sizing, patience, no overreacting either way, shorter duration trades. Key quote: *“It’s as tricky a trading environment as I’ve seen in a while — there are times to bask in the HOT AI SUMMER vibes and press the accelerator down. There are other times like now when it’s time to bask in the good ol’ outdoor summer vibes.” * As always, we keep an open-mind and will adjust when the market tells us to.
Some other interesting thoughts in TMTB Slack today:


_TMTB Slack_
### **Post-close earnings:**
**STX +7%**: Looks solid with numbers at or above bogeys we heard coming in. Investors were looking for HSD EPS upside for the guide and got mid 20s. Nice GM upside for the Q.
**Q4:** Revenue $3.63B vs. Street $3.49B and bogeys of $3.60B+; GM 52.7% vs. street 50.4% and bogeys of 51.5%; EPS $5.71 vs. $5.08
**Q1 Guide:** Revenue $4.10B vs. Street $3.79B vs bogeys of $3.9B; EPS $7.30 vs. $5.81…I’m getting something close to an implied ~57% GM guide vs bogeys of 53.5%
*“Seagate’s strong fourth quarter exceeded our expectations for revenue and non-GAAP EPS, capping a fiscal 2026 in which we grew annual revenue 34%, delivered record profitability, and generated a record $3.1 billion in free cash flow. Our performance is being driven by robust cloud data center demand and disciplined execution, and we see the momentum continuing in 2027,” “As AI accelerates data generation and its value, we see durable long-term demand for mass capacity storage. Seagate is well positioned to address strengthening exabyte demand through our Mozaic platform and differentiated HAMR technology roadmap, enabling customers to scale efficiently while supporting our ability to drive profitable growth and value creation,”*
**KLAC -8%:** Results were a modest beat-and-raise, but upside fell short of elevated buyside expects with Q4 a touch light. KLAC raised its 2026 WFE outlook to the low-$150B range, though investors were already underwriting similar or higher levels.
**Q4:** Revenue $3.66B vs. Street $3.60B vs buyside expects of $3.7B; GM 62.4% vs. 61.8%; EPS $1.05 vs. $1.00
**Q1 Guide:** Revenue $4.00B vs. Street $3.91B vs buyside $4.05B; GM 62.5% vs. 61.9%; EPS $1.16 vs. $1.1
*
"KLA's June quarter results reinforce that the trends driving our growth are strengthening, and we see momentum across our business accelerating in the second half of calendar 2026 and continuing through 2027," said Rick Wallace, president and CEO of KLA Corporation. "KLA remains uniquely positioned on the critical path of AI infrastructure expansion, where the increasing number and sophistication of leading-edge designs across foundry/logic and the rising complexity and performance specifications in memory are driving greater demand for process control. In addition, the AI infrastructure buildout is also driving new growth opportunities in advanced packaging where KLA's market-leading process control product portfolio is well positioned."*
**NXPI -5%;** Results were mostly in line, with the Q2 beat driven primarily by Industrial rather than Auto. The Q3 revenue guide implies ~7% q/q growth at the midpoint but only ~1% upside to Street, unlikely to drive meaningful estimate revisions or improve sentiment despite NXPI’s valuation discount to analog peers. Sentiment was low here vs. other analogs and positioning skewed short into the print, but on surface doesn’t look good enough to change narrative.
**2Q:** Revenue $3.50B vs. Street $3.47B; GM 58.0% vs. 58.0%; EPS $3.61 vs. $3.52
**3Q Guide:** Revenue $3.75B vs. Street $3.71B; GM 58.5% vs. 58.6%; EPS $4.11 vs. $4.03
*“NXP delivered second-quarter revenue of $3.5 billion, up 19 percent year-on-year and 10 percent sequentially, with growth across all end markets and all regions. This performance reflects the strength of our company-specific growth drivers, particularly in Software-Defined Vehicles and Physical AI, with Data Center emerging as an additional growth engine. Our strong first-half results and third-quarter guidance reinforce our confidence in achieving our financial commitments to drive long-term shareholder value. Underlying these results, AI is moving from the cloud into the physical world — into vehicles, factories, and robots — and it lands directly in the markets where NXP has leadership positions. NXP's portfolio of processing, connectivity, and security solutions, positions us to enable next-generation edge intelligence for our customers,” said Rafael Sotomayor, NXP President and Chief Executive Officer.*
**SWKS -10%:** Results modestly beat, while Q4 guidance was broadly in line. Mobile demand remained healthy, with Broad Markets growing y/y on double-digit gains in automotive and data center, though weak FCF and limited guidance upside has stock down.
**F3Q:** Revenue $935M vs. Street $926M; GM 44.9% vs. 45.0%; EPS $1.08 vs. $1.03
**F4Q Guide:** Revenue $1.01–1.06B vs. Street $1.03B; EPS $1.27 vs. $1.29
**VRNS -8%:** Revenue and earnings beat modestly, while Q3 guidance and the full-year outlook were raised. However, SaaS net-new ARR excluding conversions of $31.5M missed the ~$37M buyside bogey, overshadowing healthy new-logo momentum
**2Q:** Revenue $180M vs. Street $176.8M; SaaS revenue $171.7M vs. $169.5M; SaaS ARR $726M vs. $784.4M
**3Q Guide:** Revenue $185–188M vs. Street $186.1M; EPS $0.02–0.03 vs. $0.02
**FY Guide:** Revenue $735–739M vs. Street $734.4M; EPS $0.14–0.15 vs. $0.12; SaaS ARR $819–850M, raised from $814–845M
Gavin with a good take on hyperscaler credit spreads:

Not a ton to call out on individual stock level today that didn’t seem unwind driven so we’ll skip that see what tomorrow brings with the Fed meeting.
决策记录链 · 只追加
每次领取产生一条记录,重新决策追加一条并以 supersedes 指向被替代的记录(ADR 0014)。
这条决策早于决策账本(2026-10-08 起逐条追加),没有追加记录。