TMT BreakoutCodex · 实盘可交易 · 做多市场:美股▼ 亏 -4.94% · 已结算把握 5/10
北京时间·🕒 发布 20:45:04时区推断·⟳ 抓取 21:08:53·⚡ 决策 07-16 21:11:38 +2m45s·102.7 天前
TMT Breakout早报中捷普宣布15亿美元回购,约占当前市值4.5%
捷普(JBL.US)15亿美元回购相对334亿美元市值约4.5%,属于可量化资本回报而非纯叙事催化。
📄 原文TMT Breakout↗ 原文
TMTB Morning Wrap
*TMTB will be out on holiday beginning tomorrow through next week* Good morning. **QQQs -1%** as the Momentum/AI semis…
▼ 亏 -4.94%入场 07-16 盘前首笔 @313.74 → 离场 07-17 常规开盘 @298.60
日 K 取自复盘打分切片 · 蓝点/蓝虚线 = 纸面入场价 · 灰虚线 = 纸面离场 · 持有期红底 = 赚(价格在入场线上方)、绿底 = 亏
💡 交易逻辑15亿美元回购占市值约4.5%,回调后限价做多
怎么买 限价买入 不高于 321、仅下一个交易日,不成交作废
怎么卖 止盈 +3%(半仓)/+6%(清仓) · 止损 -4% · 时间止损 3日
不做 Lumentum(LITE.US)
券商上行催化观察本身方向偏多,但最新价当日跌7.71%、近20日跌21.44%,且卖方观点不是一阶公司催化;当前不追,等公司业绩或供给缺口被订单/指引确认。
不做 Arista Networks(ANET.US)
多家券商看好AI网络需求,但ANET市值约2165亿美元、消息属于预期强化而非新订单或指引上修;同日跌5.83%,短线edge不如可量化回购事件。
不做 台积电(TSM.US)
收入和资本开支强但毛利率低于多头门槛,事件方向混合且市场反应偏卖事实;超大市值主标的不做。
展开详情(成交明细 / 研究档案 / 原文全文 / 决策记录链)
分时走势
做多 JBL.US 捷普
建仓日早于近 30 天,只有日线图
成交明细 · 纸面
做多 JBL.US 捷普
| 收益状态 | -4.94% 已平仓 |
|---|---|
| 进场成交 | 2026-07-16 · 盘前首笔 · 07-16 20:49 北京 · @313.738 |
| 离场成交 | 2026-07-17 · 常规开盘 · @298.603 |
| 毛收益 | -4.82% |
| 成本 | +0.12% |
| 净收益 | -4.94% |
| 计入收益 | -4.94% |
| 建仓日 | 2026-07-16 · 进场不早于新闻时刻 + 2 分钟 |
| 契约提示 | LIMIT_AND_CHASE |
收益口径 event_time_plus_2min_10min_walk_open_topup_to_next_open_exchange_calendar_fill_model_local_notional_v9 · method_id m8db1cbc8f2d · 截至 2026-10-27 14:42
研究档案
🔎 新鲜度:最早出现 2026-07-16 · 扩散 medium · price-in 风险 medium ↗
消息传播链
- 研究早报列出“JBL announced $1.5B buyback, 4.5% of market cap”,属于可量化资本回报线索。市场反应:截至2026-07-16 13:09 UTC,JBL.US最新价319.18美元,较前收326.82美元跌2.34%。
- 2026-07-16 13:09 UTC市场反应Futu行情声称一手 · 未核验行情显示JBL未因该回购消息出现正向跳空,反而随AI硬件链回调,给限价低吸而非追高的窗口。市场反应:JBL.US 20日跌17.23%,距60日高点-25.59%。
关键理由
- 捷普(JBL.US)15亿美元回购相对334亿美元市值约4.5%,属于可量化资本回报而非纯叙事催化。
- 股价近20日跌17.2%、距60日高点约25.6%,回购在下跌后提供一定估值支撑,但当前AI硬件链整体承压。
- 历史美股回购授权类先例方向偏正面,6个类比样本+3日中位数约+3.6%、胜率约67%,但多与财报同日,不能机械外推。
主要风险
- 回购授权不等于立即执行,且TMT早报同篇显示AI半导体和硬件链正在去动量,可能压制JBL开盘承接。
- 当前信号来自研究早报转述,未在本轮核到公司一手公告链接;若公司公告口径或金额被证伪,应优先退出。
反向证据
- 做多前查反向 · 来源 stock_quote · 日期 2026-07-16 · 影响 weakens
JBL近20日跌17.23%、当日/最新跌2.34%,说明硬件链承压且回购尚未形成强承接。
检索:JBL.US stock_quote full recent trend AI hardware selloff - 做多前查反向 · 来源 web · 日期 2026-07-16 · 影响 weakens
同篇早报开头显示QQQ、半导体和存储链明显回撤,JBL所处AI硬件链短线风险偏高。
检索:TMT Breakout JBL buyback AI hardware unwind negative counter evidence 原文 ↗
历史先例(按相似度)
- AAPL 2024-05-02 苹果宣布1100亿美元回购并披露财报,规模约3%市值,非纯回购事件。 原文 ↗
事件后 +1日 +6.0% · +3日 +5.4% · +5日 +6.7% - META 2024-02-01 Meta宣布500亿美元回购扩大授权并披露强财报。 原文 ↗
事件后 +1日 +20.3% · +3日 +15.2% · +5日 +19.1% - UBER 2024-02-14 Uber宣布首次70亿美元回购授权,约4%市值。 原文 ↗
事件后 +1日 +2.8% · +3日 -3.2% · +5日 -1.4% - CRM 2022-08-24 Salesforce宣布首个100亿美元回购授权并披露财报。 原文 ↗
事件后 +1日 -3.4% · +3日 -11.0% · +5日 -13.3% - PYPL 2022-08-02 PayPal宣布150亿美元回购授权并披露财报/战略更新。 原文 ↗
事件后 +1日 +9.2% · +3日 +6.3% · +5日 +5.4% - INTC 2020-08-19 Intel宣布100亿美元加速股票回购计划。 原文 ↗
事件后 +1日 +1.7% · +3日 +1.7% · +5日 +2.5%
工具调用 · 历史记录,结果未知(3 种)
- stock_quote · 结果未知
- event_study · 结果未知
- validate_order · 结果未知
原文全文
展开原文 · 24,992 字
*TMTB will be out on holiday beginning tomorrow through next week*
Good morning. **QQQs -1%** as the Momentum/AI semis unwind continues with **Semis -3%** and **Software +70bps **as China AI in conversations again today (Kimi K3 rumored to surpass Opus 4.8). Hyperscalers outperforming early as well with **AMZN/GOOGL/MSFT** all in the green. **Korea -6%** overnight with memory names down big: **Kioxia-15%, Hynix-10%, Samsung-7.6%, Nanya-8%** and US names following early: **SNDK -7%; MU -5%; STX -6%**.
**TSM rev **#s, capex, & AI commentary were solid although GMs missed bogeys and stock is down 4-5% early (more sell the news reactions following other AI semi prints like Samsung, ASML, and DOCN).
Lots to get to, so let’s get to it…
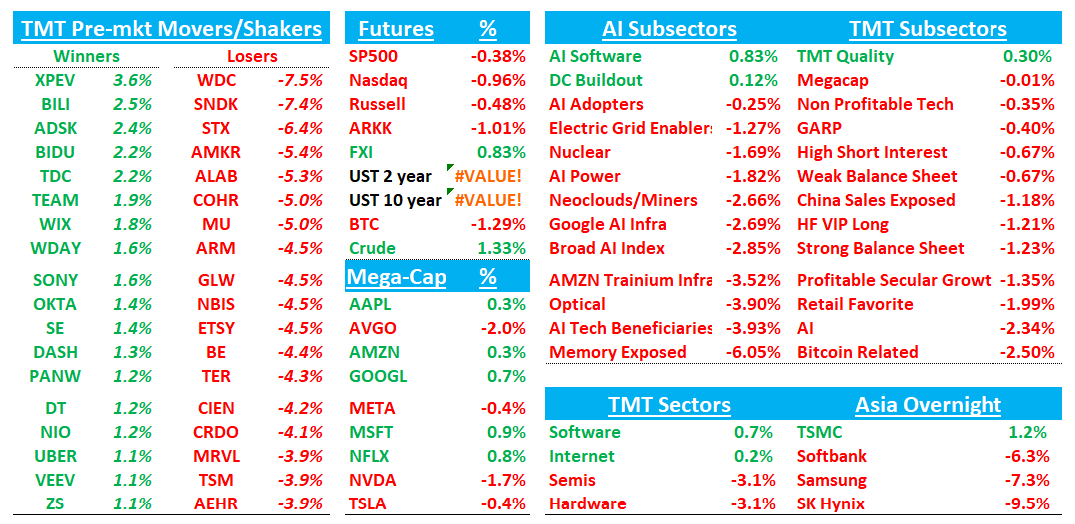
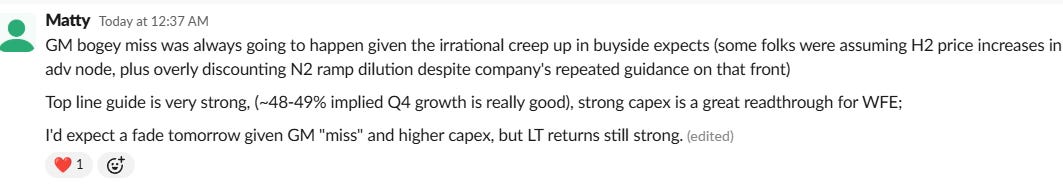
### **TSM: Capex and FY26 guide both above bogeys, but GMs misses bogeys for both Q2 and Q3**
Bulls will like the better than expected FY26 guide of “slightly above 40%” vs bogeys in mid to high 30s and implied 48-49% for Q4 growth given the Q3 guide and positive AI commentary from mgmt; while bears pointing to weaker GMs and the below comment on weaker consumer markets
*“we observe consumer and price sensitive end market segment are being challenged due to the impact of rising component prices and macroeconomic uncertainties”*
#### **The #s:**
2Q net revenue NT$1.27tln vs street NT$1.27tln.
2Q gross margin 67.7% vs street at 67.1% and bogeys in high 60s
Guides 3Q sales $44.6~45.8bln (midpoint $45.2bln) vs street $43.11bln
Sees 3Q gross margin 65~67% (midpoint 66%) vs street 65.9% and bogeys of 67-68% at midpt.
Guides FY26 sales to "grow slightly above 40% in USD terms" vs previous "above 30% in USD terms.
Raises FY26 CAPEX to $60~64bln (midpoint $62bln) vs previous high-end of $52~56bln range and bogeys of ~$60B at midpt
### **GLW: JPM Places Shares on Negative Catalyst Watch as Valuation Leaves Little Room for Error**
JPM places GLW on Negative Catalyst Watch ahead of earnings, arguing the stock’s resilience has pushed valuation above 30x CY28 earnings and implies roughly 40x for the optical business. While Optical Enterprise should remain strong, JPM expects below-seasonal Optical Carrier results after a solid first quarter, with other segments broadly in line. Tougher TV display data into 2H26 adds further risk, leaving the setup vulnerable even if core optical fundamentals remain healthy.
### **LITE: Citi Opens 90-Day Upside Catalyst Watch as InP Shortage Supports Pricing and CPO Visibility**
Citi opens a 90-day upside Catalyst Watch on LITE ahead of earnings and ECOC, arguing InP laser supply will remain below demand through at least 2028 despite aggressive capacity additions. Its model points to EML supply gaps of roughly 30%/20%/11% in 2026–28, supporting another 15% price increase in FY2Q27 and driving 6%/5% upward revisions to FY27/FY28 EPS. Citi also sees NVIDIA’s CPO roadmap as intact and believes even an NPO shift would still require Lumentum’s laser technology, leaving LITE well positioned across both architectures.
### **NVDA: Hearing Clev positive saying ASP increases driving further upside through CY27**
### **NVDA: NVIDIA Groq 3 LPX cabinets are expected to ship in the second half of 2026, introducing Q-Glass quartz fiber fabrics to drive high-end CCL, copper foil, and PCB stockpiling. Each cabinet is equipped with 256 LPUs and about 384 CCLs, with a material output value of approximately 3.84 million NTD - [CTEE](https://www.ctee.com.tw/news/20260716700081-430502)**
### **NVDA: Japan is planning to buy 27,500 next-generation Rubin chips from [Nvidia Corp.](https://www.bloomberg.com/quote/NVDA:US) to build a homegrown foundational AI model for robots. - [Bloomberg](https://www.bloomberg.com/news/articles/2026-07-16/japan-to-buy-nvidia-rubin-chips-to-build-sovereign-ai-for-robots)**
### **AMD: Hearing Clev positive saying CPU Demand remains robust, +ve GPU feedback, and AMD supply upside**
### **ANET: Evercore Adds to Tactical Outperform List Ahead of Q2 on AI and Enterprise Upside**
Evercore adds ANET to its Tactical Outperform list with a $200 price target, expecting a 2Q beat and above-Street 3Q guide as AI demand strengthens and enterprise momentum remains durable. The firm sees June-quarter revenue roughly $400M–$500M above prior expectations and believes ANET could raise its FY26 revenue target from $11.5B, with upside from increasingly complex AI networks, front-end and campus deployments, and growing traction with Anthropic and Google. Evercore also highlights scale-across networking as an underappreciated opportunity, with ANET positioned as a preferred partner for neoclouds including xAI, OpenAI and Anthropic.
### **ANET: Wells Fargo Raises PT to $200 and Recommends Buying Ahead of 2Q on Demand and Supply Upside**
Wells Fargo raises its price target to $200 from $185 and recommends buying ANET ahead of earnings, expecting continued demand strength and improved supply visibility to support an increase in 2026 revenue guidance toward roughly 30% growth from 28% currently. The firm sees potential for growth to exceed 35% given contractual commitments, pricing increases of 10%–15%, traditional server CPU demand and scale-up revenue ramping in 2027. Customer diversification also remains a catalyst, with ANET expected to add one to two new 10%+ customers in 2026, while Wells Fargo views recent supply concerns as overdone.
### **STX: Evercore Adds to Tactical Outperform List as Pricing and Mozaic Mix Drive FY27 Upside**
Evercore adds STX to its Tactical Outperform list with a $1,000 price target, arguing the June quarter should be largely in line but pricing remains the key source of upside into FY27. Nearline pricing is expected to rise around 7% q/q, with constrained supply, cloud/AI storage demand and improving Mozaic/HAMR mix supporting stronger revenue, margins and earnings visibility. Evercore sees FY27 revenue growth of roughly 40% and believes current Street estimates underappreciate the potential for favorable long-term agreements and accelerating Mozaic adoption to push earnings materially higher.
### **FLEX: Freedom Capital Upgrades to Buy on AI Infrastructure Spin-Off Upside**
Freedom Capital upgraded FLEX to Buy from Hold and raised its price target to $150 from $144, citing greater confidence in valuation and the planned separation of the company’s AI infrastructure business into a standalone public entity. The firm is particularly bullish on the spin-off, which could improve strategic focus, provide clearer valuation transparency and unlock value for shareholders.
### **TTWO: Hearing Yipit says sales to date imply ~40M units in first 3 days, with current SKU mix 92% ultimate vs 8% standard although lots of assumptions in these estimates so take fwiw**
### **Cloud: Hearing Yip saying rev accelerated in June across all CSPs**
### **NET/AKAM: Morgan Stanley Survey Shows Edge AI Inference Broadening Beyond Hyperscalers**
Morgan Stanley’s inaugural survey of roughly 40 resellers and partners suggests enterprise edge AI is moving from experimentation toward targeted production, with adoption expected to accelerate meaningfully through 2027 as inference shifts closer to users, devices and data. NET emerges as the clear early leader, prompting Morgan Stanley to raise its price target to $322, supported by rapid growth in developer services and AI agent traffic and a path to more than $5B of revenue before 2028. AKAM is viewed as a credible second platform, with 50% of partners reporting inference-related results above plan, while Vercel benefits from AI-native application development.
*Clev was also positive NET*
### **JBL: Announced $1.5B buyback, 4.5% of market cap.**
### **VRT: Baird Initiates Outperform with $370 PT on NVIDIA Alignment and 800VDC Upside**
Baird initiated VRT at Outperform with a $370 price target, viewing the company as a core data-center growth holding and one of the cleanest pure plays on AI infrastructure buildouts. Vertiv’s foundational relationship with NVIDIA should provide strong visibility into next-generation power and cooling architectures, particularly the transition toward 800VDC. Baird also highlights the company’s roughly $24B capital-allocation capacity as a major strategic advantage and recommends using near-term share weakness as a buying opportunity.
# **AI NEWS**
### **China AI: Chinese AI start-up Moonshot to launch model challenging Anthropic’s lead. imi K3 expected to exceed performance of Claude Opus 4.8 in sign of narrowing gap between US and China on frontier AI- FT**
[FinancialTimes](https://www.ft.com/content/c6ecd8ce-c441-4d7c-aea6-fae3e28fb6ff?syn-25a6b1a6=1): *The Beijing-based group is scheduled to release Kimi K3, China’s largest AI model to date with 2tn-3tn parameters, in the coming days, according to two people familiar with the matter.*
### **China AI:** **Palantir’s CTO Sees Chinese AI Models Posing Economic Risk to US**
[Bloomberg](https://www.bloomberg.com/news/articles/2026-07-15/palantir-s-cto-sees-chinese-ai-models-posing-economic-risk-to-us)**:**
**
“These Chinese open source models are really the result of distillation attacks,” Sankar said Wednesday in a Bloomberg Television interview on the sidelines of a defense innovation conference in Pennsylvania. “Most of this is just stolen American IP from frontier labs.”
Sankar’s comments highlighted growing concerns among top American AI companies that their Chinese rivals are improperly using a technique known as distillation, where developers train systems using results from another AI model to create similar capabilities in a new one at a far lower cost. He called on leading US labs to do more to protect their intellectual property, saying it’s “in their own economic interests.”
### **Anthropic: Anthropic in Talks to Add Billions to Bank Credit Line Ahead of IPO**
[TheInformation](https://www.theinformation.com/articles/anthropic-talks-add-billions-bank-credit-line-ahead-ipo?utm_campaign=article_email&utm_content=article-17465&utm_medium=email&utm_source=sg&rc=h3on51):
**
**Anthropic is in** talks with banks to arrange credit lines worth a few billions of dollars in a move that would increase its access to cash ahead of a planned initial public offering this year, according to people familiar with the matter.
The new loans would build on the $2.5 billion, five-year revolving credit facility [Anthropic](https://www.theinformation.com/org-charts/anthropic) received last year from banks. Companies often expand that type of capacity ahead of an IPO, with many of the banks also working as underwriters on the offering. SpaceX, for instance, increased its credit facility with several of its IPO bankers about a month before its June public offering.
### **Anthropic: Anthropic moves closer to mega-IPO as bankers line up investor meetings - CNBC**
### **AI Data Centers: CLSA Says Powered Land Is the Scarce Asset as Grid and Permitting Constraints Intensify**
CLSA’s Datacloud meetings reinforced a widening bifurcation between developers, with value accruing to operators that already control deliverable power, credible execution and community support. Capital availability has improved, but transmission bottlenecks and worsening “social license” constraints are throttling supply, pushing hyperscaler and sovereign demand toward any viable powered site globally; behind-the-meter generation now represents roughly half of the U.S. pipeline. For neoclouds, scale increasingly depends on hyperscaler offtake and software differentiation, while OEM customers are prioritizing delivery certainty and supplier diversification as AI deployments move from MW to GW scale.
### **AI Datacenters:** **Palm Beach Strikes Down Data Center Plan After Local Backlash**
[Bloomberg](https://www.bloomberg.com/news/articles/2026-07-16/palm-beach-strikes-down-data-center-plan-after-local-backlash):
**
Palm Beach County commissioners rejected [a proposal](https://www.bloomberg.com/news/articles/2026-07-15/ai-backlash-builds-for-project-tango-proposal-near-trump-s-mar-a-lago) late Wednesday to build a digital infrastructure hub to house AI data centers and warehouses, voting in line with the ardent opposition from local residents.
The facility, known as Project Tango, would have filled dozens of acres of land about 20 miles from President Donald Trump’s Mar-a-Lago club. It faced a backlash from residents who feared it would cause power and water bills to spike, an echo of tension playing out across the country as tech giants sprint to build data centers.
### **Korea AI: South Korea to Halt New Listings of Single Stock Leveraged ETF - [Bloomberg](https://www.bloomberg.com/news/articles/2026-07-16/south-korea-to-halt-new-listings-of-single-stock-leveraged-etfs)**
# **INTERNET**
### **ETSY: BTIG Downgrades to Neutral After 55% YTD Rally Leaves Valuation Full**
BTIG downgraded ETSY to Neutral from Buy after shares moved 10% above its prior $78 price target and nearly doubled from the February low. While third-party data suggests solid current-quarter sales and the $1.2B Depop sale validated hidden asset value, ETSY now trades near 11x 2027 EBITDA—roughly in line with faster-growing peers despite only a mid-single-digit GMV growth outlook. BTIG sees limited further multiple expansion, with recent gains also helped by short covering and rotation out of AI stocks rather than fundamentals alone.
### **UBER/Delivery: UBER announced a deal to buy Delivery Hero for EU41.50/share (the deal has an equity value of $14.8B, or $13.7B adjusted for Uber’s existing stake in the company), and Uber anticipates the transaction being accretive to EPS upon close (with 7-9% EPS accretion by year three)**
### **RDDT: Needham Says Shopping Products Shift Monetization Toward Amazon-Like Purchase Intent**
Needham argues Reddit’s 2026 product roadmap is moving the platform closer to transactions and away from a traditional social-media model, making AMZN—not META—the more relevant monetization comparison. AI Shopping Deep Dives, Reddit Shopping, Shopify integrations, Shopping Listing Ads and Redditor Highlights keep users inside the platform from discovery through purchase while giving advertisers better conversion measurement. Needham believes Reddit’s authentic human conversations, real-time sentiment and community trust create a defensible purchase-intent asset that LLMs can summarize but cannot replicate, supporting stronger
# **SOFTWARE**
### **PANW: Capital One Upgrades to Overweight as AI Buildouts Expand Cybersecurity Demand**
Capital One upgraded PANW to Overweight from Equal Weight and raised its price target to $421 from $307, arguing AI data-center expansion will create larger attack surfaces and drive incremental budget toward cybersecurity. The firm sees Palo Alto benefiting both from protecting the infrastructure supporting AI deployments and from securing the AI applications and workloads running on top of it. Capital One views the company’s growing AI momentum and broad platform position as supporting stronger demand and a higher valuation.
### **OKTA: Capital One Upgrades to Overweight as AI Agent Governance Expands the Opportunity**
Capital One upgraded OKTA to Overweight from Equal Weight and raised its price target to $171 from $126, arguing the company is well positioned as a neutral identity layer across the broader cybersecurity ecosystem. The firm sees a healthy AI agent pipeline and expects rising demand for agent discovery, authentication and governance as enterprises deploy more autonomous workflows. Capital One also sees upside to estimates this year and into FY28 as these new identity use cases expand Okta’s addressable market.
### **Cybersecurity/DDOG: BNP Survey Shows Strong 2Q Spend but Softer Forward Intentions**
BNP’s quarterly reseller survey found cybersecurity remained the top IT spending priority over the past three months, while Datadog sales tracked a few points above plan on product functionality, competitive wins and strength in infrastructure monitoring, APM and AI-related use cases. However, overall IT spending intentions weakened sharply from April, and resellers expect cybersecurity momentum to trail other categories over the next three months, suggesting demand may have been concentrated in 2Q. DDOG’s forward spending score also fell to 2.0 from 5.4, creating a more mixed setup despite solid recent execution.
### **CRWD: Citi Raises PT to $250 as AI Expands Cybersecurity TAM and Reinforces Market Leadership**
Citi reiterates Buy and raises its split-adjusted price target to $250, arguing pre-quiet-period discussions reinforced confidence in high-20% near-term ARR growth and durable mid-20% growth thereafter. Early checks point to stronger eight-figure deal activity, while AI-driven attack surfaces, regulatory pressure and procurement disruption are increasing demand for CRWD’s broad platform, services footprint and Flex offerings. Although valuation is near peak levels and estimate revisions remain limited, Citi believes CrowdStrike is becoming a “cyber OEM” for emerging AI architectures, supporting higher multiples and outsized incremental budget capture.
### **NOW: Hearing Cleveland positive saying Q1 appeared to finish ahead with some pull forward benefit, although outlooks more mixed given model transition, competition, internal org changes, etc.**
### **DDOG: UBS Stays Buy as Customer Checks Support 30%+ Growth Despite a tougher Setup**
UBS maintains Buy after conversations with seven customers and three partners reinforced that observability remains a priority spend area as enterprises accelerate AI deployments. Checks improved versus late 2025/early 2026, with DDOG gaining share through vendor consolidation and expanding into hybrid environments, although pricing pushback remains the main friction point. UBS still sees 30%+ growth in 2026 and expects another acceleration in 2Q, but acknowledges the setup is tougher after the stock’s rally and valuation near 20x revenue and 75x FCF.
### **MSFT**: **Microsoft Gives Sellers Tips to Knock Down Anthropic, OpenAI**
**[Bloomberg](https://www.bloomberg.com/news/articles/2026-07-15/microsoft-gives-salespeople-tips-to-knock-down-anthropic-openai?accessToken=eyJhbGciOiJIUzI1NiIsInR5cCI6IkpXVCJ9.eyJzb3VyY2UiOiJTdWJzY3JpYmVyR2lmdGVkQXJ0aWNsZSIsImlhdCI6MTc4NDE0Mzk5NywiZXhwIjoxNzg0NzQ4Nzk3LCJhcnRpY2xlSWQiOiJUSTZBRVhLSkg2VjYwMCIsImJjb25uZWN0SWQiOiJEQ0FGMjNFM0YyMkE0Qzk5OTM0RUMyRDEwNkM0ODc0NyJ9.xkGGKI3U9CBk_UcIipQZOAOwxHuYwKKLBjaEedoT928&leadSource=article-gifting):**
**
[Microsoft Corp.](https://www.bloomberg.com/quote/MSFT:US) is coaching its sales team on how to vigorously compete against Anthropic PBC and OpenAI, playing up shortcomings in products from the artificial intelligence firms.
The software giant offers lower costs, better security controls and a more complete suite of products, Microsoft executives said during an internal meeting this week laying out the company’s sales strategy for the fiscal year that began this month.
### **WIX: Wells Fargo Keeps Equal Weight and Cuts PT to $46 as Web Traffic Weakens**
Wells Fargo maintains Equal Weight and lowers its price target to $46 from $47 after softer June web traffic led the firm to reduce 2H bookings by 2%, now modeling roughly 10% y/y growth versus Street at 12%. Base44 traffic also weakened late in the quarter, increasing the importance of ARR execution and returns on higher marketing investment as the core Wix business slows. Wells Fargo trims FY26/FY27 bookings by 1%/3% and non-GAAP operating income by 5%/3%, while expecting 3Q revenue guidance in the low double digits.
### **TEAM: BofA Keeps Neutral and Cuts PT to $105 as Data Center Transition Pushes Growth Trough to FY27**
BofA lowers FY27/FY28 revenue estimates by 4.3%/4.1% and cuts its price objective to $105 from $110, arguing accelerated Data Center migrations, shorter contract durations and renewal pull-forwards will create a choppy 12–24 month growth profile. The firm now models FY27 revenue of $7.17B, +11% y/y versus Street at $7.37B, +14%, and reduces Data Center revenue estimates by 16% in both FY27 and FY28. Cloud remains the key upside lever through higher tiers, seat expansion, cross-sell and pricing, but BofA stays Neutral pending greater clarity on the medium-term growth algorithm.
### **ZM: Wolfe Reiterates Outperform as AI Monetization and Voice API Make the Reacceleration Path More Tangible**
Wolfe reiterates Outperform after management meetings increased confidence that Zoom is evolving from a video collaboration platform into a broader “system of action” where AI completes work. The firm sees three growth levers: lower core churn, continued Phone and Contact Center share gains, and new horizontal AI products, with enterprise pricing discipline and ZCX execution the key swing factors. Wolfe highlights a net-new Voice API opportunity outside the seat-based model and a customer that increased spending more than 50% over three years, implying roughly 115% NRR, as early evidence that consumption-based AI monetization is working.
### **MNDY: Wells Fargo More Encouraged on AI Strategy and Emerging Consumption Monetization**
Wells Fargo came away more positive after management demonstrated MNDY Agents, which can automate workflows, create dashboards and interact with enterprise data across multiple frontier models, reinforcing monday.com’s ambition to become an orchestration layer connecting employees, agents and company data. AI demand is beginning to build in customer discussions, prompting greater GTM investment and an expanded FDE organization. Monetization remains early but is shifting toward a hybrid model, with new customers purchasing minimum AI-credit bundles.
# **LEFTOVERS**
### **SPCX: JPM Says Flight 13 Is a High-Profile Test of Starship V3 Reliability and Reusability**
JPM highlights SpaceX’s 13th Starship test flight—and second using the V3 configuration—as a potentially stock-moving milestone given Starship’s importance to future Starlink, AI-satellite and lunar missions. Flight 13 will test upgraded Super Heavy re-light reliability, an in-flight upper-stage engine restart and 20 Starlink V3 satellites, while providing new data on heat-shield performance ahead of eventual upper-stage recovery. JPM views the launch as one step toward dozens of annual flights next year and hundreds by 2028, with engine reliability, refurbishment time and in-space refueling remaining the key business-model hurdles.
### **ASTS: -12%** **seeking $1b in a convertible bond offering**
### **ASTS/SPCX/RKLB: Piper Prefers ASTS as the Clearest Space Monetization Story**
Piper initiates ASTS at Overweight with a $100 price target, while launching SPCX and RKLB at Neutral with $156 and $83 targets, respectively. ASTS is the preferred name given its operator-backed direct-to-device model, partnerships with AT&T, Vodafone, Rakuten and Verizon, and access to more than 3B potential subscribers, providing the clearest path to incremental revenue and EBITDA. Piper remains constructive on SPCX’s vertically integrated platform and long-term orbital AI opportunity, but sees substantial execution, capex and transaction risk, while RKLB’s strong launch record and Neutron upside are offset by a premium valuation relative to its smaller scale.
### **SNPS/CDNS: Benchmark Initiates Both at Buy as AI Drives a New EDA Productivity Cycle**
Benchmark initiates SNPS at Buy with a $570 price target and CDNS at Buy with a $450 target, arguing rising chip, packaging and system complexity will push EDA, IP and simulation vendors to capture a larger share of semiconductor R&D spending. AI-driven design tools should create a step-function improvement in engineer productivity and support faster industry growth, strong pricing power and durable margins. CDNS is viewed as the higher-quality share leader, while SNPS offers greater valuation catch-up potential if management rebuilds credibility and executes on Ansys synergies, new hyperscaler IP, Intel 14A exposure and China stabilization.
### **NVDA: NVIDIA Introduces New Jetson Thor Computers to Advance Mainstream Robotics and Edge AI**
[PR: ](https://blogs.nvidia.com/blog/jetson-thor-robotics-edge-ai-agent/)*New NVIDIA Blackwell-powered T3000 and T2000 modules, paired with new NVIDIA Jetson software memory optimization and agent skills, help partners and customers move advanced robotics, visual AI and edge workloads onto compact, power-efficient systems.*
Good morning. **QQQs -1%** as the Momentum/AI semis unwind continues with **Semis -3%** and **Software +70bps **as China AI in conversations again today (Kimi K3 rumored to surpass Opus 4.8). Hyperscalers outperforming early as well with **AMZN/GOOGL/MSFT** all in the green. **Korea -6%** overnight with memory names down big: **Kioxia-15%, Hynix-10%, Samsung-7.6%, Nanya-8%** and US names following early: **SNDK -7%; MU -5%; STX -6%**.
**TSM rev **#s, capex, & AI commentary were solid although GMs missed bogeys and stock is down 4-5% early (more sell the news reactions following other AI semi prints like Samsung, ASML, and DOCN).
Lots to get to, so let’s get to it…

### **TSM: Capex and FY26 guide both above bogeys, but GMs misses bogeys for both Q2 and Q3**
Bulls will like the better than expected FY26 guide of “slightly above 40%” vs bogeys in mid to high 30s and implied 48-49% for Q4 growth given the Q3 guide and positive AI commentary from mgmt; while bears pointing to weaker GMs and the below comment on weaker consumer markets
*“we observe consumer and price sensitive end market segment are being challenged due to the impact of rising component prices and macroeconomic uncertainties”*

#### **The #s:**
2Q net revenue NT$1.27tln vs street NT$1.27tln.
2Q gross margin 67.7% vs street at 67.1% and bogeys in high 60s
Guides 3Q sales $44.6~45.8bln (midpoint $45.2bln) vs street $43.11bln
Sees 3Q gross margin 65~67% (midpoint 66%) vs street 65.9% and bogeys of 67-68% at midpt.
Guides FY26 sales to "grow slightly above 40% in USD terms" vs previous "above 30% in USD terms.
Raises FY26 CAPEX to $60~64bln (midpoint $62bln) vs previous high-end of $52~56bln range and bogeys of ~$60B at midpt
### **GLW: JPM Places Shares on Negative Catalyst Watch as Valuation Leaves Little Room for Error**
JPM places GLW on Negative Catalyst Watch ahead of earnings, arguing the stock’s resilience has pushed valuation above 30x CY28 earnings and implies roughly 40x for the optical business. While Optical Enterprise should remain strong, JPM expects below-seasonal Optical Carrier results after a solid first quarter, with other segments broadly in line. Tougher TV display data into 2H26 adds further risk, leaving the setup vulnerable even if core optical fundamentals remain healthy.
### **LITE: Citi Opens 90-Day Upside Catalyst Watch as InP Shortage Supports Pricing and CPO Visibility**
Citi opens a 90-day upside Catalyst Watch on LITE ahead of earnings and ECOC, arguing InP laser supply will remain below demand through at least 2028 despite aggressive capacity additions. Its model points to EML supply gaps of roughly 30%/20%/11% in 2026–28, supporting another 15% price increase in FY2Q27 and driving 6%/5% upward revisions to FY27/FY28 EPS. Citi also sees NVIDIA’s CPO roadmap as intact and believes even an NPO shift would still require Lumentum’s laser technology, leaving LITE well positioned across both architectures.
### **NVDA: Hearing Clev positive saying ASP increases driving further upside through CY27**
### **NVDA: NVIDIA Groq 3 LPX cabinets are expected to ship in the second half of 2026, introducing Q-Glass quartz fiber fabrics to drive high-end CCL, copper foil, and PCB stockpiling. Each cabinet is equipped with 256 LPUs and about 384 CCLs, with a material output value of approximately 3.84 million NTD - [CTEE](https://www.ctee.com.tw/news/20260716700081-430502)**
### **NVDA: Japan is planning to buy 27,500 next-generation Rubin chips from [Nvidia Corp.](https://www.bloomberg.com/quote/NVDA:US) to build a homegrown foundational AI model for robots. - [Bloomberg](https://www.bloomberg.com/news/articles/2026-07-16/japan-to-buy-nvidia-rubin-chips-to-build-sovereign-ai-for-robots)**
### **AMD: Hearing Clev positive saying CPU Demand remains robust, +ve GPU feedback, and AMD supply upside**
### **ANET: Evercore Adds to Tactical Outperform List Ahead of Q2 on AI and Enterprise Upside**
Evercore adds ANET to its Tactical Outperform list with a $200 price target, expecting a 2Q beat and above-Street 3Q guide as AI demand strengthens and enterprise momentum remains durable. The firm sees June-quarter revenue roughly $400M–$500M above prior expectations and believes ANET could raise its FY26 revenue target from $11.5B, with upside from increasingly complex AI networks, front-end and campus deployments, and growing traction with Anthropic and Google. Evercore also highlights scale-across networking as an underappreciated opportunity, with ANET positioned as a preferred partner for neoclouds including xAI, OpenAI and Anthropic.
### **ANET: Wells Fargo Raises PT to $200 and Recommends Buying Ahead of 2Q on Demand and Supply Upside**
Wells Fargo raises its price target to $200 from $185 and recommends buying ANET ahead of earnings, expecting continued demand strength and improved supply visibility to support an increase in 2026 revenue guidance toward roughly 30% growth from 28% currently. The firm sees potential for growth to exceed 35% given contractual commitments, pricing increases of 10%–15%, traditional server CPU demand and scale-up revenue ramping in 2027. Customer diversification also remains a catalyst, with ANET expected to add one to two new 10%+ customers in 2026, while Wells Fargo views recent supply concerns as overdone.
### **STX: Evercore Adds to Tactical Outperform List as Pricing and Mozaic Mix Drive FY27 Upside**
Evercore adds STX to its Tactical Outperform list with a $1,000 price target, arguing the June quarter should be largely in line but pricing remains the key source of upside into FY27. Nearline pricing is expected to rise around 7% q/q, with constrained supply, cloud/AI storage demand and improving Mozaic/HAMR mix supporting stronger revenue, margins and earnings visibility. Evercore sees FY27 revenue growth of roughly 40% and believes current Street estimates underappreciate the potential for favorable long-term agreements and accelerating Mozaic adoption to push earnings materially higher.
### **FLEX: Freedom Capital Upgrades to Buy on AI Infrastructure Spin-Off Upside**
Freedom Capital upgraded FLEX to Buy from Hold and raised its price target to $150 from $144, citing greater confidence in valuation and the planned separation of the company’s AI infrastructure business into a standalone public entity. The firm is particularly bullish on the spin-off, which could improve strategic focus, provide clearer valuation transparency and unlock value for shareholders.
### **TTWO: Hearing Yipit says sales to date imply ~40M units in first 3 days, with current SKU mix 92% ultimate vs 8% standard although lots of assumptions in these estimates so take fwiw**
### **Cloud: Hearing Yip saying rev accelerated in June across all CSPs**
### **NET/AKAM: Morgan Stanley Survey Shows Edge AI Inference Broadening Beyond Hyperscalers**
Morgan Stanley’s inaugural survey of roughly 40 resellers and partners suggests enterprise edge AI is moving from experimentation toward targeted production, with adoption expected to accelerate meaningfully through 2027 as inference shifts closer to users, devices and data. NET emerges as the clear early leader, prompting Morgan Stanley to raise its price target to $322, supported by rapid growth in developer services and AI agent traffic and a path to more than $5B of revenue before 2028. AKAM is viewed as a credible second platform, with 50% of partners reporting inference-related results above plan, while Vercel benefits from AI-native application development.
*Clev was also positive NET*
### **JBL: Announced $1.5B buyback, 4.5% of market cap.**
### **VRT: Baird Initiates Outperform with $370 PT on NVIDIA Alignment and 800VDC Upside**
Baird initiated VRT at Outperform with a $370 price target, viewing the company as a core data-center growth holding and one of the cleanest pure plays on AI infrastructure buildouts. Vertiv’s foundational relationship with NVIDIA should provide strong visibility into next-generation power and cooling architectures, particularly the transition toward 800VDC. Baird also highlights the company’s roughly $24B capital-allocation capacity as a major strategic advantage and recommends using near-term share weakness as a buying opportunity.
# **AI NEWS**
### **China AI: Chinese AI start-up Moonshot to launch model challenging Anthropic’s lead. imi K3 expected to exceed performance of Claude Opus 4.8 in sign of narrowing gap between US and China on frontier AI- FT**
[FinancialTimes](https://www.ft.com/content/c6ecd8ce-c441-4d7c-aea6-fae3e28fb6ff?syn-25a6b1a6=1): *The Beijing-based group is scheduled to release Kimi K3, China’s largest AI model to date with 2tn-3tn parameters, in the coming days, according to two people familiar with the matter.*
### **China AI:** **Palantir’s CTO Sees Chinese AI Models Posing Economic Risk to US**
[Bloomberg](https://www.bloomberg.com/news/articles/2026-07-15/palantir-s-cto-sees-chinese-ai-models-posing-economic-risk-to-us)**:**
**
“These Chinese open source models are really the result of distillation attacks,” Sankar said Wednesday in a Bloomberg Television interview on the sidelines of a defense innovation conference in Pennsylvania. “Most of this is just stolen American IP from frontier labs.”
Sankar’s comments highlighted growing concerns among top American AI companies that their Chinese rivals are improperly using a technique known as distillation, where developers train systems using results from another AI model to create similar capabilities in a new one at a far lower cost. He called on leading US labs to do more to protect their intellectual property, saying it’s “in their own economic interests.”
### **Anthropic: Anthropic in Talks to Add Billions to Bank Credit Line Ahead of IPO**
[TheInformation](https://www.theinformation.com/articles/anthropic-talks-add-billions-bank-credit-line-ahead-ipo?utm_campaign=article_email&utm_content=article-17465&utm_medium=email&utm_source=sg&rc=h3on51):
**
**Anthropic is in** talks with banks to arrange credit lines worth a few billions of dollars in a move that would increase its access to cash ahead of a planned initial public offering this year, according to people familiar with the matter.
The new loans would build on the $2.5 billion, five-year revolving credit facility [Anthropic](https://www.theinformation.com/org-charts/anthropic) received last year from banks. Companies often expand that type of capacity ahead of an IPO, with many of the banks also working as underwriters on the offering. SpaceX, for instance, increased its credit facility with several of its IPO bankers about a month before its June public offering.
### **Anthropic: Anthropic moves closer to mega-IPO as bankers line up investor meetings - CNBC**
### **AI Data Centers: CLSA Says Powered Land Is the Scarce Asset as Grid and Permitting Constraints Intensify**
CLSA’s Datacloud meetings reinforced a widening bifurcation between developers, with value accruing to operators that already control deliverable power, credible execution and community support. Capital availability has improved, but transmission bottlenecks and worsening “social license” constraints are throttling supply, pushing hyperscaler and sovereign demand toward any viable powered site globally; behind-the-meter generation now represents roughly half of the U.S. pipeline. For neoclouds, scale increasingly depends on hyperscaler offtake and software differentiation, while OEM customers are prioritizing delivery certainty and supplier diversification as AI deployments move from MW to GW scale.
### **AI Datacenters:** **Palm Beach Strikes Down Data Center Plan After Local Backlash**
[Bloomberg](https://www.bloomberg.com/news/articles/2026-07-16/palm-beach-strikes-down-data-center-plan-after-local-backlash):
**
Palm Beach County commissioners rejected [a proposal](https://www.bloomberg.com/news/articles/2026-07-15/ai-backlash-builds-for-project-tango-proposal-near-trump-s-mar-a-lago) late Wednesday to build a digital infrastructure hub to house AI data centers and warehouses, voting in line with the ardent opposition from local residents.
The facility, known as Project Tango, would have filled dozens of acres of land about 20 miles from President Donald Trump’s Mar-a-Lago club. It faced a backlash from residents who feared it would cause power and water bills to spike, an echo of tension playing out across the country as tech giants sprint to build data centers.
### **Korea AI: South Korea to Halt New Listings of Single Stock Leveraged ETF - [Bloomberg](https://www.bloomberg.com/news/articles/2026-07-16/south-korea-to-halt-new-listings-of-single-stock-leveraged-etfs)**
# **INTERNET**
### **ETSY: BTIG Downgrades to Neutral After 55% YTD Rally Leaves Valuation Full**
BTIG downgraded ETSY to Neutral from Buy after shares moved 10% above its prior $78 price target and nearly doubled from the February low. While third-party data suggests solid current-quarter sales and the $1.2B Depop sale validated hidden asset value, ETSY now trades near 11x 2027 EBITDA—roughly in line with faster-growing peers despite only a mid-single-digit GMV growth outlook. BTIG sees limited further multiple expansion, with recent gains also helped by short covering and rotation out of AI stocks rather than fundamentals alone.
### **UBER/Delivery: UBER announced a deal to buy Delivery Hero for EU41.50/share (the deal has an equity value of $14.8B, or $13.7B adjusted for Uber’s existing stake in the company), and Uber anticipates the transaction being accretive to EPS upon close (with 7-9% EPS accretion by year three)**
### **RDDT: Needham Says Shopping Products Shift Monetization Toward Amazon-Like Purchase Intent**
Needham argues Reddit’s 2026 product roadmap is moving the platform closer to transactions and away from a traditional social-media model, making AMZN—not META—the more relevant monetization comparison. AI Shopping Deep Dives, Reddit Shopping, Shopify integrations, Shopping Listing Ads and Redditor Highlights keep users inside the platform from discovery through purchase while giving advertisers better conversion measurement. Needham believes Reddit’s authentic human conversations, real-time sentiment and community trust create a defensible purchase-intent asset that LLMs can summarize but cannot replicate, supporting stronger
# **SOFTWARE**
### **PANW: Capital One Upgrades to Overweight as AI Buildouts Expand Cybersecurity Demand**
Capital One upgraded PANW to Overweight from Equal Weight and raised its price target to $421 from $307, arguing AI data-center expansion will create larger attack surfaces and drive incremental budget toward cybersecurity. The firm sees Palo Alto benefiting both from protecting the infrastructure supporting AI deployments and from securing the AI applications and workloads running on top of it. Capital One views the company’s growing AI momentum and broad platform position as supporting stronger demand and a higher valuation.
### **OKTA: Capital One Upgrades to Overweight as AI Agent Governance Expands the Opportunity**
Capital One upgraded OKTA to Overweight from Equal Weight and raised its price target to $171 from $126, arguing the company is well positioned as a neutral identity layer across the broader cybersecurity ecosystem. The firm sees a healthy AI agent pipeline and expects rising demand for agent discovery, authentication and governance as enterprises deploy more autonomous workflows. Capital One also sees upside to estimates this year and into FY28 as these new identity use cases expand Okta’s addressable market.
### **Cybersecurity/DDOG: BNP Survey Shows Strong 2Q Spend but Softer Forward Intentions**
BNP’s quarterly reseller survey found cybersecurity remained the top IT spending priority over the past three months, while Datadog sales tracked a few points above plan on product functionality, competitive wins and strength in infrastructure monitoring, APM and AI-related use cases. However, overall IT spending intentions weakened sharply from April, and resellers expect cybersecurity momentum to trail other categories over the next three months, suggesting demand may have been concentrated in 2Q. DDOG’s forward spending score also fell to 2.0 from 5.4, creating a more mixed setup despite solid recent execution.
### **CRWD: Citi Raises PT to $250 as AI Expands Cybersecurity TAM and Reinforces Market Leadership**
Citi reiterates Buy and raises its split-adjusted price target to $250, arguing pre-quiet-period discussions reinforced confidence in high-20% near-term ARR growth and durable mid-20% growth thereafter. Early checks point to stronger eight-figure deal activity, while AI-driven attack surfaces, regulatory pressure and procurement disruption are increasing demand for CRWD’s broad platform, services footprint and Flex offerings. Although valuation is near peak levels and estimate revisions remain limited, Citi believes CrowdStrike is becoming a “cyber OEM” for emerging AI architectures, supporting higher multiples and outsized incremental budget capture.
### **NOW: Hearing Cleveland positive saying Q1 appeared to finish ahead with some pull forward benefit, although outlooks more mixed given model transition, competition, internal org changes, etc.**
### **DDOG: UBS Stays Buy as Customer Checks Support 30%+ Growth Despite a tougher Setup**
UBS maintains Buy after conversations with seven customers and three partners reinforced that observability remains a priority spend area as enterprises accelerate AI deployments. Checks improved versus late 2025/early 2026, with DDOG gaining share through vendor consolidation and expanding into hybrid environments, although pricing pushback remains the main friction point. UBS still sees 30%+ growth in 2026 and expects another acceleration in 2Q, but acknowledges the setup is tougher after the stock’s rally and valuation near 20x revenue and 75x FCF.
### **MSFT**: **Microsoft Gives Sellers Tips to Knock Down Anthropic, OpenAI**
**[Bloomberg](https://www.bloomberg.com/news/articles/2026-07-15/microsoft-gives-salespeople-tips-to-knock-down-anthropic-openai?accessToken=eyJhbGciOiJIUzI1NiIsInR5cCI6IkpXVCJ9.eyJzb3VyY2UiOiJTdWJzY3JpYmVyR2lmdGVkQXJ0aWNsZSIsImlhdCI6MTc4NDE0Mzk5NywiZXhwIjoxNzg0NzQ4Nzk3LCJhcnRpY2xlSWQiOiJUSTZBRVhLSkg2VjYwMCIsImJjb25uZWN0SWQiOiJEQ0FGMjNFM0YyMkE0Qzk5OTM0RUMyRDEwNkM0ODc0NyJ9.xkGGKI3U9CBk_UcIipQZOAOwxHuYwKKLBjaEedoT928&leadSource=article-gifting):**
**
[Microsoft Corp.](https://www.bloomberg.com/quote/MSFT:US) is coaching its sales team on how to vigorously compete against Anthropic PBC and OpenAI, playing up shortcomings in products from the artificial intelligence firms.
The software giant offers lower costs, better security controls and a more complete suite of products, Microsoft executives said during an internal meeting this week laying out the company’s sales strategy for the fiscal year that began this month.
### **WIX: Wells Fargo Keeps Equal Weight and Cuts PT to $46 as Web Traffic Weakens**
Wells Fargo maintains Equal Weight and lowers its price target to $46 from $47 after softer June web traffic led the firm to reduce 2H bookings by 2%, now modeling roughly 10% y/y growth versus Street at 12%. Base44 traffic also weakened late in the quarter, increasing the importance of ARR execution and returns on higher marketing investment as the core Wix business slows. Wells Fargo trims FY26/FY27 bookings by 1%/3% and non-GAAP operating income by 5%/3%, while expecting 3Q revenue guidance in the low double digits.
### **TEAM: BofA Keeps Neutral and Cuts PT to $105 as Data Center Transition Pushes Growth Trough to FY27**
BofA lowers FY27/FY28 revenue estimates by 4.3%/4.1% and cuts its price objective to $105 from $110, arguing accelerated Data Center migrations, shorter contract durations and renewal pull-forwards will create a choppy 12–24 month growth profile. The firm now models FY27 revenue of $7.17B, +11% y/y versus Street at $7.37B, +14%, and reduces Data Center revenue estimates by 16% in both FY27 and FY28. Cloud remains the key upside lever through higher tiers, seat expansion, cross-sell and pricing, but BofA stays Neutral pending greater clarity on the medium-term growth algorithm.
### **ZM: Wolfe Reiterates Outperform as AI Monetization and Voice API Make the Reacceleration Path More Tangible**
Wolfe reiterates Outperform after management meetings increased confidence that Zoom is evolving from a video collaboration platform into a broader “system of action” where AI completes work. The firm sees three growth levers: lower core churn, continued Phone and Contact Center share gains, and new horizontal AI products, with enterprise pricing discipline and ZCX execution the key swing factors. Wolfe highlights a net-new Voice API opportunity outside the seat-based model and a customer that increased spending more than 50% over three years, implying roughly 115% NRR, as early evidence that consumption-based AI monetization is working.
### **MNDY: Wells Fargo More Encouraged on AI Strategy and Emerging Consumption Monetization**
Wells Fargo came away more positive after management demonstrated MNDY Agents, which can automate workflows, create dashboards and interact with enterprise data across multiple frontier models, reinforcing monday.com’s ambition to become an orchestration layer connecting employees, agents and company data. AI demand is beginning to build in customer discussions, prompting greater GTM investment and an expanded FDE organization. Monetization remains early but is shifting toward a hybrid model, with new customers purchasing minimum AI-credit bundles.
# **LEFTOVERS**
### **SPCX: JPM Says Flight 13 Is a High-Profile Test of Starship V3 Reliability and Reusability**
JPM highlights SpaceX’s 13th Starship test flight—and second using the V3 configuration—as a potentially stock-moving milestone given Starship’s importance to future Starlink, AI-satellite and lunar missions. Flight 13 will test upgraded Super Heavy re-light reliability, an in-flight upper-stage engine restart and 20 Starlink V3 satellites, while providing new data on heat-shield performance ahead of eventual upper-stage recovery. JPM views the launch as one step toward dozens of annual flights next year and hundreds by 2028, with engine reliability, refurbishment time and in-space refueling remaining the key business-model hurdles.
### **ASTS: -12%** **seeking $1b in a convertible bond offering**
### **ASTS/SPCX/RKLB: Piper Prefers ASTS as the Clearest Space Monetization Story**
Piper initiates ASTS at Overweight with a $100 price target, while launching SPCX and RKLB at Neutral with $156 and $83 targets, respectively. ASTS is the preferred name given its operator-backed direct-to-device model, partnerships with AT&T, Vodafone, Rakuten and Verizon, and access to more than 3B potential subscribers, providing the clearest path to incremental revenue and EBITDA. Piper remains constructive on SPCX’s vertically integrated platform and long-term orbital AI opportunity, but sees substantial execution, capex and transaction risk, while RKLB’s strong launch record and Neutron upside are offset by a premium valuation relative to its smaller scale.
### **SNPS/CDNS: Benchmark Initiates Both at Buy as AI Drives a New EDA Productivity Cycle**
Benchmark initiates SNPS at Buy with a $570 price target and CDNS at Buy with a $450 target, arguing rising chip, packaging and system complexity will push EDA, IP and simulation vendors to capture a larger share of semiconductor R&D spending. AI-driven design tools should create a step-function improvement in engineer productivity and support faster industry growth, strong pricing power and durable margins. CDNS is viewed as the higher-quality share leader, while SNPS offers greater valuation catch-up potential if management rebuilds credibility and executes on Ansys synergies, new hyperscaler IP, Intel 14A exposure and China stabilization.
### **NVDA: NVIDIA Introduces New Jetson Thor Computers to Advance Mainstream Robotics and Edge AI**
[PR: ](https://blogs.nvidia.com/blog/jetson-thor-robotics-edge-ai-agent/)*New NVIDIA Blackwell-powered T3000 and T2000 modules, paired with new NVIDIA Jetson software memory optimization and agent skills, help partners and customers move advanced robotics, visual AI and edge workloads onto compact, power-efficient systems.*
决策记录链 · 只追加
每次领取产生一条记录,重新决策追加一条并以 supersedes 指向被替代的记录(ADR 0014)。
这条决策早于决策账本(2026-10-08 起逐条追加),没有追加记录。