TMT BreakoutCodex · 实盘不做把握 5/10
北京时间·🕒 发布 06:18:57时区推断·⟳ 抓取 06:44:58·⚡ 决策 07-28 06:46:49 +1m51s·91.8 天前
Celestica盘后公布二季度超预期并上调全年指引,但财报后追高胜率不足
Celestica二季度收入47.0亿美元、EPS 2.54美元均高于一致预期,并将全年收入/EPS指引上调至205亿美元/11.30美元。
📄 原文TMT Breakout↗ 原文
TMTB EOD Wrap
Good morning. **QQQs -30bps** as **Semis -2.2%** underperformed **Internet +4%** and **Software +2.5% **as the market d…
不做 Celestica(CLS.US)
财报本身是正面,但盘后已涨、同公司财报上调指引先例+3日胜率仅33%且中位数为负;等电话会后若回踩或给出更明确2027项目量级再由新信号接手。
展开详情(成交明细 / 研究档案 / 原文全文 / 决策记录链)
研究档案
消息传播链
- 公司日历显示Q2 2026财报电话会安排在2026-07-28 08:00 EDT,说明本次为正式财报周期披露而非传闻。
- TMTB盘后转述Celestica二季度beat and raise,并称盘后约+8%,强调组件供应改善、新项目和客户需求可见度提升。市场反应:stock_quote显示CLS.US截至2026-07-27 22:45 UTC报318.24美元,较前收+4.25%。
关键理由
- Celestica二季度收入47.0亿美元、EPS 2.54美元均高于一致预期,并将全年收入/EPS指引上调至205亿美元/11.30美元。
- 公司称2027年收入增速将超过2026年预计65%的增长,AI数据中心相关的新项目和客户需求仍在增强。
- 但CLS.US盘后已涨至318.24美元、较前收+4.25%,且同公司近三次类似财报/上调指引先例+3日胜率仅33%、中位数-2.99%,追开盘缺乏正期望。
主要风险
- 若次日电话会进一步确认2027年大客户项目规模或毛利率上修,可能继续触发卖方上修并造成踏空。
- 近期股价距60日高点仍低约33%,但波动率和财报后高开低走历史较高,不能用低位替代入场边际。
反向证据
- 做多前查反向 · 来源 kb_search · 日期 2026-07-27 · 影响 none
内部库命中巴克莱财报前瞻覆盖CLS,但未命中能显著改变本次做多判断的新增反证;主要风险仍是财报后预期兑现和AI硬件去风险环境。
检索:Celestica CLS AI revenue guidance component supply new program wins customer demand 2027 原文 ↗ - 做多前查反向 · 来源 web · 日期 2026-07-27 · 影响 weakens
公开检索未发现公司级辟谣或重大负面新增事实,但财报类正面信息已盘后同向反应且历史追高胜率偏低。
检索:Celestica Q2 2026 earnings guidance risk margin component supply customer concentration 原文 ↗
历史先例(按相似度)
- 相似度 9/10 CLS.US 2025-07-28 Celestica Q2 2025收入/EPS超高端并上调2025年展望。 原文 ↗
CLS.US财报后+1日+16.51%、+3日+15.28%、+5日+16.20%。
相似度依据:同一公司、同为二季度财报超预期并上调全年展望,事件相位最接近本次。 - 相似度 8/10 CLS.US 2026-04-27 Celestica Q1 2026 EPS小超并上调全年营收/EPS,延续AI数据中心需求叙事。 原文 ↗
CLS.US财报后+1日-14.37%、+3日-2.99%、+5日-0.35%。
相似度依据:同一公司、同为盘后财报并上调全年展望,但Q1后的市场环境与本次AI半导体去风险阶段不完全一致。 - 相似度 8/10 CLS.US 2026-01-28 Celestica Q4 2025业绩超高端并上调2026年收入/EPS展望。 原文 ↗
CLS.US财报后+1日-13.10%、+3日-17.41%、+5日-20.09%。
相似度依据:同一公司、同为强财报和上调下一年展望,能直接校准财报后追高风险。
工具调用 · 历史记录,结果未知(4 种)
- search_processed_events · 结果未知
- stock_quote · 结果未知
- kb_search · 结果未知
- event_study · 结果未知
原文全文
展开原文 · 11,919 字
Good morning. **QQQs -30bps** as **Semis -2.2%** underperformed **Internet +4%** and **Software +2.5% **as the market digested NVDA’s $250B financing guarantee. TMT Momentum down another 8%. We were gone for a week, but it seems like not much has changed in respect to the overarching market/AI semi narrative & price action, which feels very similar to last fall’s ASS (After Sam’s Splurge) environment. How are we thinking about things on our first day back from vacation?
Yes, semis are a bit lower than a couple weeks ago, but we think the main difference sentiment wise is that (most some) bulls have accepted we are in a new AI semi environment unlike May and June’s go-go days, and the outstanding questions around open source/frontier viability/credit yields moving up/sustainability of the cycle past ‘28/hyperscaler ROI, etc. are unlikely to be solved any time soon. If every LT AI Bull coming out to defend the trade after Kimi’s K3, INTC’s big print, GOOGL’s 80%+ GCP # and various other positive news developments aren’t enough to get semis to sustainably rally over the last week, bulls are asking themselves what it will take to get the mojo back. The continued factor whiplash / macro-overhangs doesn’t help to inspire risk-on confidence (and now midterms are around the corner!).
In terms of positioning, in our initial conversations today with other investors after coming back from vacation, I get the sense there has been a good amount of de-risking/de-grossing that has been going on, especially from some of the smarter medium-term vibe guys I talk to.
The types of questions LT bulls are asking (can AI semis ever go up?) are usually the hallmarks of some sort of short-term bottom and there’s a good argument/signs on the charts/sentiment wise for us being there today (that’s our relatively low conviction base case - tricky with FOMC ahead of us on wed). Generally, we stick to the gameplan we’ve been expressing over the last few weeks: despite SOX hitting new 3-month lows, our base case continues to be more chop and don’t think we go outright negative or positive unless there are some big new major developments in either direction. That means being patient before pressing the pedal on gross — we think the market needs to breathe and digest the outstanding questions mentioned above. Practically, it means fading extremes in price & sentiment and not getting emotionally excited in either direction. Don’t get chopped up. Running lower gross. Shorter duration trades. Paying more attention to shifts in narratives. Stay away from the more spec names. Focusing on catalysts & risk/reward trades.
It’s as tricky a trading environment as I’ve seen in a while — there are times to bask in the HOT AI SUMMER vibes and press the accelerator down. There are other times like now when it’s time to bask in the good ol’ outdoor summer vibes.
Lots of good discussion on the debate in AI semis right now in TMTB Slack in this thread [here](https://tmtbreakout.slack.com/archives/C0A7X6WKVB2/p1785172476115269).
**Post-close CLS +8%** looks solid with a solid beat and raise above buyside expects as they cited improved component supply with visibility increasing driven by new program wins/customer demand.
**Q2 Results**
Revenue: $4.70B vs. Street $4.39B
EPS: $2.54 vs. Street $2.30
CCS revenue: $3.81B vs. Street $3.52B
ATS revenue: $890M vs. Street $864.9M
Gross margin: 11.5% vs. Street 11.4%
Operating margin: 8.2% vs. Street 8.0%
**Q4 Guidance**
Revenue: $5.25B–$5.55B vs. Street $5.00B
EPS: $2.88–$3.08 vs. Street $2.69
**FY Guidance**
Revenue: $20.50B vs. Street $19.21B
EPS: $11.30 vs. Street $10.28
PR:
*“Looking beyond 2026, our visibility continues to increase. Driven by very strong customer demand, and supported by new program wins, we expect revenue growth in 2027 to accelerate beyond the 65% growth rate we are anticipating in 2026. We also anticipate adjusted EPS (non-GAAP)* to grow at a faster rate than our revenue in 2027, driven by higher expected adjusted operating margin (non-GAAP)**
Ok let’s get to the good stuff…
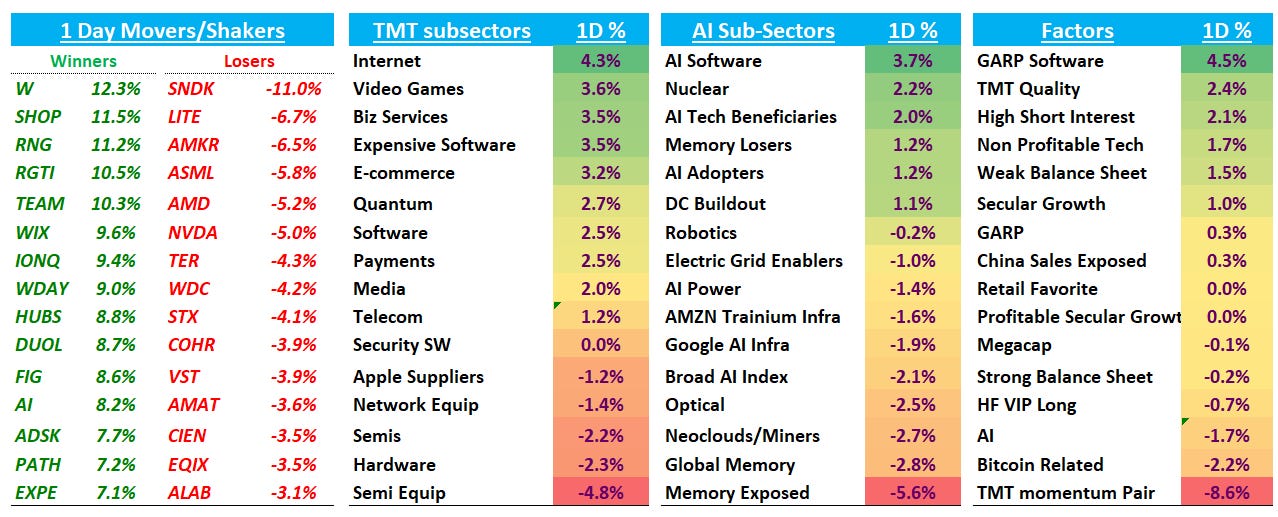
# **AI/SEMIS**
Some positive RSI divergence on a double bottom on the SOX, along with extreme volume

-
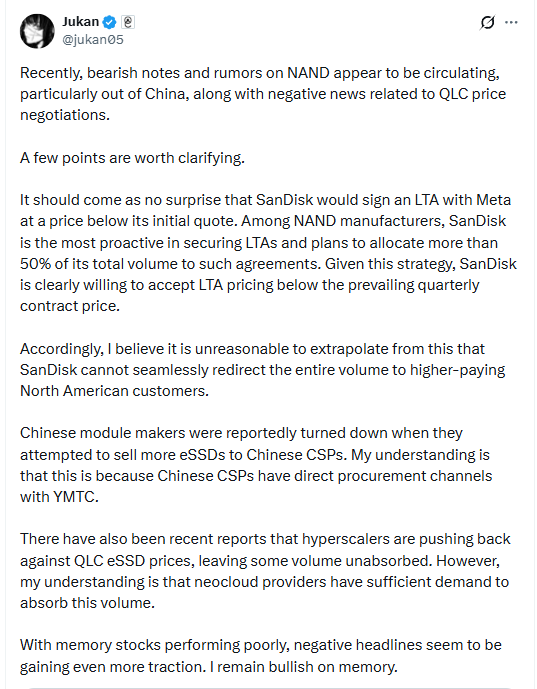
Not a good day for memory with **SNDK -11%, SKHY -8%, MU -2% **after Chinese DRAM maker **CXMT** was +**466**% overnight. ** SNDK** the big loser as some pointed to Trendforce data showing slowing ASP increases in Q3 vs Q2: NAND +13% in Q3 vs 58% in Q2. Also some Chinese rumors floating around NAND:

Hard looking at the GPL log chart on Bloomberg, but SNDK now down close to about 50% from the peak at sitting at 61.8% fib retracement on the chart and just blew past what we thought was a decent r/r near $1,500. Memory trade continues to suffer from downtick in sentiment post the MU print as investors concerns around lack of earnings upside and given news noise (NVDA SOCAMM/NVL72 de-spec, supply coming online). And well it just has one of the largest betas in the semi trade and was one of the most crowded so the unwind has hit it the most. [FMS memory conference ](https://www.terrapinn.com/conference/future-memory-storage/index.stm)coming up, and agenda shows that KV cache offload should be a big part of the conversations. Catalyst + decent r/r + fade sentiment/price extreme — prob makes sense for another short-term long trade if we stick to our process.
Randy had a good long post in TMTB Slack around impact of CXMT supply on DRAM. Full post worth reading [here](https://tmtbreakout.slack.com/archives/C0A7X6WKVB2/p1785171901256899). Here’s a summary:

_TMTB Slack_
-
**ASML -6%** as TheInformation was out saying China Begins Mass Production of Homegrown DUV Chip Tools:
**
**A Chinese state-backed** company has begun manufacturing one of the key pieces of equipment used in chip manufacturing for the first time, a significant development in Beijing’s drive to reduce its reliance on foreign technology to make chips.
The Shanghai-based company is making immersion deep ultraviolet lithography machines, used by chipmakers such as Taiwan Semiconductor Manufacturing Co. in the production of chips, according to two people familiar with the situation.
JPM was out commenting saying near-term risk to ASML appears more sentiment-driven (rather than any hit to #s) until the systems demonstrate the stability, yield and throughput required for high-volume manufacturing, also noting semi specialist feedback largely dismissed the report as clickbait.
-
**STX/WDC -4%** despite some positive pricing checks. MS — who is one of better analysts on the name was out saying CY27-28 pricing discussions moving toward $25-$30/TB and spot EBs commanding 30-40% premiums and 300-400 EB annual supply shortfall through 2028 (implying 75% EPS CAGR through ‘28). Cleveland was also out confirming those checks saying CY27 pricing continue to fill in at $20-$30/TB with some even reaching $30+. Remember, pricing a big lever here (You can get close to $100 of EPS for STX at $30/TB). Still a pair of our favorite names despite the pullback and think should o/p in a choppy environment. Narrative here now has risen up the rankings given the memory turbulance. With all the debate around compute, we keep coming back to this quote from WDC CEO a couple months ago:
**
*Compute power is reused all the time — it takes a few seconds to generate a token, and then that compute is available again to generate something else. That’s not the case with storage. Storage keeps compounding: every time you generate a token and an output, that gets stored. So every time you use compute power, you get more and more storage out of it. **In** **my mind, even if CapEx on compute and memory slows down over time — who knows — that does not indicate to me that the spend on storage will slow down. It’s decoupled.***
-
Quantum bid today: **IONQ/RGTI +10%**. Interesting tea leaf given they topped a couple weeks before general semis. Semi spec names like NVTS +4.5%/WOLF +3% catching a bid also interesting tea leaf given those names also rolled over before the index.
-
**NVDA -5%. AMD -5%** - stock had outperformed nicely heading into AI day but with that in rear-view and INTC’s ugly price action post EPS, some sell the news post the event. **AVGO +30bps** has acted relatively well past couple of weeks.
-
Analogs with some outperformance: **STM +4/ON +3%/TXN flat**
# **INTERNET**
-
**SHOP +12**% as Cleveland was out positive saying Q2 finished well ahead on GMV/payments upside and share gains. Sentiment here still remains mixed - buyside wants to get more positive on some sort of price increase in 1H’27 and likely upside to top line while long-onlys struggling with META’s ecomm ambitions & the optics of "“increasingly variable cost structure against fixed rev model = big problem.”
-
Hypers mixed: **GOOGL +2%** getting some love after last week’s disaster but **META/AMZN -20bps.**

-
**RDDT +6%** continues to see-saw
-
**DUOL +8%:** didn’t see anything out there today, but 3p continues to show a 10% bookings # vs street at 7%. Only incremental thing I’ve heard on the narrative is that cheaper open source models should help alleviate some of the gross margin pressure they have been calling out as they roll out AI features to their sub base, although the AI argument cuts both ways (easier for top line disintermediation).
# **SOFTWARE**
-
**RNG +11% / SAP +7%** nice follow through after last week’s beats.
-
Lots of strength from app sw/”Ai Losers”: **FIG +8%; NOW +7%; WDAY +9%; HUBS +9%;** **CRM +6%; MNDY +6%** and so on…
-
**MSFT +2%** bucking the **META/AMZN** weakness. Bogeys here sit around 41-42% for the Azure guide. FundaAI was out saying their checks showing big ramp up in co-pilot adds in the June quarter.
-
**DOCN -3**% getting grouped in the semi trade. AKAM -2% also off despite positive ISI note modeling out CIS capacity saying build could add about $164M of revenue in CY27 and $464M in CY28, lifting total growth to roughly 13.8% and 13.6% versus Street at 10.6% and 7.4%, while full deployment could support about $1.3B of annual revenue.
-
**U +6%**: checks through June here sounded decent as with a friend passing along check showing June daily GMV growth accel’d to 90s vs 80% in May with the m/m +15% increase the strongest in data set. This data been out there for a couple weeks now - I’m just catching up to it, but should get some initial July checks early next week.
-
**ORCL +4%:** huh, this stock can go green.
# **ELSEWHERE**
-
**TTWO +5% l**ooks like it wants another shot at highs. Raymond James was out today with a survey of more than 500 U.S. men ages 18–40 pointing to stronger-than-expected GTA VI demand, with roughly three-quarters planning to purchase before or near launch and more than half favoring the $100 Ultimate Edition. They think that implies 50M at an ASP just below $90.
-
**AAPL +1%** continues to hit new highs as they look like geniuses (so far) in this environment after not splurging on capex
# **BULLISH AND BEARISH WEEKLY OPTION FLOW**

# Good to be back. See you tomorrow
Yes, semis are a bit lower than a couple weeks ago, but we think the main difference sentiment wise is that (most some) bulls have accepted we are in a new AI semi environment unlike May and June’s go-go days, and the outstanding questions around open source/frontier viability/credit yields moving up/sustainability of the cycle past ‘28/hyperscaler ROI, etc. are unlikely to be solved any time soon. If every LT AI Bull coming out to defend the trade after Kimi’s K3, INTC’s big print, GOOGL’s 80%+ GCP # and various other positive news developments aren’t enough to get semis to sustainably rally over the last week, bulls are asking themselves what it will take to get the mojo back. The continued factor whiplash / macro-overhangs doesn’t help to inspire risk-on confidence (and now midterms are around the corner!).
In terms of positioning, in our initial conversations today with other investors after coming back from vacation, I get the sense there has been a good amount of de-risking/de-grossing that has been going on, especially from some of the smarter medium-term vibe guys I talk to.
The types of questions LT bulls are asking (can AI semis ever go up?) are usually the hallmarks of some sort of short-term bottom and there’s a good argument/signs on the charts/sentiment wise for us being there today (that’s our relatively low conviction base case - tricky with FOMC ahead of us on wed). Generally, we stick to the gameplan we’ve been expressing over the last few weeks: despite SOX hitting new 3-month lows, our base case continues to be more chop and don’t think we go outright negative or positive unless there are some big new major developments in either direction. That means being patient before pressing the pedal on gross — we think the market needs to breathe and digest the outstanding questions mentioned above. Practically, it means fading extremes in price & sentiment and not getting emotionally excited in either direction. Don’t get chopped up. Running lower gross. Shorter duration trades. Paying more attention to shifts in narratives. Stay away from the more spec names. Focusing on catalysts & risk/reward trades.
It’s as tricky a trading environment as I’ve seen in a while — there are times to bask in the HOT AI SUMMER vibes and press the accelerator down. There are other times like now when it’s time to bask in the good ol’ outdoor summer vibes.
Lots of good discussion on the debate in AI semis right now in TMTB Slack in this thread [here](https://tmtbreakout.slack.com/archives/C0A7X6WKVB2/p1785172476115269).
**Post-close CLS +8%** looks solid with a solid beat and raise above buyside expects as they cited improved component supply with visibility increasing driven by new program wins/customer demand.
**Q2 Results**
Revenue: $4.70B vs. Street $4.39B
EPS: $2.54 vs. Street $2.30
CCS revenue: $3.81B vs. Street $3.52B
ATS revenue: $890M vs. Street $864.9M
Gross margin: 11.5% vs. Street 11.4%
Operating margin: 8.2% vs. Street 8.0%
**Q4 Guidance**
Revenue: $5.25B–$5.55B vs. Street $5.00B
EPS: $2.88–$3.08 vs. Street $2.69
**FY Guidance**
Revenue: $20.50B vs. Street $19.21B
EPS: $11.30 vs. Street $10.28
PR:
*“Looking beyond 2026, our visibility continues to increase. Driven by very strong customer demand, and supported by new program wins, we expect revenue growth in 2027 to accelerate beyond the 65% growth rate we are anticipating in 2026. We also anticipate adjusted EPS (non-GAAP)* to grow at a faster rate than our revenue in 2027, driven by higher expected adjusted operating margin (non-GAAP)**
Ok let’s get to the good stuff…

# **AI/SEMIS**
Some positive RSI divergence on a double bottom on the SOX, along with extreme volume

-
Not a good day for memory with **SNDK -11%, SKHY -8%, MU -2% **after Chinese DRAM maker **CXMT** was +**466**% overnight. ** SNDK** the big loser as some pointed to Trendforce data showing slowing ASP increases in Q3 vs Q2: NAND +13% in Q3 vs 58% in Q2. Also some Chinese rumors floating around NAND:


Hard looking at the GPL log chart on Bloomberg, but SNDK now down close to about 50% from the peak at sitting at 61.8% fib retracement on the chart and just blew past what we thought was a decent r/r near $1,500. Memory trade continues to suffer from downtick in sentiment post the MU print as investors concerns around lack of earnings upside and given news noise (NVDA SOCAMM/NVL72 de-spec, supply coming online). And well it just has one of the largest betas in the semi trade and was one of the most crowded so the unwind has hit it the most. [FMS memory conference ](https://www.terrapinn.com/conference/future-memory-storage/index.stm)coming up, and agenda shows that KV cache offload should be a big part of the conversations. Catalyst + decent r/r + fade sentiment/price extreme — prob makes sense for another short-term long trade if we stick to our process.
Randy had a good long post in TMTB Slack around impact of CXMT supply on DRAM. Full post worth reading [here](https://tmtbreakout.slack.com/archives/C0A7X6WKVB2/p1785171901256899). Here’s a summary:

_TMTB Slack_
-
**ASML -6%** as TheInformation was out saying China Begins Mass Production of Homegrown DUV Chip Tools:
**
**A Chinese state-backed** company has begun manufacturing one of the key pieces of equipment used in chip manufacturing for the first time, a significant development in Beijing’s drive to reduce its reliance on foreign technology to make chips.
The Shanghai-based company is making immersion deep ultraviolet lithography machines, used by chipmakers such as Taiwan Semiconductor Manufacturing Co. in the production of chips, according to two people familiar with the situation.
JPM was out commenting saying near-term risk to ASML appears more sentiment-driven (rather than any hit to #s) until the systems demonstrate the stability, yield and throughput required for high-volume manufacturing, also noting semi specialist feedback largely dismissed the report as clickbait.
-
**STX/WDC -4%** despite some positive pricing checks. MS — who is one of better analysts on the name was out saying CY27-28 pricing discussions moving toward $25-$30/TB and spot EBs commanding 30-40% premiums and 300-400 EB annual supply shortfall through 2028 (implying 75% EPS CAGR through ‘28). Cleveland was also out confirming those checks saying CY27 pricing continue to fill in at $20-$30/TB with some even reaching $30+. Remember, pricing a big lever here (You can get close to $100 of EPS for STX at $30/TB). Still a pair of our favorite names despite the pullback and think should o/p in a choppy environment. Narrative here now has risen up the rankings given the memory turbulance. With all the debate around compute, we keep coming back to this quote from WDC CEO a couple months ago:
**
*Compute power is reused all the time — it takes a few seconds to generate a token, and then that compute is available again to generate something else. That’s not the case with storage. Storage keeps compounding: every time you generate a token and an output, that gets stored. So every time you use compute power, you get more and more storage out of it. **In** **my mind, even if CapEx on compute and memory slows down over time — who knows — that does not indicate to me that the spend on storage will slow down. It’s decoupled.***
-
Quantum bid today: **IONQ/RGTI +10%**. Interesting tea leaf given they topped a couple weeks before general semis. Semi spec names like NVTS +4.5%/WOLF +3% catching a bid also interesting tea leaf given those names also rolled over before the index.
-
**NVDA -5%. AMD -5%** - stock had outperformed nicely heading into AI day but with that in rear-view and INTC’s ugly price action post EPS, some sell the news post the event. **AVGO +30bps** has acted relatively well past couple of weeks.
-
Analogs with some outperformance: **STM +4/ON +3%/TXN flat**
# **INTERNET**
-
**SHOP +12**% as Cleveland was out positive saying Q2 finished well ahead on GMV/payments upside and share gains. Sentiment here still remains mixed - buyside wants to get more positive on some sort of price increase in 1H’27 and likely upside to top line while long-onlys struggling with META’s ecomm ambitions & the optics of "“increasingly variable cost structure against fixed rev model = big problem.”
-
Hypers mixed: **GOOGL +2%** getting some love after last week’s disaster but **META/AMZN -20bps.**

-
**RDDT +6%** continues to see-saw
-
**DUOL +8%:** didn’t see anything out there today, but 3p continues to show a 10% bookings # vs street at 7%. Only incremental thing I’ve heard on the narrative is that cheaper open source models should help alleviate some of the gross margin pressure they have been calling out as they roll out AI features to their sub base, although the AI argument cuts both ways (easier for top line disintermediation).
# **SOFTWARE**
-
**RNG +11% / SAP +7%** nice follow through after last week’s beats.
-
Lots of strength from app sw/”Ai Losers”: **FIG +8%; NOW +7%; WDAY +9%; HUBS +9%;** **CRM +6%; MNDY +6%** and so on…
-
**MSFT +2%** bucking the **META/AMZN** weakness. Bogeys here sit around 41-42% for the Azure guide. FundaAI was out saying their checks showing big ramp up in co-pilot adds in the June quarter.
-
**DOCN -3**% getting grouped in the semi trade. AKAM -2% also off despite positive ISI note modeling out CIS capacity saying build could add about $164M of revenue in CY27 and $464M in CY28, lifting total growth to roughly 13.8% and 13.6% versus Street at 10.6% and 7.4%, while full deployment could support about $1.3B of annual revenue.
-
**U +6%**: checks through June here sounded decent as with a friend passing along check showing June daily GMV growth accel’d to 90s vs 80% in May with the m/m +15% increase the strongest in data set. This data been out there for a couple weeks now - I’m just catching up to it, but should get some initial July checks early next week.
-
**ORCL +4%:** huh, this stock can go green.
# **ELSEWHERE**
-
**TTWO +5% l**ooks like it wants another shot at highs. Raymond James was out today with a survey of more than 500 U.S. men ages 18–40 pointing to stronger-than-expected GTA VI demand, with roughly three-quarters planning to purchase before or near launch and more than half favoring the $100 Ultimate Edition. They think that implies 50M at an ASP just below $90.
-
**AAPL +1%** continues to hit new highs as they look like geniuses (so far) in this environment after not splurging on capex
# **BULLISH AND BEARISH WEEKLY OPTION FLOW**

# Good to be back. See you tomorrow
决策记录链 · 只追加
每次领取产生一条记录,重新决策追加一条并以 supersedes 指向被替代的记录(ADR 0014)。
这条决策早于决策账本(2026-10-08 起逐条追加),没有追加记录。