Flyover StocksCodex · 实盘不做把握 7/10
北京时间·🕒 发布 21:39:22时区推断·⟳ 抓取 22:00:33·⚡ 决策 07-16 22:03:04 +2m31s·103.2 天前
ABB拟以现金高溢价收购英国阀门执行器公司Rotork,目标股已跳至接近要约价
Rotork是现金收购目标,503p现金要约加最高3p股息已公开,股价盘中已大涨约67%至485p附近,剩余空间主要是并购套利而非事件弹性。
📄 原文Flyover Stocks↗ 原文
Rotork Acquired for a Huge Premium
Back in January 2025, I profiled **Rotork plc (ROR.L)**, a nearly 70-year-old U.K. maker of mission-critical flow contr…
不做 Rotork(ROR.GB)
现金收购目标股已盘中大涨约67%并接近503p现金要约价,剩余为并购套利价差且非本系统优势,不追。
不做 ABB(ABB.US)
收购方短线偏负面但不是明确强空催化,且ABB同时上调收入指引;不满足做空红线,回避。
展开详情(成交明细 / 研究档案 / 原文全文 / 决策记录链)
研究档案
消息传播链
- 早于Flyover文章数小时已报道ABB同意以每股503p收购Rotork,说明事件不是Flyover首发。
- Reuters报道ABB宣布55亿美元收购Rotork,并称ABB仍有约140亿美元并购火力。市场反应:页面显示Rotork约+67.02%,ABB约-4.78%。
- ABB官方公告确认以每股503p现金收购Rotork,交易预计2027年上半年完成。
- WSJ报道Rotork董事会支持交易,目标股欧洲早盘涨约67%至485.4p,ABB瑞士股跌约2.9%。市场反应:Rotork已接近现金要约价,剩余套利空间有限。
- Flyover文章主要复盘其2025年对Rotork的公司画像,不提供新的可交易增量。
关键理由
- Rotork是现金收购目标,503p现金要约加最高3p股息已公开,股价盘中已大涨约67%至485p附近,剩余空间主要是并购套利而非事件弹性。
- ABB作为收购方,美股盘中下跌约1.2%,交易方向偏负面但不是足够强的做空催化,且未满足做空红线。
- 交易窗口上,目标股利好已在伦敦盘中基本兑现,收购方影响相对其体量较小,无法形成清晰正期望同向交易。
主要风险
- 若出现竞购方或ABB提高报价,Rotork仍可能继续向上,但这属于并购套利/新信息,不适合在当前事件后追入。
- ABB若后续披露协同或资本回报超预期,收购方短线负面反应可能逆转。
反向证据
- 做多前查反向 · 来源 web · 日期 2026-07-16 · 影响 weakens
目标股已跳涨至接近现金要约价,剩余收益主要是并购套利价差而非事件反应窗口。
检索:Rotork ABB acquisition 503p share price 485p July 16 2026 原文 ↗ - 做空前查反向 · 来源 web · 日期 2026-07-16 · 影响 weakens
ABB同时上调全年可比收入增长指引,且称交易完成后增厚盈利,削弱单纯因收购溢价做空ABB的理由。
检索:ABB Rotork acquisition revenue boost profitability guidance Q2 2026 原文 ↗
工具调用 · 历史记录,结果未知(1 种)
- stock_quote · 结果未知
原文全文
展开原文 · 5,065 字
Back in January 2025, I profiled **Rotork plc (ROR.L)**, a nearly 70-year-old U.K. maker of mission-critical flow control actuators.
Today, **ABB** announced it plans to acquire Rotork in an all-cash deal at 503 pence per share, valuing Rotork at roughly $5.5 billion in enterprise value - a 73% premium to the previous day’s close.
#### **Profile summary**
Like every other Flyover Stocks profile, the Rotork report wasn’t a “buy” call. Using my moat, management, and forecastability framework, Rotork scored 3.0 out of 5, or middle of the pack relative to other companies I’d profiled.
That said, most of the demerits were due to a relatively new management team and low relative forecastability and simplicity scores, with Rotork selling into the oil & gas industry.
The moat, however, I found to be quite impressive - it scored a 4 in Moat Width and Depth.
A few things stood out enough to write about in January 2025:
-
**Deep switching costs / cost of failure avoidance.** Rotork’s actuators are a small fraction of the cost of the systems in which they’re installed, but failure is expensive. Once installed, customers don’t swap them out on price alone.
-
**Best-in-peer-set returns on capital.** At the time of the report, Rotork’s ROIC (~21%) was meaningfully ahead of the group I compared it against, including ABB (the acquirer), **Emerson**, and **Flowserve**.
-
**A valuation that didn’t match the fundamentals.** Rotork was trading at the bottom of its peer group on P/E and EV/EBITDA despite having margins and returns near the top of the group.
-
**A newer leadership team not yet getting credit.** CEO Kiet Huynh’s “Growth+” strategy was showing early results (double-digit revenue and profit growth in H1 2024) but hadn’t fully changed the market’s mind yet.
[Subscribe now](https://www.flyoverstocks.com/subscribe?)
#### **What surprised me**
In the profile, I also flagged real reasons for caution, such as heavy oil & gas cyclicality, a run of management turnover through the 2010s, and low forecastability given currency and end-market swings. These factors kept me from buying the stock myself, along with the fact my portfolio was already overweight industrials.
Save a spike in the share price following the start of the US-Iran conflict, Rotork’s stock had been lackluster at best since last January, and multiples fell further recently as oil prices returned closer to pre-conflict levels.
I’m less surprised that Rotork was acquired by a strategic buyer than I am the multiples ABB paid for Rotork - 5.3x revenue and 19.5x EBITDA, which are a considerable premium to the 20-year averages of 3.6x and 14.8x, respectively.
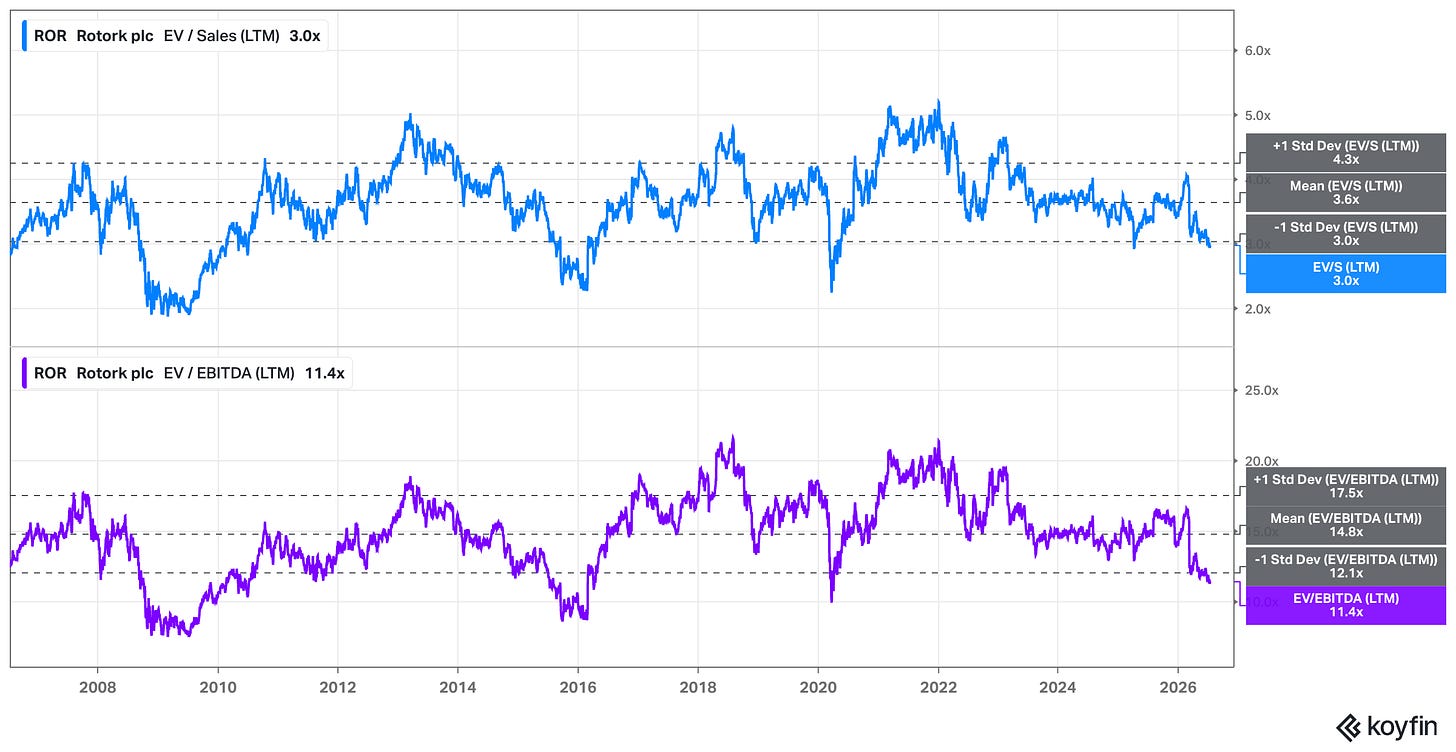
_Source: Koyfin, as of July 16, 2026. Flyover Stocks readers can get a special offer from Koyfin by [clicking here](https://www.koyfin.com/affiliate/flyover-stocks/?via=todd)!_
I would not have used those multiples to determine a fair price, but I noted in the original profile that:
With a starting free cash flow yield just under 5%, paired with the potential for high-single digit free cash flow per share growth (aided by mid- to high-revenue growth and some margin expansion), it’s an attractive setup to consider if you are looking for a quality mid-cap company in the global industrial space.
Good on Rotork for getting such an attractive offer. I’m not sure if there was an active auction for Rotork, but given the huge premium, I suspect there were competing bids.
#### **The takeaway**
I don’t write these profiles as buy recommendations. I write them to find durable, underappreciated businesses that I should keep on my radar. Writing them forces me as a portfolio manager to regularly compare the prospects of my current holdings against new ideas I may not have previously considered.
While Rotork didn’t find a place in my portfolios, this is a decent reminder that the gap between good business and cheap stock doesn’t stay open forever.
It seems like you'd rather find businesses like this while they're still overlooked, not after the acquisition headline. That's what the Flyover Stocks archive is for: 30+ profiles, each run through the same moat/management/forecastability framework. Upgrade to paid for full access.
**
Stay patient, stay focused.
Todd
*Todd Wenning is the President & CIO of [KNA Capital Management, LLC](https://www.kna-capital.com/), an Ohio-registered investment advisor that manages a concentrated equity strategy and provides other investment-related services.*
*At the time of publication, the author, his immediate family, and/or KNA Capital Management, LLC or its clients do not have positions in any company mentioned.*
*Please see important [disclaimers](https://www.flyoverstocks.com/p/disclaimers).*
Industrial conglomerate ABB pays a pretty penny for the high quality industrial niche operator
Today, **ABB** announced it plans to acquire Rotork in an all-cash deal at 503 pence per share, valuing Rotork at roughly $5.5 billion in enterprise value - a 73% premium to the previous day’s close.
#### **Profile summary**
Like every other Flyover Stocks profile, the Rotork report wasn’t a “buy” call. Using my moat, management, and forecastability framework, Rotork scored 3.0 out of 5, or middle of the pack relative to other companies I’d profiled.
That said, most of the demerits were due to a relatively new management team and low relative forecastability and simplicity scores, with Rotork selling into the oil & gas industry.
The moat, however, I found to be quite impressive - it scored a 4 in Moat Width and Depth.
A few things stood out enough to write about in January 2025:
-
**Deep switching costs / cost of failure avoidance.** Rotork’s actuators are a small fraction of the cost of the systems in which they’re installed, but failure is expensive. Once installed, customers don’t swap them out on price alone.
-
**Best-in-peer-set returns on capital.** At the time of the report, Rotork’s ROIC (~21%) was meaningfully ahead of the group I compared it against, including ABB (the acquirer), **Emerson**, and **Flowserve**.
-
**A valuation that didn’t match the fundamentals.** Rotork was trading at the bottom of its peer group on P/E and EV/EBITDA despite having margins and returns near the top of the group.
-
**A newer leadership team not yet getting credit.** CEO Kiet Huynh’s “Growth+” strategy was showing early results (double-digit revenue and profit growth in H1 2024) but hadn’t fully changed the market’s mind yet.
[Subscribe now](https://www.flyoverstocks.com/subscribe?)
#### **What surprised me**
In the profile, I also flagged real reasons for caution, such as heavy oil & gas cyclicality, a run of management turnover through the 2010s, and low forecastability given currency and end-market swings. These factors kept me from buying the stock myself, along with the fact my portfolio was already overweight industrials.
Save a spike in the share price following the start of the US-Iran conflict, Rotork’s stock had been lackluster at best since last January, and multiples fell further recently as oil prices returned closer to pre-conflict levels.
I’m less surprised that Rotork was acquired by a strategic buyer than I am the multiples ABB paid for Rotork - 5.3x revenue and 19.5x EBITDA, which are a considerable premium to the 20-year averages of 3.6x and 14.8x, respectively.

_Source: Koyfin, as of July 16, 2026. Flyover Stocks readers can get a special offer from Koyfin by [clicking here](https://www.koyfin.com/affiliate/flyover-stocks/?via=todd)!_
I would not have used those multiples to determine a fair price, but I noted in the original profile that:
With a starting free cash flow yield just under 5%, paired with the potential for high-single digit free cash flow per share growth (aided by mid- to high-revenue growth and some margin expansion), it’s an attractive setup to consider if you are looking for a quality mid-cap company in the global industrial space.
Good on Rotork for getting such an attractive offer. I’m not sure if there was an active auction for Rotork, but given the huge premium, I suspect there were competing bids.
#### **The takeaway**
I don’t write these profiles as buy recommendations. I write them to find durable, underappreciated businesses that I should keep on my radar. Writing them forces me as a portfolio manager to regularly compare the prospects of my current holdings against new ideas I may not have previously considered.
While Rotork didn’t find a place in my portfolios, this is a decent reminder that the gap between good business and cheap stock doesn’t stay open forever.
It seems like you'd rather find businesses like this while they're still overlooked, not after the acquisition headline. That's what the Flyover Stocks archive is for: 30+ profiles, each run through the same moat/management/forecastability framework. Upgrade to paid for full access.
**
Stay patient, stay focused.
Todd
*Todd Wenning is the President & CIO of [KNA Capital Management, LLC](https://www.kna-capital.com/), an Ohio-registered investment advisor that manages a concentrated equity strategy and provides other investment-related services.*
*At the time of publication, the author, his immediate family, and/or KNA Capital Management, LLC or its clients do not have positions in any company mentioned.*
*Please see important [disclaimers](https://www.flyoverstocks.com/p/disclaimers).*
Industrial conglomerate ABB pays a pretty penny for the high quality industrial niche operator
决策记录链 · 只追加
每次领取产生一条记录,重新决策追加一条并以 supersedes 指向被替代的记录(ADR 0014)。
这条决策早于决策账本(2026-10-08 起逐条追加),没有追加记录。