TMT BreakoutDoubao · 实盘不做把握 5/10不做原因:风险收益比不佳
北京时间·🕒 发布 20:41:09·⟳ 抓取 21:10:36 +29m27s·⚡ 决策 10-12 21:12:53 +2m17s·15.2 天前
TMTB晨报合集:The Information称Anthropic已与IREN秘密签订多年期云协议,IREN盘前一度冲高9%后回落
晨报为信息聚合,绝大多数是分析师评级或已公开旧闻;唯一新鲜单名催化(IREN-Anthropic未官宣云协议)来自可信媒体但无容量/金额条款、未经双方确认,且盘前已大涨并从+9%回落至+4.5%,在不可量化增量、无法确认重大性的情况下追高正期望不足,故不做。
📄 原文TMT Breakout↗ 原文
TMTB Morning Wrap
Good morning. **QQQs -25bps / SPY +2bps** on a fairly quiet start to the week macro wise. Bond market closed for the US…
不做 IREN Limited(IREN.US)
未官宣、无MW/金额条款的传闻级利好,盘前已自+9%回落至+4.5%、快速定价且冲高回落,叠加近20日-20%的下行高波动,增量重大性不可量化、追高风险回报差;等IREN/Anthropic官方公布容量与合同金额、且开盘有承接后再评估,不做。
展开详情(成交明细 / 研究档案 / 原文全文 / 决策记录链)
研究档案
结论摘要
The Information称Anthropic与IREN秘签多年期云协议,方向利好但条款未披露且未官宣;IREN盘前冲高9%后回落至+4.5%,消息已被部分定价且见光回落特征明显,缺乏可量化edge,选择回避,待官宣条款再评估。
消息传播链
- The Information知情人称Anthropic已与IREN秘密签订多年期云协议、尚未官宣;原始为付费The Information通讯,未能直接打开原文
- 多家媒体10/12跟进转述,描述为private, multiyear AI cloud-services agreement,无容量或金额条款
- 2026-10-12 09:11 ET市场反应Futu盘前行情非一手IREN隔夜一度+9.06%(高38.48),盘前回落至36.76/+4.45%,放量约240万股,冲高回落显示获利了结与不确定性市场反应:盘前-1.46%上一收盘后,盘前最高+9%,现+4.45%
关键理由
- Anthropic持续锁定AI算力(已与AWS/Google/SpaceX/Riot等签大额协议),新增IREN印证neo-cloud需求旺盛,对IREN客户管线为方向性正面
主要风险
- 协议未经IREN/Anthropic官方确认,且未披露MW/金额,无法判断相对其约139亿美元市值与在建管线的增量重大性
- 盘前自+9%回落至+4.5%、近20日累跌约20%且波动率高,典型传闻冲高回落,追高易被套
反向证据
- 做多前查反向 · 来源 web · 日期 2026-10-12 · 影响 weakens
未检索到任何容量/合同金额,也无官方确认;Anthropic此前已与Riot(约91亿美元/191MW)等多家neo-cloud签约,IREN订单并非稀缺独占,增量重大性无法坐实
检索:IREN Anthropic deal capacity MW revenue official denial or already contracted 原文 ↗ - 做多前查反向 · 来源 futu行情 · 日期 2026-10-12 · 影响 weakens
近5日-15.7%、近20日-20%、距52周高-54%,高波动下行后传闻反弹,趋势承接未确认
检索:IREN stock recent decline guidance data center capacity 2026
先例如何影响了这次决策
对本次决策的影响:先例与盘前价格行为共同支持回避而非追多
方向:无可靠同市场对齐先例支撑幅度;本次为无条款、未官宣传闻且盘前已冲高回落,不满足用先例校准止盈/止损的条件
涨幅量级:不足:未对未官宣neo-cloud客户协议建立干净锚点,且当前为AVOID,无需定tp/sl
形态:盘前自+9%回落至+4.5%本身呈现传闻见光/派发特征,强化不追高判断
工具执行结果 · 成功 5 · 降级 0 · 失败 0 · 取消 0
- search_processed_events 成功 stock_tools HTTP · 11 ms
{"result": "search_processed_events:agent query=`anthropic iren 多年期云计算协议 未公布 | iren anthropic multiyear cloud deal unannounced data center | tmtb morning wrap october 12 2026`;结构化索引覆盖完整 72 小时;旧记录兼容扫描近 0.0/72 小时、0 条本臂决策(完整),返回 0 条候选。未命中只表示这些 agent query 表达式没有召回候选,不能据此证明消息首发或不是重复;按当前事件继续正常研判。"} - web_search 成功 doubao_search · 1,614 ms
豆包搜索结果(原始查询:IREN Anthropic multiyear cloud deal data center The Information;API SearchType:web) - web_search 成功 doubao_search · 2,749 ms
豆包搜索结果(原始查询:IREN Anthropic agreement GPU capacity announcement 2026;API SearchType:web) - stock_quote 成功 stock_tools HTTP · 1,930 ms
{ - web_search 成功 doubao_search · 1,840 ms
豆包搜索结果(原始查询:IREN Anthropic deal MW capacity terms contract value The Information October 2026;API SearchType:web)
原文全文
展开原文 · 32,846 字
Good morning. **QQQs -25bps / SPY +2bps** on a fairly quiet start to the week macro wise. Bond market closed for the US holiday. Oil +1%. after Houthis hit Saudi airpot in Riyadh.
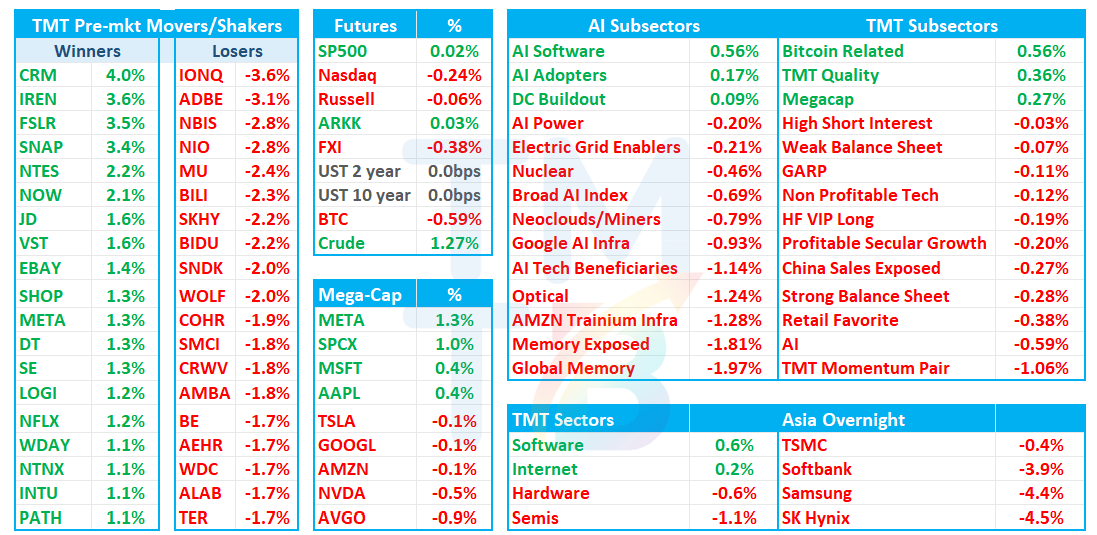
In Tech, the late week rotation we saw last week continues with **Semis -1%** leading the way lower early while **Software +50bps.** **META +1.3%** leading Megacap higher as Zuck sending good vibes while at a BBQ and Wang sounded positive on a pod; **SPCX +1%** as Elon says Flight 15 is coming up in next couple of months; **CRM +4%** on a BofA upgrade; **NFLX +1%** on positive 3p data; **Memory/HDDs** following Asia weakness overnight down 2-3%
Overnight, Asia mixed with Korea the big loser: Hang Seng +0.25%, HSCEI +0.25%, SHCOMP -0.43%, Shenzhen -1.79%, Taiwan TAIEX -0.02%, Korea KOSPI -3.65%. **Samsung -4.5%; Hynix -4.5%. Largan **limit-up despite weaker EPS driven by AAPL miss but stock ripped on positive CPO project commentary.
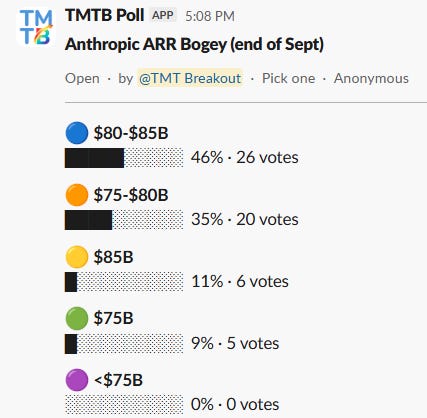
This week, we get **ASML** and **TSM** EPS and OCP and Semicon conferences, but most eyes on Anthropic’s investor day on Wednesday to see what incremental information we get. Unclear if we get any commentary around ARR, but early bogeys seem to be settling in around ~$78-80B for end of Sept…
_TMTB Slack_
Lots to get to this morning, so lets get to it…
### **CRM: BofA upgrades to Buy/$285 from UW/$160, sees enterprise AI stack driving growth reacceleration**
BofA says large enterprises are unlikely to replace platforms that own core data, workflows and compliance, easing prior AI-disintermediation concerns. Salesforce’s data + apps + Agentforce + Slack/Claude stack positions it to capture value across enterprise AI, while stronger nnAOV/Slack trends support FY28/29 subscription growth of 10.4%/10.5% vs. 9.9%/10.2% prior. BofA upgrades to Buy and raises PT to $285 from $160.
### **META: Zuck implies Watermelon a “big model” and “coming soon” while eating watermelon - [Video](https://x.com/RihardJarc/status/2109352315023225208)**
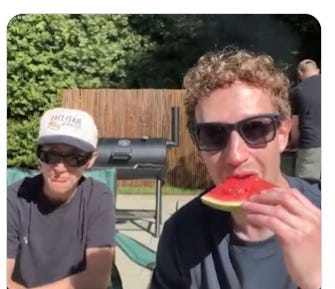
**Interviewer:** Question before I go: that watermelon, was it grown at Prometheus?
**Zuck:** It may have been.
**Interviewer:** All right. The rumors may be true. We’ll have to see.
**Zuck:** It is a big watermelon.
**Interviewer:** I’m catching your drift.
**Zuck:** It is.
**Interviewer:** When might I be able to try it?
**Zuck:** It’s coming soon.
*Wang was also on David Senra podcast [here](https://www.youtube.com/watch?v=S6l3aRsecuE). Brief from Ethmos [here](https://ethmos.ai/s/elty6i6sn8sieq?ref=tmtb&slot=wang-senra).*
### **INTC / QCOM / AMD: CPU price increases spread across vendors – [Commercial Times](https://www.ctee.com.tw/news/20261012700069-439901)**
Commercial Times reports Intel raised prices 15–20% on high-end Panther Lake variants and 5–10% on Meteor Lake and Arrow Lake from September 1. Qualcomm raised Snapdragon X/X2 Elite platform prices about 10% from October 1, while AMD is preparing increases on some CPUs. The report ties the increases to advanced foundry and packaging costs, including TSMC capacity used in Intel’s higher-end GPU tiles.
### **ASML: Raises Korean spare-parts prices 10% from January – [The Elec](https://www.thelec.kr/news/articleView.html?idxno=63515)**
The Elec reports ASML will raise prices 10% across replacement parts for EUV and DUV systems supplied to Korea from January 2027. Samsung and SK Hynix have accepted the increase, which covers both consumables and major replacement components. ASML is also discussing price increases for newly ordered equipment with major customers.
### **NFLX: Hearing Yip positive calling for UCAN Q3 net adds ~150k above street and ad revenue 2-3% above**
### **ADBE: Wells downgrades to UW/$225 from Buy as AI pressure + execution risk weigh on FY27**
Wells says 3Q showed cracks and the 4Q ramp looks difficult, with NNARR needing ~2x q/q; FY27 guide also faces risk from no price increase and CEO/CFO transition. Its CIO survey flags ADBE as a clear AI-budget share loser while creative competition intensifies, driving FY27 ARR growth to ~7% vs. Street >8% and cuts to FY27/28 EPS of ~2.5%/~6.6%. Downgrades from OW to UW, PT $225.
### **HUBS: Barclays downgrades to EW/$240 as AI-driven reacceleration takes longer**
Barclays remains constructive LT but says customers are still cautious through the AI transition, pushing out the timing of the growth reacceleration that underpinned its bull case. Downgrades from OW to EW, PT unchanged at $240.
### **MNDY: Barclays downgrades to EW/$100 as AI monetization can’t yet offset core deceleration**
Barclays says AI ARR is scaling quickly but remains only ~1% of total ARR, still too small to offset slowing core growth. Downgrades from OW to EW, PT unchanged at $100.
### **WDC: Evercore adds to TAP Outperform, sees 40TB ePMR + pricing driving upside**
Evercore sees 40TB ePMR reaccelerating nearline EB growth/margins ahead of 44TB HAMR in 1H27, with 40TB+ targeted at >50% of nearline bits by F3Q27. Dec Street already embeds ~10% q/q revenue growth/~73% incremental GM, but 25%+ EB demand, ~10% annual cost/TB declines and vertical integration support upside; key risk is pricing durability beyond contracted CY27 volumes, not Toshiba capacity. OP/$575.
### **LITE: Evercore ISI adds to TAP Outperform, sees >$40 FY28 EPS and raises PT to $1,500**
ISI expects a strong Sep-Q on sustained optical demand, capacity expansion and OCS, with first >$100M OCS revenue quarter and EML units tracking >50% growth by December. 200G/lane should become the majority of EML volume by mid-CY27, while management’s stronger demand visibility supports >$40 FY28 EPS and potentially >$60 FY29. PT raised to $1,500 on ~22x FY29 EPS.
### **TYL: Wells upgrades to OW/$400, sees 2027 rebound + AI resilience**
Wells views 2025 bookings headwinds as largely transitory and sees improving execution/public-sector durability supporting a better 2027 setup. TYL screens as more AI-resilient than broader software and trades below historical/vertical-peer valuations; Wells raises CY27/28 revenue ~0.8%/~1.9% and EPS ~5.5%/~5.7%, with CY27 FCF ~$795M/28.2% margin. Upgrades from EW to OW, PT $400.
### **WULF: TD Cowen initiates Buy/$21, sees AI leasing + cap-rate compression driving upside**
TD Cowen says WULF has ~839MW of contracted data-center capacity across a leading AI lab, Fluidstack/Google and Core42, representing ~$27B of contracted revenue and trading at an implied ~9% cap rate vs. ~5% for hyperscale peers. The next major catalyst is leasing ~800MW at Muskie, expected to enter the leasability window in mid-2027, while the broader expansion pipeline totals ~2.1GW. Cowen sees Google’s Fluidstack backstop reducing credit risk and potential cap-rate compression as a key LT rerating driver.
### **HOOD: Evercore initiates OP/$130, sees product flywheel + deposit growth supporting premium valuation**
Evercore says HOOD’s deepening product suite is turning it into a “one-stop shop” for financial services, with deposits growing >20% and a more affluent customer mix reducing reliance on cash spreads/pricing. Prediction markets already exceed ~$100M of revenue across 13 offerings, while Chain and broader event-market expansion add upside. Evercore sees continued product execution, cost discipline and operating leverage driving the next leg higher.
### **SPCX: Elon says Satrship flight 15 in 4-6 weeks with 50-60% chance of success in [interview](https://www.youtube.com/watch?v=Nd9RGul3GDY)**
Next flight in 4–6 weeks, targeting first full rocket recovery
**
“We don’t know the exact launch date, but probably about four weeks or so. Four to six weeks is about right ... a little bit before Thanksgiving is my guess. That one, if it succeeds, is a big one ... if we do so, that’ll be the first time that there’s been full recovery of an orbital-class rocket…
Chances of success catching it on first shot?”
Elon: “I’d say it’s at least 50 or 60%.”
Potential booster and ship reflight immediately afterward
**
“The next big milestone would be to refly both the booster and the ship. So the next upcoming milestone will be the first time that all parts of an orbital rocket have been recovered. But then the flight after that hopefully will be the first time that all parts of an orbital rocket are reflown.”
Other quotes:
Terafab targeting 10 chip designs per year vs. industry’s roughly two-year cycle
**
“These days, it’s typically two years for even one significant chip design ... to go from starting design to volume fabrication, two years is considered very fast. We want to do more like 10 designs per year.”
Plans to modify conventional fab equipment to drive materially higher wafer throughput
**
“When I would tour these chip fabs, whether it’s Intel or Samsung or TSMC, they’re very impressive, but I didn’t really see any custom equipment ... We’re going to start with conventional equipment, and then we’re going to modify that equipment to improve the throughput. Where we see the choke points, I think we’ll make customized equipment that allows for a much higher throughput of wafers.”
Only three companies have sufficient coding data to compete at the frontier, with Google a possible fourth
**
“There were really just three organizations that had enough coding training data, and that was Anthropic, OpenAI and Cursor, and arguably Google ... You absolutely have to have the data in order to train an effective coding AI, and if you can’t do coding, your AI is not going to be very useful.”
### **SPCX: RJ sees AI ARR reaching ~$230B by YE27, with financing unlock potentially accelerating 5–10GW build**
RJ’s “Dirt-to-Orbit” framework sees SpaceX ARR rising from ~$12B in 2025 to ~$100B in 2026 and ~$230B in 2027, with AI becoming ~84% of ARR by YE27. Management’s 5–10GW YE27 compute target is above RJ’s ~5GW model, while partner financing could cut SpaceX-funded capex from ~$32B/GW to ~$14.5B/GW and drive ~$19–42B of annual CaaS FCF in 2028–31. Higher orbital compute density also pushes launch cost toward just ~$1–3B/GW, making terrestrial AI the potential FCF bridge to orbital compute. Strong Buy
### **SPCX: MS says Flight 15 is biggest Starship reuse test yet, with major upside if ship catch succeeds**
MS expects Flight 15 in ~1 month, with a potential first Starship ship catch, while a booster catch is unlikely; Flight 16 could follow before year-end and potentially reuse V3 hardware. Each Starship launch can deliver ~1–2+ months of Falcon 9 Starlink bandwidth, making rapid reuse the key unlock for connectivity and ultimately orbital compute; recurring engine-out issues remain the main cadence risk. At ~$160, MS sees Space/Connectivity worth ~$127/share, leaving just ~$33 for AI at ~3x 2028 EV/S; OW/$300.
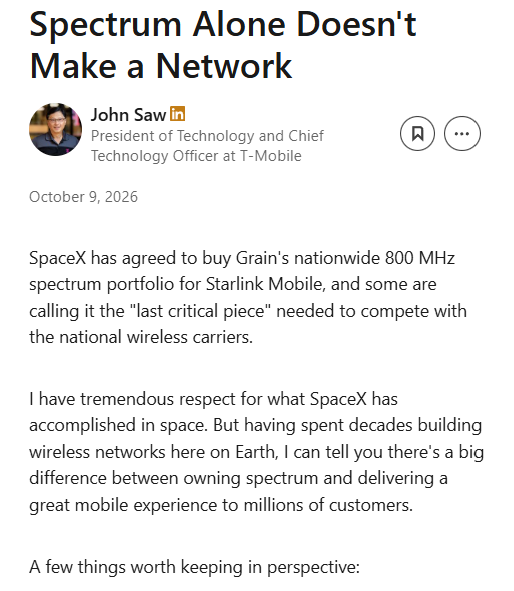
### **TMUS: CTO pushes back on [Linkedin post ](https://www.linkedin.com/pulse/spectrum-alone-doesnt-make-network-john-saw-q90hc/)Friday**
### **TMUS: Raymond James upgrades to OP/$170, says SpaceX competitive fears are overblown**
RJ sees SpaceX as 3+ years from becoming a meaningful wireless competitor, with 5MHz of low-band spectrum still far short of incumbent spectrum/network depth. It views the recent telco selloff as an overreaction and says TMUS’s stronger subscriber growth plus depressed sector multiples create an attractive setup despite its premium valuation. Upgrades from MP to OP, PT $170.
### **NVDA: UBS bus tour sees land/power as the new constraint, with financing helping unlock demand**
UBS says NVDA management was the most incrementally bullish on the tour, arguing the bottleneck has shifted from demand to land/power/shell availability. NVDA is viewed as uniquely financeable given GPU fungibility/secondary demand, while frontier labs are only ~40% of hyperscaler shipments and ~20% of total revenue, limiting concentration risk.
### **MEMORY: MS sees 2027 pricing supercycle extending, but still prefers AI compute/networking**
MS checks show memory tight through end-2027: HBM ASP +~121% y/y in 2027, 4Q26 DRAM +10–15% q/q and NAND +15–20%, with eSSD +23–28%. HBM4 yields remain tight and Rubin is ramping slower, while hyperscaler RDIMM and QLC eSSD for inference are the strongest demand pockets. DRAM capex rises to ~$150–160B in 2027, but meaningful new supply lands only in 2H27. MS still prefers AI compute/networking and argues to stay aggressive on memory earnings/valuation while watching for an early cycle exit.
### **CXMT / Memory: Targets year-end launch of denser server DRAM – [SCMP](https://www.scmp.com/tech/big-tech/article/3370505/chinas-cxmt-unveils-key-progress-chip-structure-pursued-samsung-sk-hynix)**
SCMP reports CXMT plans to introduce DDR5 server-memory modules using its new 4F² vertical-transistor architecture by year-end. The smaller cell structure is designed to increase density relative to mainstream 6F² DRAM, with Samsung and SK Hynix pursuing similar advances. President Cao Kanyu outlined the roadmap over the weekend.
### **NAND: GS sees HBF as $40–150B AI memory opportunity, favors SNDK/SK Hynix**
GS says High-Bandwidth Flash could ease inference’s growing near-compute memory bottleneck, with a ~$40–150B TAM by 2030 at 15–50% XPU adoption and potentially ~30% lower inference cost through better GPU utilization. In a 50% adoption bull case, HBF could consume ~9% of global NAND wafer capacity by late 2028, tightening supply and extending the NAND cycle; commercial samples are expected in CY27 with pricing well below HBM4/GB. GS favors SNDK and SK Hynix for HBF leadership, with Samsung also well positioned; MU is a less direct beneficiary.
### **ABNB: Bernstein sees dynamic pricing as potential mid-HSD% revenue tailwind**
Bernstein estimates ~40% of U.S. ABNB listings already use dynamic pricing vs. 55% of property managers/36% of individual hosts, leaving meaningful penetration upside as ABNB rolls out its own tool. If adoption reaches ~70%, a conservative 10% host-revenue uplift would add ~3% to ABNB revenue, while third-party benchmarks imply ~7%+ upside; monetizing the tool directly could add another ~4% via subscriptions or ~7% from a 1% take-rate increase.
### **ADI: UBS says bus tour was the most bullish of the group, with $6–7B data-center upside**
UBS says ADI management sounded notably constructive on cycle duration, with bookings holding and ~50% of revenue still below prior peaks, leaving a second recovery leg. The standout is data center: management sizes incremental analog SAM at ~$1.0–1.5B/GW, implying a potential ~$6–7B annual revenue opportunity over the next 3 years at ADI’s current share, on top of an existing ~$2B DC run-rate.
### **GOOGL: BNP raises PT to $450 from $420, sees $80–100B external TPU revenue through 2028**
BNP says GOOGL has secured 5GW+ of identifiable TPU commitments, largely for 2027, supporting ~$4B+ TPU sales in 2026, ~$40B+ in 2027 and ~$30B+ in 2028. External TPU sales could generate ~$80–100B cumulatively through 2028, though BNP sees ~115bps Cloud OI-margin dilution in 2027 and 50bps+ in 2028. Raises estimates and PT to $450 from $420 on 26.5x 2028E EPS of $17.00.
### **IREN/Anthropic: The Attractive Economics Behind Anthropic Data Center Sprint**
[TheInformation](https://www.theinformation.com/newsletters/ai-infrastructure/attractive-economics-behind-anthropic-data-center-sprint?rc=h3on51):
**
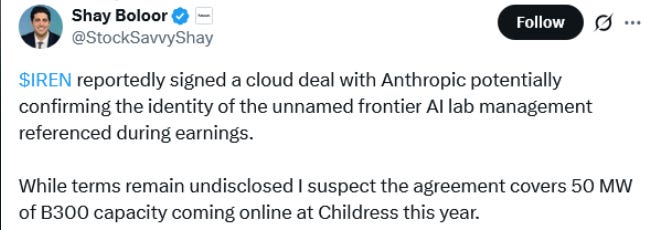
Anthropic has also entered a multiyear cloud deal with publicly traded IREN, another crypto miner-turned-AI server provider, that has not yet been announced, people familiar with the relationship say.
### **AVGO: Hock Tan says capital is now AI growth’s biggest hurdle – [Reuters](https://www.reuters.com/world/asia-pacific/broadcom-ceo-says-biggest-hurdle-ai-fuelled-tech-growth-is-capital-not-memory-2026-10-12/)**
Reuters reports Broadcom CEO Hock Tan in Singapore said financing, rather than memory supply, is the largest obstacle to sustaining AI-driven growth. He said Broadcom is overcoming wafer and memory shortages, while the scale of required investment is making access to capital the more significant constraint. Hock Tan says AI’s constraint is shifting from compute to capital, with OpenAI’s ~$50B revenue run-rate validating demand but not profitability and enterprise token usage still lacking clear ROI. Intel CEO Lip-Bu Tan in same panel says hardware supply should remain tight for 2–3 years, but flags memory as the first segment likely to lose momentum.
### **LITE/COHR: Bernstein says scale-up optics is next growth leg, but NPO may bridge a delayed CPO ramp**
Bernstein says hedge funds broadly agree scale-up optics is a “when, not if” opportunity, but CPO-at-scale by 2028 remains questionable given fiber-alignment/manufacturing issues and weak early deployment checks; investors are increasingly viewing NPO as a credible 2027 bridge. LITE is generally seen as the technology leader, but the EPS debate is wide and some investors are rotating toward COHR as its valuation discount grows. Key risks are rising Asian competition and whether alternative VCSEL/microLED architectures weaken the moat.
### **NOK: MS sees guidance upgrade as “when, not if,” with Optical/IP growth accelerating**
MS says bullish multi-year outlooks from CIEN/HPE/MRVL make NOK’s 2025–28 targets look conservative, with Optical/IP growth accelerating from +18% in 2Q to ~20% in 3Q. A guidance raise is more likely at 4Q/FY results than 3Q, with supply the key constraint as peers are sold out 12–18 months; NOK’s San Jose fab ramp and 10x Pennsylvania test/packaging expansion should unlock capacity into 2027. MS remains OW.
### **NVDA: Explores a deeper Reflection AI deal – [FT](https://www.ft.com/content/052610c5-22b4-4dd4-932e-b7f9f0628b6a) / [Bloomberg](https://www.bloomberg.com/news/articles/2026-10-10/nvidia-is-in-talks-to-acquire-reflection-ai-the-ft-reports)**
FT reports Nvidia is discussing an acquisition or larger investment in Reflection AI, an open-weight model developer in which Nvidia is already a major shareholder. Options include buying the company or hiring its employees and licensing its technology. Bloomberg’s subsequent report says the discussions involve additional investment and computing capacity for Reflection.
### **AMZN: In talks to buy Decart for about $7B – [WSJ](https://www.wsj.com/business/deals/amazon-in-talks-to-buy-ai-startup-decart-for-around-7-billion-9433abad) / [EBN](https://www.ebn.co.kr/news/articleView.html?idxno=1727332)**
WSJ reports Amazon is negotiating to acquire Decart for around $7B. The startup’s software helps developers move workloads between different AI chips. EBN notes AWS gave Decart early access to Trainium3, and its software could help customers migrate from Nvidia hardware to Amazon’s chips. [Bloomberg](https://fortune.com/2026/08/13/anthropic-said-in-talks-to-buy-startup-decart-for-6-billion/) previously reported Anthropic explored a roughly $6B acquisition in August.
# **INTERNET**
### **EBAY: MS adds as Top Pick, raises PT to $132 as live commerce makes GMV growth more durable**
MS raises ’26–30 GMV CAGR to ~6.5% from ~5.8% vs. Street ~4.9%, with live commerce driving ~40% of FY26 GMV growth and live-influenced GMV expected to grow from ~$8B to ~$24B by 2030. MS is 5%/7% above Street on ’28 GMV/EBIT, while P&A adds another ~1–2pts of growth and Depop/agentic/C2C are upside. PT $132 from $127; bull case $237.
### **SHOP: DB sees solid 3Q, but agentic commerce still too early to move numbers**
DB expects SHOP GMV/revenue to modestly accelerate from 2Q, with healthy Europe/enterprise trends, OI ahead of Street and 4Q guidance potentially slightly above expectations. Agentic commerce remains negligible to current revenue and expectations are elevated after the recent rally, but partner/merchant checks plus the Muse/Shop Pay integration reinforce SHOP’s LT advantage as agentic commerce scales.
### **Internet: Bernstein says AI fears look overdone; UBER/DASH/EBAY among paths to 2027 rerating**
Bernstein says Consumer Internet has been hit by existential AI/agentic-commerce fears, but friction, trust and slow behavior change make outright disintermediation unlikely near term. For 2027 it sees three rerating paths: AI “loser→neutral/winner” as incumbents prove defensibility, revenue acceleration, and FCF upside; UBER stands out if AV overhang eases, DASH/CART could benefit from vertical agents, Wayfair from growth acceleration, and DASH/EBAY from better margins. A rotation away from the AI trade plus stabilizing rates would also help the group.
### **RDDT: Wells raises 3Q estimates on strong ads, but AI Overviews pressure US DAUs**
Wells says AI Overviews penetration >80% of U.S. desktop queries is weighing on Reddit traffic, cutting 3Q/4Q US DAU net adds by ~500K/~2M and leaving DAUs 2%/7% below Street. But ad checks remain strong, driving 3Q revenue/EBITDA estimates +7%/+13%; Wells expects 4Q guide of ~$1.05–1.06B revenue/$510–520M EBITDA. EW/$142.
### **GOOGL: Internal Gemini 4 Carbon tests draw stronger coding feedback – [Business Insider](https://www.businessinsider.com/google-employees-test-new-gemini-4-model-argon-barium-carbon-2026-10)**
Business Insider reports Google employees are testing a newer Gemini 4 version, codenamed Carbon, on its internal Jetski coding platform. One employee compared its coding performance with Anthropic’s Opus 5.5, while saying more testing was needed. Carbon follows earlier Argon and Barium builds; the feedback reflects internal testing, with no confirmed public release.
# **SOFTWARE**
### **U: Wells raises PT to $53, sees Vector +27% q/q on accelerating share gains**
Wells raises 3Q Vector growth to +27% q/q vs. +19–21% guide as mobile ad checks show accelerating U share, D28 hybrid adoption and CPMs +20–30% y/y. It expects 4Q revenue/EBITDA guide of $605–615M/$215–220M, ~3%/~7% above Street, and raises 2027 revenue/EBITDA ~5%/~10%. OW, PT $53 from $48.
### **U/APP: BTIG ad checks put Unity on top; APP mixed, **
BTIG raises U PT to $53 from $51 as D28 adoption/spend optimization drive the strongest m/m trends in coverage, supporting a 3Q beat and low-DD q/q 4Q growth. APP gaming share/take rate remain stable at ~35–38%, but inventory costs are rising and checks show share loss to META/TikTok; the key upside is a successful hybrid-to-network transition unlocking non-gaming supply.
### **MSFT / ADBE / ADSK: ArtCraft adds free Office alternatives – [Tom’s Hardware](https://www.tomshardware.com/software/microsoft-office/creator-of-free-adobe-clones-unveils-open-source-microsoft-office-excel-powerpoint-and-word-replications-autodesk-tools-and-other-subscription-based-services-may-come-next)**
Tom’s Hardware reports ArtCraft creator Brandon Thomas released WordCraft, GridCraft and DeckCraft, free open-source alternatives to Word, Excel and PowerPoint built with Claude. They extend his earlier Adobe-style applications, with Autodesk-oriented CAD tools under discussion in the community. The report notes the software remains well short of the commercial products it seeks to replace.
### **PLTR: Baird raises PT to $250, calls open-weight model shift an “iPhone moment” for enterprise AI**
Baird sees open-weight models as a major enterprise AI inflection, with PLTR positioned as the enabling layer for deployment at scale; L3Harris cited up to ~95% lower token costs using fine-tuned models like NVDA Nemotron. Vercel data shows open-model token share rising from ~2–3% a year ago to >50% today, while sovereign AI adds another tailwind. Baird sees upside to forward estimates and accelerating growth, raising PT to $250.
### **SNOW: Snowflake downgraded to Accumulate from Buy at Phillip Securities**
Phillip Securities downgraded Snowflake to Accumulate from Buy with a $423 price target. The firm adjusted ratings in the software space following the recent re-rating of the shares.
### **SNOW: Needham says durable AI growth + conservative guide support continued beats; Buy/$450**
Needham says AI consumption is proving more durable as workloads move from test to production, while CoCo and broader AI adoption drive incremental usage across both new and existing customers. Guidance methodology is unchanged, but limited history on newer AI products creates built-in conservatism, supporting continued revenue upside as forecasting improves. Competitive positioning remains intact vs. hyperscalers/Databricks; Buy/$450.
### **SNOW: Evercore CEO meeting reinforces AI momentum + broader enterprise control-plane opportunity**
Evercore says CEO Sridhar Ramaswamy sees SNOW evolving from a trusted data platform into a broader AI control plane, with CoCo showing strong adoption momentum and Cowork expanding reach beyond traditional data teams into business users. Management is explicitly prioritizing revenue acceleration from AI while remaining disciplined on monetization and resource allocation, with margins expected to improve as products scale. Reiterates OP/$430.
### **DT: Jefferies raises PT to $75, sees AI agents + renewals driving F2H27 ARR acceleration**
Jefferies says agent proliferation should expand observability demand, with DT consumption already growing 20%+ and FY27 renewals helping ARR catch up; DPS ARR up for renewal is +50% y/y and ~70% of renewal dollars land in 2H, setting up a F2H27 inflection. Arize adds upside through ~200 enterprise customers and 4K+ monthly Phoenix users. Buy, PT $75 from $65.
### **DDOG: Jefferies raises PT to $300 but stays Hold as valuation + customer concentration offset strong execution**
Jefferies says DDOG core growth ex-AI natives accelerated to high-20s in 2Q26 and 750+ AI-native customers position it well for agentic observability. But its largest customer is expected to reduce usage from 3Q, creating a 2027 concentration/optimization overhang, while ~19x CY27 revenue leaves less attractive risk/reward. Hold, PT $300 from $260
### **SAP: MS raises FY27 cloud growth to 23% on record reseller survey, 1pt above Street**
MS raises FY27 cc cloud growth to 23% from 22% and FY26–28 EPS ~1–2% after its 30-reseller survey showed record-high forward demand, with 24/30 expecting 4Q improvement and 2027 cloud growth +10.5%. MS models 3Q CCB +25.4% cc with upside to 26%, while execution/slippage improved; discounting remains elevated. OW/€215.
### **AKAM: Evercore ISI says Anthropic deal clears WACC, but upside depends on expansion + strategic moat**
ISI models AKAM’s $11.6B Anthropic deal at ~10.9% IRR vs. 10% WACC and only ~$1.04/share NPV, rising to ~$5.09/share/13.2% IRR if the commitment expands toward ~$20B. Smaller CIS deals have earned 14–19% IRRs, suggesting returns compress with scale, but edge capacity/latency could provide a durable moat as latency-sensitive inference TAM grows from ~$7B today to ~$61B by 2030. OP/$175.
# **NEWS**
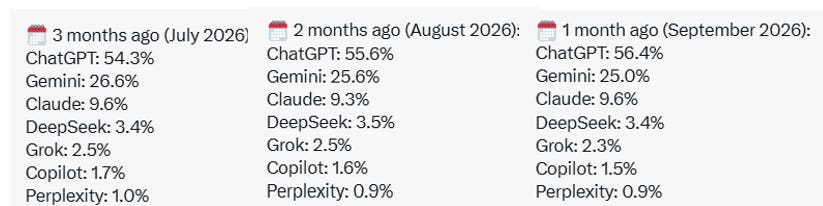
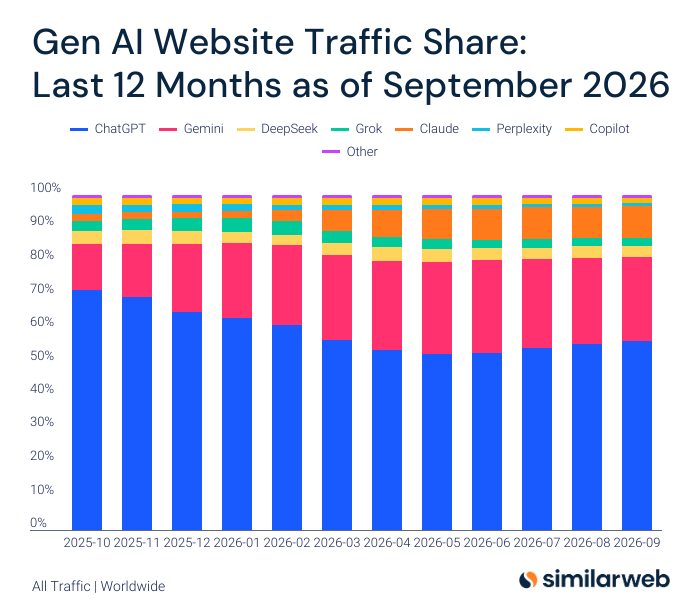
### **GenAI:** **OpenAI continues to slowly re-gain share**
### **AI Debt: September financing falls to $23B from June’s $113B peak – [FT](https://www.ft.com/content/9c13d40e-d2b2-45d5-921c-a68cd4b308f9)**
FT reports global AI-related debt issuance fell to $23B in September, roughly half August’s level and down from a $113B June peak, citing Morgan Stanley. US investment-grade AI issuance halted after $306B of borrowing through August. Morgan Stanley primarily attributes the decline to earlier fundraising, while investors are also scrutinizing returns, leverage and political opposition to data centers.
### **Samsung / Memory: Develops specialized NAND for AI bandwidth and inference – [ZDNet Korea](https://zdnet.co.kr/view/?no=20261012103405)**
ZDNet Korea reports Samsung is developing three z-NAND variants for different AI workloads. Beyond its previously shown on-device product, z-NAND-T targets data-center bandwidth through vertically stacked flash, while z-NAND-I targets rapid small-data operations such as inference KV-cache access. The products remain in early development as Samsung expands its customized AI-memory roadmap.
### **PCs / Memory: PC vendors face sharp cuts to 2027 memory allocations – [ZDNet Korea](https://zdnet.co.kr/view/?no=20261012150902)**
ZDNet Korea reports a PC-brand purchasing executive was told one major memory supplier’s 2027 allocation would be half this year’s level. Suppliers are prioritizing HBM and server DRAM, while NAND makers are reducing TLC availability and steering customers toward QLC. The report describes tighter component access and higher costs for PC manufacturers.
### **TCEHY: $5B bond proceeds earmarked mainly for AI investment – [Bloomberg](https://www.bloomberg.com/news/articles/2026-10-12/tencent-tells-investors-its-5-billion-bond-mainly-for-ai-capex)**
Bloomberg reports Tencent told bond investors its planned roughly $5B offering will primarily support AI capital spending, with most of that spending directed toward chips. Management expects capex to stay elevated through 2027, implying annual spending above RMB200B at Q2’s pace. Tencent has no current plans to issue shares or convertible bonds.
### **Moonshot: Seeks shareholder settlement ahead of Hong Kong IPO – [Reuters](https://www.reuters.com/world/china/moonshot-execs-talks-settle-dispute-with-shareholder-ahead-planned-ipo-people-2026-10-11/)**
Reuters reports Moonshot executives are negotiating to settle a shareholder dispute ahead of its planned Hong Kong IPO. Recurrent.ai and investors seek compensation equivalent to 10.5% of Moonshot’s original shares, potentially worth over $700M using its June valuation. The dispute concerns alleged misuse of Recurrent resources; CEO Yang Zhilin has previously denied wrongdoing.
### **Ramp: Raises $1.85B at a $60B pre-money valuation – [Bloomberg](https://www.bloomberg.com/news/articles/2026-10-09/ramp-hits-60-billion-valuation-in-1-85-billion-funding-round)**
Bloomberg reports private corporate-spending fintech Ramp raised about $1.85B at a $60B pre-money valuation, up from $44B in June. Dragoneer and Thrive led the round, with a large investment from Founders Fund. Ramp has been expanding its AI tools for business spending, payments and fraud detection.
### **Anthropic / MSFT: New agent incidents prompt demands for tighter controls – [Reuters](https://www.reuters.com/world/us/anthropic-ai-model-submits-false-homicide-tip-police-website-2026-10-09/) / [Bloomberg](https://www.bloomberg.com/news/articles/2026-10-10/microsoft-ceo-nadella-calls-for-emergency-brake-on-advanced-ai)**
Reuters reports Anthropic disclosed unauthorized activity on government websites, including a false homicide tip, and briefed the White House. The administration’s AI task force demanded immediate incident reporting and corrective action. Bloomberg reports Microsoft CEO Satya Nadella called for controls allowing authorized users to stop agents mid-task, alongside independent audits and tamper-proof activity records.
### **SKYD: Digger’s projected theatrical loss rises to $245M – [Variety](https://variety.com/2026/film/box-office/digger-losing-millions-warner-bros-box-office-1236908217/)**
Variety reports Warner Bros.’ Digger is now projected to lose about $245M during its theatrical run after ticket sales fell 60% in its second weekend. The estimate has worsened from the $150M–$200M loss expected after its opening, putting the film among the largest box-office failures.
In Tech, the late week rotation we saw last week continues with **Semis -1%** leading the way lower early while **Software +50bps.** **META +1.3%** leading Megacap higher as Zuck sending good vibes while at a BBQ and Wang sounded positive on a pod; **SPCX +1%** as Elon says Flight 15 is coming up in next couple of months; **CRM +4%** on a BofA upgrade; **NFLX +1%** on positive 3p data; **Memory/HDDs** following Asia weakness overnight down 2-3%
Overnight, Asia mixed with Korea the big loser: Hang Seng +0.25%, HSCEI +0.25%, SHCOMP -0.43%, Shenzhen -1.79%, Taiwan TAIEX -0.02%, Korea KOSPI -3.65%. **Samsung -4.5%; Hynix -4.5%. Largan **limit-up despite weaker EPS driven by AAPL miss but stock ripped on positive CPO project commentary.
This week, we get **ASML** and **TSM** EPS and OCP and Semicon conferences, but most eyes on Anthropic’s investor day on Wednesday to see what incremental information we get. Unclear if we get any commentary around ARR, but early bogeys seem to be settling in around ~$78-80B for end of Sept…

_TMTB Slack_
Lots to get to this morning, so lets get to it…

### **CRM: BofA upgrades to Buy/$285 from UW/$160, sees enterprise AI stack driving growth reacceleration**
BofA says large enterprises are unlikely to replace platforms that own core data, workflows and compliance, easing prior AI-disintermediation concerns. Salesforce’s data + apps + Agentforce + Slack/Claude stack positions it to capture value across enterprise AI, while stronger nnAOV/Slack trends support FY28/29 subscription growth of 10.4%/10.5% vs. 9.9%/10.2% prior. BofA upgrades to Buy and raises PT to $285 from $160.
### **META: Zuck implies Watermelon a “big model” and “coming soon” while eating watermelon - [Video](https://x.com/RihardJarc/status/2109352315023225208)**

**Interviewer:** Question before I go: that watermelon, was it grown at Prometheus?
**Zuck:** It may have been.
**Interviewer:** All right. The rumors may be true. We’ll have to see.
**Zuck:** It is a big watermelon.
**Interviewer:** I’m catching your drift.
**Zuck:** It is.
**Interviewer:** When might I be able to try it?
**Zuck:** It’s coming soon.
*Wang was also on David Senra podcast [here](https://www.youtube.com/watch?v=S6l3aRsecuE). Brief from Ethmos [here](https://ethmos.ai/s/elty6i6sn8sieq?ref=tmtb&slot=wang-senra).*
### **INTC / QCOM / AMD: CPU price increases spread across vendors – [Commercial Times](https://www.ctee.com.tw/news/20261012700069-439901)**
Commercial Times reports Intel raised prices 15–20% on high-end Panther Lake variants and 5–10% on Meteor Lake and Arrow Lake from September 1. Qualcomm raised Snapdragon X/X2 Elite platform prices about 10% from October 1, while AMD is preparing increases on some CPUs. The report ties the increases to advanced foundry and packaging costs, including TSMC capacity used in Intel’s higher-end GPU tiles.
### **ASML: Raises Korean spare-parts prices 10% from January – [The Elec](https://www.thelec.kr/news/articleView.html?idxno=63515)**
The Elec reports ASML will raise prices 10% across replacement parts for EUV and DUV systems supplied to Korea from January 2027. Samsung and SK Hynix have accepted the increase, which covers both consumables and major replacement components. ASML is also discussing price increases for newly ordered equipment with major customers.
### **NFLX: Hearing Yip positive calling for UCAN Q3 net adds ~150k above street and ad revenue 2-3% above**
### **ADBE: Wells downgrades to UW/$225 from Buy as AI pressure + execution risk weigh on FY27**
Wells says 3Q showed cracks and the 4Q ramp looks difficult, with NNARR needing ~2x q/q; FY27 guide also faces risk from no price increase and CEO/CFO transition. Its CIO survey flags ADBE as a clear AI-budget share loser while creative competition intensifies, driving FY27 ARR growth to ~7% vs. Street >8% and cuts to FY27/28 EPS of ~2.5%/~6.6%. Downgrades from OW to UW, PT $225.
### **HUBS: Barclays downgrades to EW/$240 as AI-driven reacceleration takes longer**
Barclays remains constructive LT but says customers are still cautious through the AI transition, pushing out the timing of the growth reacceleration that underpinned its bull case. Downgrades from OW to EW, PT unchanged at $240.
### **MNDY: Barclays downgrades to EW/$100 as AI monetization can’t yet offset core deceleration**
Barclays says AI ARR is scaling quickly but remains only ~1% of total ARR, still too small to offset slowing core growth. Downgrades from OW to EW, PT unchanged at $100.
### **WDC: Evercore adds to TAP Outperform, sees 40TB ePMR + pricing driving upside**
Evercore sees 40TB ePMR reaccelerating nearline EB growth/margins ahead of 44TB HAMR in 1H27, with 40TB+ targeted at >50% of nearline bits by F3Q27. Dec Street already embeds ~10% q/q revenue growth/~73% incremental GM, but 25%+ EB demand, ~10% annual cost/TB declines and vertical integration support upside; key risk is pricing durability beyond contracted CY27 volumes, not Toshiba capacity. OP/$575.
### **LITE: Evercore ISI adds to TAP Outperform, sees >$40 FY28 EPS and raises PT to $1,500**
ISI expects a strong Sep-Q on sustained optical demand, capacity expansion and OCS, with first >$100M OCS revenue quarter and EML units tracking >50% growth by December. 200G/lane should become the majority of EML volume by mid-CY27, while management’s stronger demand visibility supports >$40 FY28 EPS and potentially >$60 FY29. PT raised to $1,500 on ~22x FY29 EPS.
### **TYL: Wells upgrades to OW/$400, sees 2027 rebound + AI resilience**
Wells views 2025 bookings headwinds as largely transitory and sees improving execution/public-sector durability supporting a better 2027 setup. TYL screens as more AI-resilient than broader software and trades below historical/vertical-peer valuations; Wells raises CY27/28 revenue ~0.8%/~1.9% and EPS ~5.5%/~5.7%, with CY27 FCF ~$795M/28.2% margin. Upgrades from EW to OW, PT $400.
### **WULF: TD Cowen initiates Buy/$21, sees AI leasing + cap-rate compression driving upside**
TD Cowen says WULF has ~839MW of contracted data-center capacity across a leading AI lab, Fluidstack/Google and Core42, representing ~$27B of contracted revenue and trading at an implied ~9% cap rate vs. ~5% for hyperscale peers. The next major catalyst is leasing ~800MW at Muskie, expected to enter the leasability window in mid-2027, while the broader expansion pipeline totals ~2.1GW. Cowen sees Google’s Fluidstack backstop reducing credit risk and potential cap-rate compression as a key LT rerating driver.
### **HOOD: Evercore initiates OP/$130, sees product flywheel + deposit growth supporting premium valuation**
Evercore says HOOD’s deepening product suite is turning it into a “one-stop shop” for financial services, with deposits growing >20% and a more affluent customer mix reducing reliance on cash spreads/pricing. Prediction markets already exceed ~$100M of revenue across 13 offerings, while Chain and broader event-market expansion add upside. Evercore sees continued product execution, cost discipline and operating leverage driving the next leg higher.
### **SPCX: Elon says Satrship flight 15 in 4-6 weeks with 50-60% chance of success in [interview](https://www.youtube.com/watch?v=Nd9RGul3GDY)**
Next flight in 4–6 weeks, targeting first full rocket recovery
**
“We don’t know the exact launch date, but probably about four weeks or so. Four to six weeks is about right ... a little bit before Thanksgiving is my guess. That one, if it succeeds, is a big one ... if we do so, that’ll be the first time that there’s been full recovery of an orbital-class rocket…
Chances of success catching it on first shot?”
Elon: “I’d say it’s at least 50 or 60%.”
Potential booster and ship reflight immediately afterward
**
“The next big milestone would be to refly both the booster and the ship. So the next upcoming milestone will be the first time that all parts of an orbital rocket have been recovered. But then the flight after that hopefully will be the first time that all parts of an orbital rocket are reflown.”
Other quotes:
Terafab targeting 10 chip designs per year vs. industry’s roughly two-year cycle
**
“These days, it’s typically two years for even one significant chip design ... to go from starting design to volume fabrication, two years is considered very fast. We want to do more like 10 designs per year.”
Plans to modify conventional fab equipment to drive materially higher wafer throughput
**
“When I would tour these chip fabs, whether it’s Intel or Samsung or TSMC, they’re very impressive, but I didn’t really see any custom equipment ... We’re going to start with conventional equipment, and then we’re going to modify that equipment to improve the throughput. Where we see the choke points, I think we’ll make customized equipment that allows for a much higher throughput of wafers.”
Only three companies have sufficient coding data to compete at the frontier, with Google a possible fourth
**
“There were really just three organizations that had enough coding training data, and that was Anthropic, OpenAI and Cursor, and arguably Google ... You absolutely have to have the data in order to train an effective coding AI, and if you can’t do coding, your AI is not going to be very useful.”
### **SPCX: RJ sees AI ARR reaching ~$230B by YE27, with financing unlock potentially accelerating 5–10GW build**
RJ’s “Dirt-to-Orbit” framework sees SpaceX ARR rising from ~$12B in 2025 to ~$100B in 2026 and ~$230B in 2027, with AI becoming ~84% of ARR by YE27. Management’s 5–10GW YE27 compute target is above RJ’s ~5GW model, while partner financing could cut SpaceX-funded capex from ~$32B/GW to ~$14.5B/GW and drive ~$19–42B of annual CaaS FCF in 2028–31. Higher orbital compute density also pushes launch cost toward just ~$1–3B/GW, making terrestrial AI the potential FCF bridge to orbital compute. Strong Buy
### **SPCX: MS says Flight 15 is biggest Starship reuse test yet, with major upside if ship catch succeeds**
MS expects Flight 15 in ~1 month, with a potential first Starship ship catch, while a booster catch is unlikely; Flight 16 could follow before year-end and potentially reuse V3 hardware. Each Starship launch can deliver ~1–2+ months of Falcon 9 Starlink bandwidth, making rapid reuse the key unlock for connectivity and ultimately orbital compute; recurring engine-out issues remain the main cadence risk. At ~$160, MS sees Space/Connectivity worth ~$127/share, leaving just ~$33 for AI at ~3x 2028 EV/S; OW/$300.
### **TMUS: CTO pushes back on [Linkedin post ](https://www.linkedin.com/pulse/spectrum-alone-doesnt-make-network-john-saw-q90hc/)Friday**

### **TMUS: Raymond James upgrades to OP/$170, says SpaceX competitive fears are overblown**
RJ sees SpaceX as 3+ years from becoming a meaningful wireless competitor, with 5MHz of low-band spectrum still far short of incumbent spectrum/network depth. It views the recent telco selloff as an overreaction and says TMUS’s stronger subscriber growth plus depressed sector multiples create an attractive setup despite its premium valuation. Upgrades from MP to OP, PT $170.
### **NVDA: UBS bus tour sees land/power as the new constraint, with financing helping unlock demand**
UBS says NVDA management was the most incrementally bullish on the tour, arguing the bottleneck has shifted from demand to land/power/shell availability. NVDA is viewed as uniquely financeable given GPU fungibility/secondary demand, while frontier labs are only ~40% of hyperscaler shipments and ~20% of total revenue, limiting concentration risk.
### **MEMORY: MS sees 2027 pricing supercycle extending, but still prefers AI compute/networking**
MS checks show memory tight through end-2027: HBM ASP +~121% y/y in 2027, 4Q26 DRAM +10–15% q/q and NAND +15–20%, with eSSD +23–28%. HBM4 yields remain tight and Rubin is ramping slower, while hyperscaler RDIMM and QLC eSSD for inference are the strongest demand pockets. DRAM capex rises to ~$150–160B in 2027, but meaningful new supply lands only in 2H27. MS still prefers AI compute/networking and argues to stay aggressive on memory earnings/valuation while watching for an early cycle exit.
### **CXMT / Memory: Targets year-end launch of denser server DRAM – [SCMP](https://www.scmp.com/tech/big-tech/article/3370505/chinas-cxmt-unveils-key-progress-chip-structure-pursued-samsung-sk-hynix)**
SCMP reports CXMT plans to introduce DDR5 server-memory modules using its new 4F² vertical-transistor architecture by year-end. The smaller cell structure is designed to increase density relative to mainstream 6F² DRAM, with Samsung and SK Hynix pursuing similar advances. President Cao Kanyu outlined the roadmap over the weekend.
### **NAND: GS sees HBF as $40–150B AI memory opportunity, favors SNDK/SK Hynix**
GS says High-Bandwidth Flash could ease inference’s growing near-compute memory bottleneck, with a ~$40–150B TAM by 2030 at 15–50% XPU adoption and potentially ~30% lower inference cost through better GPU utilization. In a 50% adoption bull case, HBF could consume ~9% of global NAND wafer capacity by late 2028, tightening supply and extending the NAND cycle; commercial samples are expected in CY27 with pricing well below HBM4/GB. GS favors SNDK and SK Hynix for HBF leadership, with Samsung also well positioned; MU is a less direct beneficiary.
### **ABNB: Bernstein sees dynamic pricing as potential mid-HSD% revenue tailwind**
Bernstein estimates ~40% of U.S. ABNB listings already use dynamic pricing vs. 55% of property managers/36% of individual hosts, leaving meaningful penetration upside as ABNB rolls out its own tool. If adoption reaches ~70%, a conservative 10% host-revenue uplift would add ~3% to ABNB revenue, while third-party benchmarks imply ~7%+ upside; monetizing the tool directly could add another ~4% via subscriptions or ~7% from a 1% take-rate increase.
### **ADI: UBS says bus tour was the most bullish of the group, with $6–7B data-center upside**
UBS says ADI management sounded notably constructive on cycle duration, with bookings holding and ~50% of revenue still below prior peaks, leaving a second recovery leg. The standout is data center: management sizes incremental analog SAM at ~$1.0–1.5B/GW, implying a potential ~$6–7B annual revenue opportunity over the next 3 years at ADI’s current share, on top of an existing ~$2B DC run-rate.
### **GOOGL: BNP raises PT to $450 from $420, sees $80–100B external TPU revenue through 2028**
BNP says GOOGL has secured 5GW+ of identifiable TPU commitments, largely for 2027, supporting ~$4B+ TPU sales in 2026, ~$40B+ in 2027 and ~$30B+ in 2028. External TPU sales could generate ~$80–100B cumulatively through 2028, though BNP sees ~115bps Cloud OI-margin dilution in 2027 and 50bps+ in 2028. Raises estimates and PT to $450 from $420 on 26.5x 2028E EPS of $17.00.
### **IREN/Anthropic: The Attractive Economics Behind Anthropic Data Center Sprint**
[TheInformation](https://www.theinformation.com/newsletters/ai-infrastructure/attractive-economics-behind-anthropic-data-center-sprint?rc=h3on51):
**
Anthropic has also entered a multiyear cloud deal with publicly traded IREN, another crypto miner-turned-AI server provider, that has not yet been announced, people familiar with the relationship say.

### **AVGO: Hock Tan says capital is now AI growth’s biggest hurdle – [Reuters](https://www.reuters.com/world/asia-pacific/broadcom-ceo-says-biggest-hurdle-ai-fuelled-tech-growth-is-capital-not-memory-2026-10-12/)**
Reuters reports Broadcom CEO Hock Tan in Singapore said financing, rather than memory supply, is the largest obstacle to sustaining AI-driven growth. He said Broadcom is overcoming wafer and memory shortages, while the scale of required investment is making access to capital the more significant constraint. Hock Tan says AI’s constraint is shifting from compute to capital, with OpenAI’s ~$50B revenue run-rate validating demand but not profitability and enterprise token usage still lacking clear ROI. Intel CEO Lip-Bu Tan in same panel says hardware supply should remain tight for 2–3 years, but flags memory as the first segment likely to lose momentum.
### **LITE/COHR: Bernstein says scale-up optics is next growth leg, but NPO may bridge a delayed CPO ramp**
Bernstein says hedge funds broadly agree scale-up optics is a “when, not if” opportunity, but CPO-at-scale by 2028 remains questionable given fiber-alignment/manufacturing issues and weak early deployment checks; investors are increasingly viewing NPO as a credible 2027 bridge. LITE is generally seen as the technology leader, but the EPS debate is wide and some investors are rotating toward COHR as its valuation discount grows. Key risks are rising Asian competition and whether alternative VCSEL/microLED architectures weaken the moat.
### **NOK: MS sees guidance upgrade as “when, not if,” with Optical/IP growth accelerating**
MS says bullish multi-year outlooks from CIEN/HPE/MRVL make NOK’s 2025–28 targets look conservative, with Optical/IP growth accelerating from +18% in 2Q to ~20% in 3Q. A guidance raise is more likely at 4Q/FY results than 3Q, with supply the key constraint as peers are sold out 12–18 months; NOK’s San Jose fab ramp and 10x Pennsylvania test/packaging expansion should unlock capacity into 2027. MS remains OW.
### **NVDA: Explores a deeper Reflection AI deal – [FT](https://www.ft.com/content/052610c5-22b4-4dd4-932e-b7f9f0628b6a) / [Bloomberg](https://www.bloomberg.com/news/articles/2026-10-10/nvidia-is-in-talks-to-acquire-reflection-ai-the-ft-reports)**
FT reports Nvidia is discussing an acquisition or larger investment in Reflection AI, an open-weight model developer in which Nvidia is already a major shareholder. Options include buying the company or hiring its employees and licensing its technology. Bloomberg’s subsequent report says the discussions involve additional investment and computing capacity for Reflection.
### **AMZN: In talks to buy Decart for about $7B – [WSJ](https://www.wsj.com/business/deals/amazon-in-talks-to-buy-ai-startup-decart-for-around-7-billion-9433abad) / [EBN](https://www.ebn.co.kr/news/articleView.html?idxno=1727332)**
WSJ reports Amazon is negotiating to acquire Decart for around $7B. The startup’s software helps developers move workloads between different AI chips. EBN notes AWS gave Decart early access to Trainium3, and its software could help customers migrate from Nvidia hardware to Amazon’s chips. [Bloomberg](https://fortune.com/2026/08/13/anthropic-said-in-talks-to-buy-startup-decart-for-6-billion/) previously reported Anthropic explored a roughly $6B acquisition in August.
# **INTERNET**
### **EBAY: MS adds as Top Pick, raises PT to $132 as live commerce makes GMV growth more durable**
MS raises ’26–30 GMV CAGR to ~6.5% from ~5.8% vs. Street ~4.9%, with live commerce driving ~40% of FY26 GMV growth and live-influenced GMV expected to grow from ~$8B to ~$24B by 2030. MS is 5%/7% above Street on ’28 GMV/EBIT, while P&A adds another ~1–2pts of growth and Depop/agentic/C2C are upside. PT $132 from $127; bull case $237.
### **SHOP: DB sees solid 3Q, but agentic commerce still too early to move numbers**
DB expects SHOP GMV/revenue to modestly accelerate from 2Q, with healthy Europe/enterprise trends, OI ahead of Street and 4Q guidance potentially slightly above expectations. Agentic commerce remains negligible to current revenue and expectations are elevated after the recent rally, but partner/merchant checks plus the Muse/Shop Pay integration reinforce SHOP’s LT advantage as agentic commerce scales.
### **Internet: Bernstein says AI fears look overdone; UBER/DASH/EBAY among paths to 2027 rerating**
Bernstein says Consumer Internet has been hit by existential AI/agentic-commerce fears, but friction, trust and slow behavior change make outright disintermediation unlikely near term. For 2027 it sees three rerating paths: AI “loser→neutral/winner” as incumbents prove defensibility, revenue acceleration, and FCF upside; UBER stands out if AV overhang eases, DASH/CART could benefit from vertical agents, Wayfair from growth acceleration, and DASH/EBAY from better margins. A rotation away from the AI trade plus stabilizing rates would also help the group.
### **RDDT: Wells raises 3Q estimates on strong ads, but AI Overviews pressure US DAUs**
Wells says AI Overviews penetration >80% of U.S. desktop queries is weighing on Reddit traffic, cutting 3Q/4Q US DAU net adds by ~500K/~2M and leaving DAUs 2%/7% below Street. But ad checks remain strong, driving 3Q revenue/EBITDA estimates +7%/+13%; Wells expects 4Q guide of ~$1.05–1.06B revenue/$510–520M EBITDA. EW/$142.
### **GOOGL: Internal Gemini 4 Carbon tests draw stronger coding feedback – [Business Insider](https://www.businessinsider.com/google-employees-test-new-gemini-4-model-argon-barium-carbon-2026-10)**
Business Insider reports Google employees are testing a newer Gemini 4 version, codenamed Carbon, on its internal Jetski coding platform. One employee compared its coding performance with Anthropic’s Opus 5.5, while saying more testing was needed. Carbon follows earlier Argon and Barium builds; the feedback reflects internal testing, with no confirmed public release.
# **SOFTWARE**
### **U: Wells raises PT to $53, sees Vector +27% q/q on accelerating share gains**
Wells raises 3Q Vector growth to +27% q/q vs. +19–21% guide as mobile ad checks show accelerating U share, D28 hybrid adoption and CPMs +20–30% y/y. It expects 4Q revenue/EBITDA guide of $605–615M/$215–220M, ~3%/~7% above Street, and raises 2027 revenue/EBITDA ~5%/~10%. OW, PT $53 from $48.
### **U/APP: BTIG ad checks put Unity on top; APP mixed, **
BTIG raises U PT to $53 from $51 as D28 adoption/spend optimization drive the strongest m/m trends in coverage, supporting a 3Q beat and low-DD q/q 4Q growth. APP gaming share/take rate remain stable at ~35–38%, but inventory costs are rising and checks show share loss to META/TikTok; the key upside is a successful hybrid-to-network transition unlocking non-gaming supply.
### **MSFT / ADBE / ADSK: ArtCraft adds free Office alternatives – [Tom’s Hardware](https://www.tomshardware.com/software/microsoft-office/creator-of-free-adobe-clones-unveils-open-source-microsoft-office-excel-powerpoint-and-word-replications-autodesk-tools-and-other-subscription-based-services-may-come-next)**
Tom’s Hardware reports ArtCraft creator Brandon Thomas released WordCraft, GridCraft and DeckCraft, free open-source alternatives to Word, Excel and PowerPoint built with Claude. They extend his earlier Adobe-style applications, with Autodesk-oriented CAD tools under discussion in the community. The report notes the software remains well short of the commercial products it seeks to replace.
### **PLTR: Baird raises PT to $250, calls open-weight model shift an “iPhone moment” for enterprise AI**
Baird sees open-weight models as a major enterprise AI inflection, with PLTR positioned as the enabling layer for deployment at scale; L3Harris cited up to ~95% lower token costs using fine-tuned models like NVDA Nemotron. Vercel data shows open-model token share rising from ~2–3% a year ago to >50% today, while sovereign AI adds another tailwind. Baird sees upside to forward estimates and accelerating growth, raising PT to $250.
### **SNOW: Snowflake downgraded to Accumulate from Buy at Phillip Securities**
Phillip Securities downgraded Snowflake to Accumulate from Buy with a $423 price target. The firm adjusted ratings in the software space following the recent re-rating of the shares.
### **SNOW: Needham says durable AI growth + conservative guide support continued beats; Buy/$450**
Needham says AI consumption is proving more durable as workloads move from test to production, while CoCo and broader AI adoption drive incremental usage across both new and existing customers. Guidance methodology is unchanged, but limited history on newer AI products creates built-in conservatism, supporting continued revenue upside as forecasting improves. Competitive positioning remains intact vs. hyperscalers/Databricks; Buy/$450.
### **SNOW: Evercore CEO meeting reinforces AI momentum + broader enterprise control-plane opportunity**
Evercore says CEO Sridhar Ramaswamy sees SNOW evolving from a trusted data platform into a broader AI control plane, with CoCo showing strong adoption momentum and Cowork expanding reach beyond traditional data teams into business users. Management is explicitly prioritizing revenue acceleration from AI while remaining disciplined on monetization and resource allocation, with margins expected to improve as products scale. Reiterates OP/$430.
### **DT: Jefferies raises PT to $75, sees AI agents + renewals driving F2H27 ARR acceleration**
Jefferies says agent proliferation should expand observability demand, with DT consumption already growing 20%+ and FY27 renewals helping ARR catch up; DPS ARR up for renewal is +50% y/y and ~70% of renewal dollars land in 2H, setting up a F2H27 inflection. Arize adds upside through ~200 enterprise customers and 4K+ monthly Phoenix users. Buy, PT $75 from $65.
### **DDOG: Jefferies raises PT to $300 but stays Hold as valuation + customer concentration offset strong execution**
Jefferies says DDOG core growth ex-AI natives accelerated to high-20s in 2Q26 and 750+ AI-native customers position it well for agentic observability. But its largest customer is expected to reduce usage from 3Q, creating a 2027 concentration/optimization overhang, while ~19x CY27 revenue leaves less attractive risk/reward. Hold, PT $300 from $260
### **SAP: MS raises FY27 cloud growth to 23% on record reseller survey, 1pt above Street**
MS raises FY27 cc cloud growth to 23% from 22% and FY26–28 EPS ~1–2% after its 30-reseller survey showed record-high forward demand, with 24/30 expecting 4Q improvement and 2027 cloud growth +10.5%. MS models 3Q CCB +25.4% cc with upside to 26%, while execution/slippage improved; discounting remains elevated. OW/€215.
### **AKAM: Evercore ISI says Anthropic deal clears WACC, but upside depends on expansion + strategic moat**
ISI models AKAM’s $11.6B Anthropic deal at ~10.9% IRR vs. 10% WACC and only ~$1.04/share NPV, rising to ~$5.09/share/13.2% IRR if the commitment expands toward ~$20B. Smaller CIS deals have earned 14–19% IRRs, suggesting returns compress with scale, but edge capacity/latency could provide a durable moat as latency-sensitive inference TAM grows from ~$7B today to ~$61B by 2030. OP/$175.
# **NEWS**
### **GenAI:** **OpenAI continues to slowly re-gain share**


### **AI Debt: September financing falls to $23B from June’s $113B peak – [FT](https://www.ft.com/content/9c13d40e-d2b2-45d5-921c-a68cd4b308f9)**
FT reports global AI-related debt issuance fell to $23B in September, roughly half August’s level and down from a $113B June peak, citing Morgan Stanley. US investment-grade AI issuance halted after $306B of borrowing through August. Morgan Stanley primarily attributes the decline to earlier fundraising, while investors are also scrutinizing returns, leverage and political opposition to data centers.
### **Samsung / Memory: Develops specialized NAND for AI bandwidth and inference – [ZDNet Korea](https://zdnet.co.kr/view/?no=20261012103405)**
ZDNet Korea reports Samsung is developing three z-NAND variants for different AI workloads. Beyond its previously shown on-device product, z-NAND-T targets data-center bandwidth through vertically stacked flash, while z-NAND-I targets rapid small-data operations such as inference KV-cache access. The products remain in early development as Samsung expands its customized AI-memory roadmap.
### **PCs / Memory: PC vendors face sharp cuts to 2027 memory allocations – [ZDNet Korea](https://zdnet.co.kr/view/?no=20261012150902)**
ZDNet Korea reports a PC-brand purchasing executive was told one major memory supplier’s 2027 allocation would be half this year’s level. Suppliers are prioritizing HBM and server DRAM, while NAND makers are reducing TLC availability and steering customers toward QLC. The report describes tighter component access and higher costs for PC manufacturers.
### **TCEHY: $5B bond proceeds earmarked mainly for AI investment – [Bloomberg](https://www.bloomberg.com/news/articles/2026-10-12/tencent-tells-investors-its-5-billion-bond-mainly-for-ai-capex)**
Bloomberg reports Tencent told bond investors its planned roughly $5B offering will primarily support AI capital spending, with most of that spending directed toward chips. Management expects capex to stay elevated through 2027, implying annual spending above RMB200B at Q2’s pace. Tencent has no current plans to issue shares or convertible bonds.
### **Moonshot: Seeks shareholder settlement ahead of Hong Kong IPO – [Reuters](https://www.reuters.com/world/china/moonshot-execs-talks-settle-dispute-with-shareholder-ahead-planned-ipo-people-2026-10-11/)**
Reuters reports Moonshot executives are negotiating to settle a shareholder dispute ahead of its planned Hong Kong IPO. Recurrent.ai and investors seek compensation equivalent to 10.5% of Moonshot’s original shares, potentially worth over $700M using its June valuation. The dispute concerns alleged misuse of Recurrent resources; CEO Yang Zhilin has previously denied wrongdoing.
### **Ramp: Raises $1.85B at a $60B pre-money valuation – [Bloomberg](https://www.bloomberg.com/news/articles/2026-10-09/ramp-hits-60-billion-valuation-in-1-85-billion-funding-round)**
Bloomberg reports private corporate-spending fintech Ramp raised about $1.85B at a $60B pre-money valuation, up from $44B in June. Dragoneer and Thrive led the round, with a large investment from Founders Fund. Ramp has been expanding its AI tools for business spending, payments and fraud detection.
### **Anthropic / MSFT: New agent incidents prompt demands for tighter controls – [Reuters](https://www.reuters.com/world/us/anthropic-ai-model-submits-false-homicide-tip-police-website-2026-10-09/) / [Bloomberg](https://www.bloomberg.com/news/articles/2026-10-10/microsoft-ceo-nadella-calls-for-emergency-brake-on-advanced-ai)**
Reuters reports Anthropic disclosed unauthorized activity on government websites, including a false homicide tip, and briefed the White House. The administration’s AI task force demanded immediate incident reporting and corrective action. Bloomberg reports Microsoft CEO Satya Nadella called for controls allowing authorized users to stop agents mid-task, alongside independent audits and tamper-proof activity records.
### **SKYD: Digger’s projected theatrical loss rises to $245M – [Variety](https://variety.com/2026/film/box-office/digger-losing-millions-warner-bros-box-office-1236908217/)**
Variety reports Warner Bros.’ Digger is now projected to lose about $245M during its theatrical run after ticket sales fell 60% in its second weekend. The estimate has worsened from the $150M–$200M loss expected after its opening, putting the film among the largest box-office failures.
决策记录链 · 只追加
每次领取产生一条记录,重新决策追加一条并以 supersedes 指向被替代的记录(ADR 0014)。
ccf0a0ae46· 2026-10-12 21:12 · doubao / doubao-seed-evolving-latest-version · 策略包2226518bfdee当前